Diffusion Engineers (DIFFNKG) Q2 FY27 Profit Slips 24% QoQ Despite 51% Revenue Surge
The welding consumables maker posted a 50.7% YoY revenue jump in Q2 FY27, but profit fell sequentially as input costs and lower other income squeezed margins.
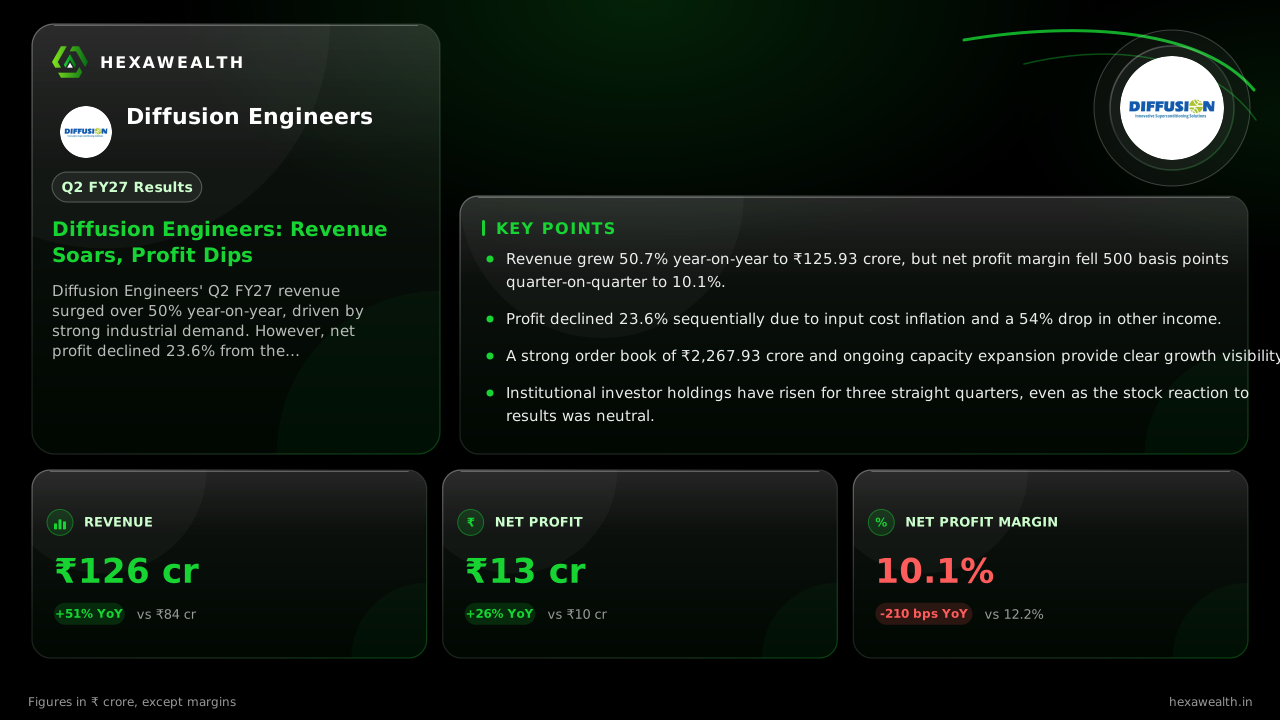
Diffusion Engineers' Q2 FY27 revenue surged over 50% year-on-year, driven by strong industrial demand. However, net profit declined 23.6% from the previous quarter as rising costs and a sharp drop in other income pressured profitability.
For a company riding India's industrial capex wave, top-line growth is the first test. Diffusion Engineers passed it convincingly, with revenue surging over half from a year ago. Yet the quarter's real story is the 500-basis-point sequential squeeze that kept that growth from reaching the bottom line.
Consolidated revenue for the September 2026 quarter hit ₹125.93 crore, a 50.7% leap from the same period last year. Net profit grew a more modest 25.5% year-on-year to ₹12.75 crore. Sequentially, profit fell 23.6% even as revenue rose 14.4%, pulling the net profit margin down to 10.1% from 15.1% in June.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 125.93 | 110.11 |
| Profit (₹ Cr) | 12.75 | 16.68 |
| Net Profit Margin | 10.1% | 15.1% |
Why the profit engine sputtered
Total expenses grew faster than sales, rising 52.7% year-on-year. The company's investor presentation, cited by Arthneeti, blamed geopolitical uncertainties and rising input, energy, and logistics costs. A sharp 54% quarter-on-quarter drop in other income to ₹1.87 crore also removed a tailwind that had boosted the previous quarter's profit.
This cost pressure is an industry-wide theme. A report from Credence Research notes the Indian welding consumables market is growing steadily, but input cost volatility can squeeze margins. A competitor's earnings call highlighted steel price inflation of 7-8% last quarter, a pressure unlikely to ease soon.
The growth runway remains clear
Demand is not the issue. The company reported a robust order book of ₹2,267.93 crore as of September 2026, up 30% from March. Its investor presentation cited strong demand across core industrial segments and higher execution levels.
Management remains optimistic, with the Chairman's message pointing to near-completion of capital expenditure and capacity expansion. According to an August earnings call transcript on Yahoo Finance, new heavy engineering capacity has been doubled and international operations in Turkey and the UAE are ramping up.
Market weighs the mix
Institutional investors have been steadily increasing their stake, with DII and FII holdings rising for three consecutive quarters according to Sector Alpha. The stock, however, was tagged 'Neutral' in post-results analysis by StockFin.ai, reflecting the market's pause over the margin compression.
The valuation gap is stark, with the stock trading at a P/E of 18.5, a 57% discount to the industry average of 42.7. This discounts both the growth potential and the near-term margin risks.
Key Points
- Revenue grew 50.7% year-on-year to ₹125.93 crore, but net profit margin fell 500 basis points quarter-on-quarter to 10.1%.
- Profit declined 23.6% sequentially due to input cost inflation and a 54% drop in other income.
- A strong order book of ₹2,267.93 crore and ongoing capacity expansion provide clear growth visibility.
- Institutional investor holdings have risen for three straight quarters, even as the stock reaction to results was neutral.
Hexa Perspective
The quarter presents a classic growth-versus-margin tension. Diffusion Engineers is successfully capturing industrial demand, evidenced by the soaring revenue and a bulging order book. The capacity expansion, once fully ramped, should support this trajectory.
The near-term challenge is cost recovery. With expenses outpacing sales and industry peers flagging persistent input cost pressure, margin improvement hinges on operational efficiencies and pricing power. Investors are left weighing the compelling long-term growth story against the certainty of near-term profitability pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.