All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 21 November 20262 min read

Millworks (MILLWORKS) Q2 FY27 Posts Q2 Loss as Revenue Recognition Stalls

Millworks Technologies reported a 61% revenue collapse and a net loss in Q2 FY27, with execution delays and a major receivable overhang prompting an auditor's qualified opinion.

By Anant Kacholia, HexaWealth Research · Created 21 November 2026

Millworks Technologies' Q2 FY27 revenue fell 61% year-on-year to ₹17 crore, resulting in a net loss. The gap between a strong ₹230 crore order book and weak cash conversion, highlighted by an auditor's qualification, defines a quarter of stalled execution.

For a company fresh off an IPO and sitting on a ₹230 crore order book, the September quarter was meant to be about execution. Instead, Millworks Technologies reported a revenue collapse, turning last year’s profit into a loss and drawing a qualified opinion from its auditor. The quarter exposed a painful gap between promised growth and delivered cash.

Revenue plunged 61% year-on-year to ₹17 crore. The company swung from a ₹12 crore profit in Q2 FY26 to a ₹2 crore loss this quarter, with the net profit margin contracting by a stark 39 percentage points.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY26 44.0, Q2 FY27 17.0. Q2 FY26 12.0, Q2 FY27 -2.0-80-4004080Q2 FY26Q2 FY27
  • Revenue (₹ Cr), Q2 FY26: 44.0
  • Revenue (₹ Cr), Q2 FY27: 17.0
  • Profit (₹ Cr), Q2 FY26: 12.0
  • Profit (₹ Cr), Q2 FY27: -2.0

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY26 44.0, Q2 FY27 17.0020406080Q2 FY26Q2 FY27
  • Revenue (₹ Cr), Q2 FY26: 44.0
  • Revenue (₹ Cr), Q2 FY27: 17.0

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY26 12.0, Q2 FY27 -2.0-20-1001020Q2 FY26Q2 FY27
  • Profit (₹ Cr), Q2 FY26: 12.0
  • Profit (₹ Cr), Q2 FY27: -2.0

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY26 27.3, Q2 FY27 -11.8-40%-20%0%20%40%Q2 '26Q2 '27
  • Net Profit Margin (%), Q2 FY26: 27.3
  • Net Profit Margin (%), Q2 FY27: -11.8
MetricCurrentQ2 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
17.0YoY -61%
44.0
Profit (₹ Cr)
-2.0YoY -117%
12.0
Net Profit Margin (%)
-11.8YoY -143%
27.3

Why Revenue Recognition Stalled

Management, cited by Alpha Tribe, attributed the weak half to delayed customer and regulatory approvals, which pushed revenue recognition into the second half. About ₹30 crore of work completed in September was booked in October. This timing mismatch left full fixed costs—including employee and finance expenses—running against a bare revenue base, creating an operating loss.

The Credibility Gap

The more material issue is a ₹86.88 crore receivable stuck with a single customer, Quick Pay, for over six months. According to Stockwatch.live, this led the auditor to issue a qualified opinion, flagging uncertainty over the timing of collections and defense order completion. This overhang is 8.2 times the half-yearly revenue, creating a severe working capital strain.

Despite this, the underlying business pipeline appears robust. The order book stands at ₹230 crore, bolstered by a landmark ₹111 crore export defense order. Management, per Alpha Tribe, expects full-year revenue to cross ₹200 crore, implying a massive execution ramp in the coming months.

Live Chart

· MILLWORKS

(BSE)

ISIN: INE1SRC01010

Key Points

  • Revenue collapsed 61% YoY to ₹17 crore due to delayed customer approvals shifting recognition to H2.
  • A net loss of ₹2 crore resulted from fixed costs hitting a deferred revenue base, not a gross margin crash.
  • An auditor's qualified opinion highlights material risk from a ₹86.88 crore receivable stuck with one customer.
  • Management maintains full-year revenue guidance above ₹200 crore, banking on a ₹230 crore order book.

Hexa Perspective

The quarter presents a classic tension between visibility and credibility. The order book is substantial and validated by a major export win, suggesting the demand story is intact. However, the auditor's qualification on receivables is a serious red flag for a newly listed company, questioning internal controls and cash conversion.

The investment case now hinges entirely on second-half execution and the promised December recovery of the large receivable. If both materialize, the narrative can reset from a 'credibility crisis' to a delayed growth story. Any further slip, however, would confirm structural weaknesses in working capital management, likely leading to a prolonged equity re-rating.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
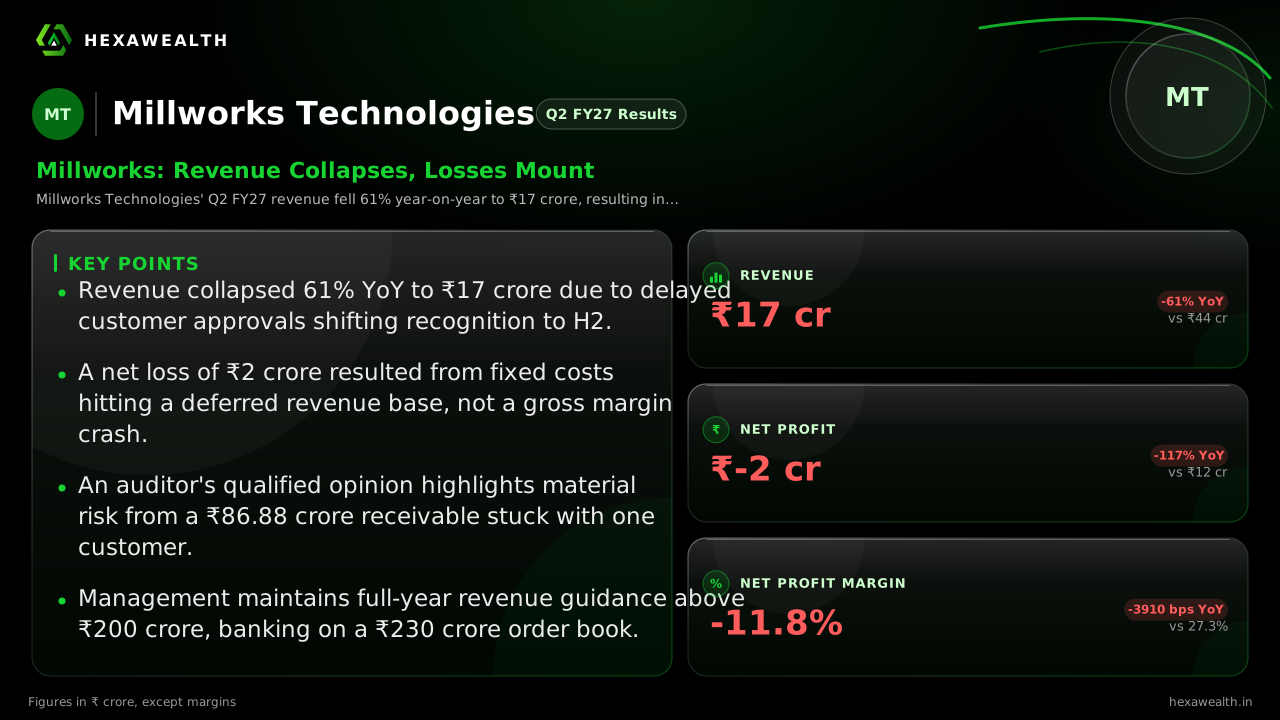
Millworks Technologies (MILLWORKS) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Millworks Technologies' Q2 FY27 results?
Millworks Technologies reported Q2 FY27 revenue of ₹17 crore, a 61% decline from the ₹44 crore reported in Q2 FY26. The company posted a net loss of ₹2 crore for the quarter, compared to a profit of ₹12 crore a year ago. The net profit margin contracted sharply to -11.8%.
Why did Millworks Technologies' Q2 FY27 revenue collapse by over 60%?
Millworks' revenue fell due to delayed customer and regulatory approvals that pushed revenue recognition into the second half. Management, cited by Alpha Tribe, stated that orders worth about ₹30 crore executed in September were recognized in October, creating a timing mismatch that left Q2 revenue bare.
Why did Millworks Technologies report a net loss in Q2 FY27?
Millworks reported a ₹2 crore net loss because full fixed costs, including employee and finance expenses, ran against a severely deferred revenue base. As per Stockwatch.live, this was a result of operating leverage from its new IPO-funded capacity, not a collapse in gross margin, which remained stable around 37%.
What drove the sharp contraction in Millworks' net profit margin?
The net profit margin contracted by 3910 basis points to -11.8% because revenue fell 61% while a significant portion of fixed costs remained. The collapse in the top line, not a drop in gross profitability, turned last year's 27.3% margin into a loss.
What is Millworks Technologies' current order book status?
Millworks Technologies has an order book of ₹230 crore as of November 2026, which is 1.5 times its prior-year annual revenue. This includes a landmark ₹111 crore export defense order, the largest in the company's history, as reported by Alpha Tribe.
What guidance did Millworks management provide for future revenue?
Millworks management, in its earnings call covered by Alpha Tribe, expects full-year FY27 revenue to cross ₹200 crore, driven by the execution of its ₹230 crore order backlog. For FY28, the company is targeting 60% to 70% year-on-year growth.
What is the issue with Millworks' receivables and the auditor's opinion?
Millworks has ₹86.88 crore, or 61% of its total receivables, stuck with one customer, Quick Pay, for 6–8 months. This led the auditor to issue a qualified opinion, citing uncertainty over the timing of recovery and defense order completion, as reported by Stockwatch.live.
When does Millworks expect to recover the ₹86.88 crore from Quick Pay?
Millworks management expects to recover the ₹86.88 crore receivable from Quick Pay in December 2026. This recovery is critical to resolving the working capital overhang and narrowing the scope of the auditor's qualification.
Did Millworks Technologies Q2 FY27 results beat or miss analyst estimates?
The results were a significant miss against any implied expectations, given the 61% revenue decline and a net loss. Post-results, analysis from Stockwatch.live characterized the situation as a 'credibility crisis' and suggested a 'Hold' rating pending proof of execution in the second half.
What are the key client concentration risks for Millworks Technologies?
Millworks faces high customer concentration risk. A single customer, Quick Pay, accounts for 61% of its total receivables (₹86.88 crore). Historically, the top 10 customers have contributed over 90% of revenue, creating significant dependency, as noted in pre-IPO analyses.
Millworks Technologies Q2 profit drop
Millworks Technologies' Q2 FY27 profit dropped 116.7% year-on-year to a loss of ₹2 crore, from a profit of ₹12 crore in Q2 FY26. The loss was driven by a 61% collapse in revenue, as fixed costs from new capacity hit a deferred revenue base.
Millworks Technologies September quarter results
For the September 2026 quarter, Millworks Technologies reported revenue of ₹17 crore and a net loss of ₹2 crore. The results were severely impacted by revenue recognition delays and a large overdue receivable of ₹86.88 crore, which prompted an auditor's qualified opinion.