Shine Fashion (SHINEFASH) Profit Holds as Revenue Declines in Q2 FY27
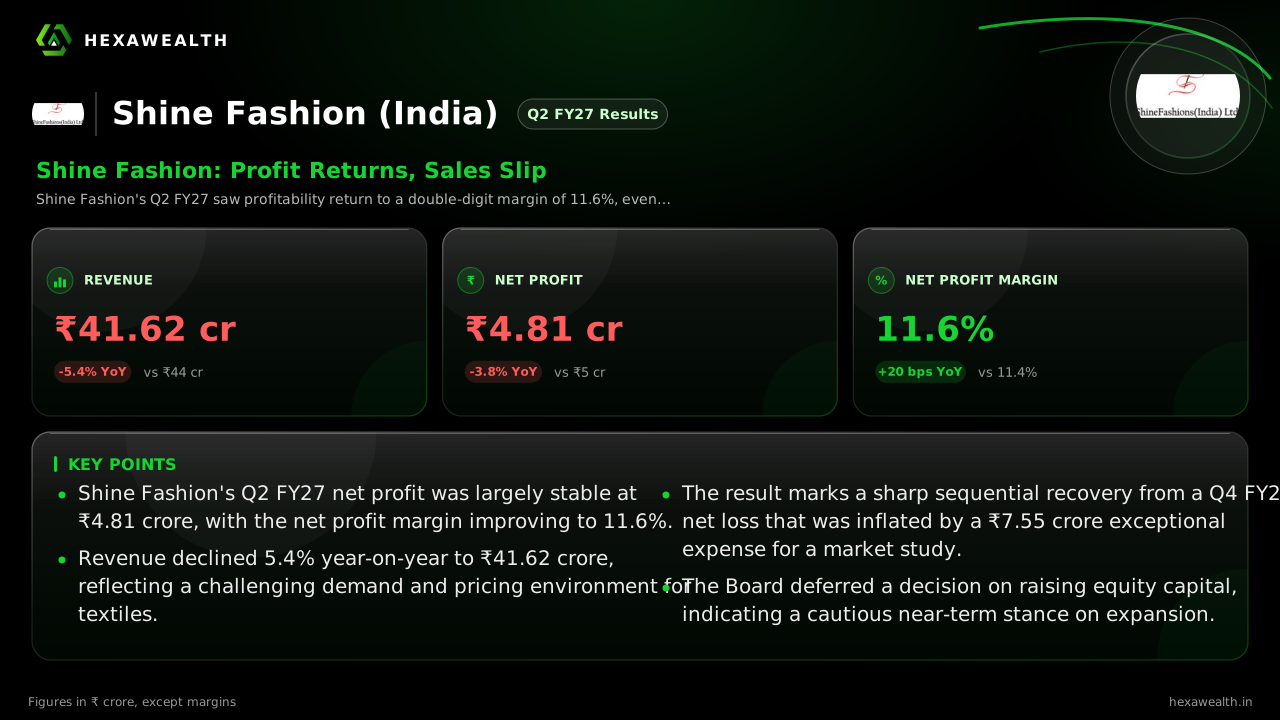
Shine Fashion posted a net profit of ₹4.81 crore in Q2 FY27, but revenue fell 5.4% year-on-year amid a tough textile market.
Shine Fashion's Q2 FY27 saw profitability return to a double-digit margin of 11.6%, even as revenue dipped. The quarter marks a recovery from last quarter's loss, but top-line pressure from rising cotton costs persists.
For a textile trader like Shine Fashion, the quarter was a balancing act between rising input costs and preserving profitability. The company managed to keep its net profit steady year-on-year at ₹4.81 crore, even as revenue slipped to ₹41.62 crore.
The numbers show a business that held its ground on the bottom line. Revenue declined 5.4% from the same quarter last year and fell 28.2% sequentially from a strong Q4. Profit, however, dipped only 3.8% year-on-year, and the net profit margin actually improved to 11.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 34.00
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 47.00
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 44.00
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 58.00
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 41.62
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.00
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 4.00
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 5.00
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -2.00
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.81
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 34.00
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 47.00
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 44.00
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 58.00
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 41.62
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.00
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 4.00
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 5.00
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -2.00
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 4.81
Net Profit Margin
- Net Profit Margin, Q2 FY25 (Sep 2024): 8.8%
- Net Profit Margin, Q4 FY25 (Mar 2025): 8.5%
- Net Profit Margin, Q2 FY26 (Sep 2025): 11.4%
- Net Profit Margin, Q4 FY26 (Mar 2026): -3.4%
- Net Profit Margin, Q2 FY27 (Sep 2026): 11.6%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 41.62 | 58.00 |
| Profit (₹ Cr) | 4.81 | -2.00 |
| Net Profit Margin | 11.6% | -3.4% |
The Margin Story Behind Flat Sales
The steady profit despite lower sales points to disciplined cost control. According to data from Sovrenn, the company's operating margin for the half-year stood at a healthy 16.1%. Total expenses fell 4.9% year-on-year and dropped sharply by 34.8% from the previous quarter, which contained a significant one-off charge.
That prior quarter's loss of ₹2 crore, reports from Mcapital and Tapetide show, was heavily distorted by an exceptional expense of ₹7.55 crore for a strategic market study. Stripping that out, the underlying business has been consistently profitable, and Q2's result represents a return to that norm rather than a new peak.
A Cautious Stance on Growth and Capital
Management's immediate focus appears to be consolidation over aggressive expansion. In its board meeting, the company considered but deferred a proposal to raise funds via equity, as reported by ForgeUp. This suggests a wait-and-see approach towards capital allocation and growth initiatives in the current market.
Live Chart
· SHINEFASH
(BSE)
ISIN: INE0BLY01023
The broader textile environment offers little relief for top-line growth. Industry reports cited by ET Edge Insights note that while export demand is recovering, domestic cotton yarn prices rose approximately 60% over the year. This raw material inflation pressures fabric traders like Shine Fashion, likely constraining sales volume and value.
Key Points
- Shine Fashion's Q2 FY27 net profit was largely stable at ₹4.81 crore, with the net profit margin improving to 11.6%.
- Revenue declined 5.4% year-on-year to ₹41.62 crore, reflecting a challenging demand and pricing environment for textiles.
- The result marks a sharp sequential recovery from a Q4 FY26 net loss that was inflated by a ₹7.55 crore exceptional expense for a market study.
- The Board deferred a decision on raising equity capital, indicating a cautious near-term stance on expansion.
Hexa Perspective
This quarter reveals a company managing for profitability in a tough market. The ability to maintain a double-digit net margin while sales contract shows operational discipline, likely through careful expense management. The valuation, at a P/E of 24.6, trades at a discount to the industry but still prices in this resilience.
The outlook hinges on the trajectory of cotton prices and export demand. If input cost pressures ease, the preserved margin structure could deliver stronger earnings on any sales recovery. However, with the fundraise deferred and working capital days elevated, the capacity for aggressive growth appears limited in the near term.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.