Rapid Multimodal (RAPID) Q2 FY27 Profit Doubles as Efficiency Drive Pays Off
The logistics aggregator's net profit surged 100% sequentially in Q2 FY27, driven by sharp cost control that expanded margins despite modest revenue growth.
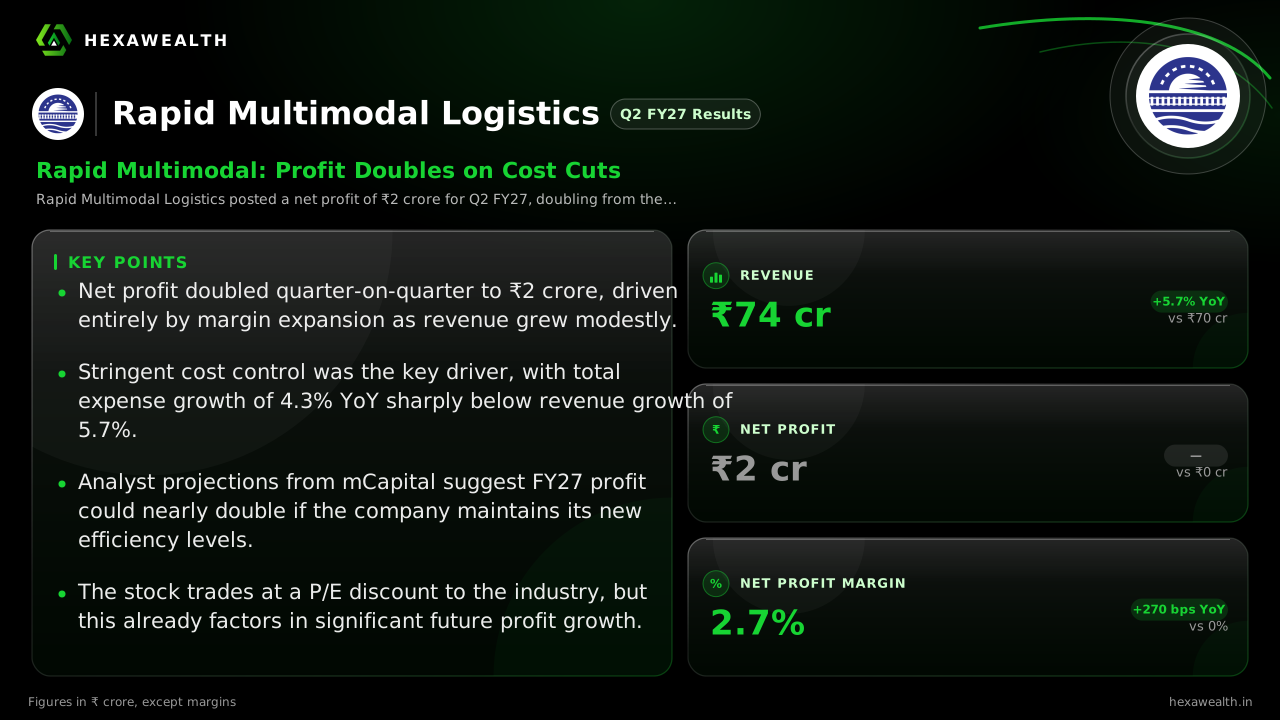
Rapid Multimodal Logistics posted a net profit of ₹2 crore for Q2 FY27, doubling from the previous quarter. The jump was powered by disciplined cost management, which expanded the net profit margin by 130 basis points sequentially.
For Rapid Multimodal Logistics, the story has shifted from chasing top-line growth to making that growth pay. After a year where soaring costs ate into profits, the September quarter shows the efficiency drive finally reaching the bottom line.
The numbers tell a clear turnaround. Revenue grew a steady 5.7% year-on-year to ₹74 crore. Profit, however, told a different story, doubling sequentially to ₹2 crore. The net profit margin jumped 270 basis points from a year ago to 2.7%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 44.0
- Revenue (₹ Cr), Q4 FY25: 59.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 73.0
- Revenue (₹ Cr), Q2 FY27: 74.0
- Net Profit (₹ Cr), Q2 FY25: 1.0
- Net Profit (₹ Cr), Q4 FY25: 1.0
- Net Profit (₹ Cr), Q2 FY26: 0.0
- Net Profit (₹ Cr), Q4 FY26: 1.0
- Net Profit (₹ Cr), Q2 FY27: 2.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 44.0
- Revenue (₹ Cr), Q4 FY25: 59.0
- Revenue (₹ Cr), Q2 FY26: 70.0
- Revenue (₹ Cr), Q4 FY26: 73.0
- Revenue (₹ Cr), Q2 FY27: 74.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY25: 1.0
- Net Profit (₹ Cr), Q4 FY25: 1.0
- Net Profit (₹ Cr), Q2 FY26: 0.0
- Net Profit (₹ Cr), Q4 FY26: 1.0
- Net Profit (₹ Cr), Q2 FY27: 2.0
Net Profit Margin
- Net Profit Margin, Q2 FY25: 2.3%
- Net Profit Margin, Q4 FY25: 1.7%
- Net Profit Margin, Q2 FY26: 0.0%
- Net Profit Margin, Q4 FY26: 1.4%
- Net Profit Margin, Q2 FY27: 2.7%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 74.0YoY +5.7% | 70.0 |
| Net Profit (₹ Cr) | 2.0 | 0.0 |
| Net Profit Margin | 2.7% | 0.0% |
Why Margins Finally Expanded
The profit surge was not driven by a revenue spike but by a tight grip on expenses. According to a ScanX report, total expenses rose just 4.3% year-on-year, well below the revenue growth rate. This allowed significant operating leverage to kick in.
Key cost lines saw notable reductions. ScanX data shows employee benefit expenses fell 18% and other expenses dropped 10% year-on-year. This disciplined approach reversed the margin pressure that plagued the company through FY26, when costs had outpaced sales.
The Outlook and Market Read
The company has not provided formal guidance, but analysts are building projections based on the new margin run-rate. mCapital's analysis, cited in research, projects FY27 profit could rise 70-90% from the FY26 base if current trends hold.
Live Chart
· RAPID
(BSE)
ISIN: INE0QA901010
This implies full-year profit could reach ₹3.4–3.8 crore. Investors are weighing this potential against a valuation that trades at a P/E of 37.4, a discount to the industry average of 48.9.
Key Points
- Net profit doubled quarter-on-quarter to ₹2 crore, driven entirely by margin expansion as revenue grew modestly.
- Stringent cost control was the key driver, with total expense growth of 4.3% YoY sharply below revenue growth of 5.7%.
- Analyst projections from mCapital suggest FY27 profit could nearly double if the company maintains its new efficiency levels.
- The stock trades at a P/E discount to the industry, but this already factors in significant future profit growth.
Hexa Perspective
The quarter marks a clear inflection from a growth-at-all-costs model to a more profitable scale-up. The evidence of operating leverage is convincing, but its sustainability is the critical test.
For the improved margin profile to hold, the company must continue its cost discipline amid potential fuel price volatility and a competitive pricing environment. The current valuation suggests the market is giving credit for this transition, leaving less room for execution slips.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.