Makers Laboratories (MAKERSL) Q2 FY27 Profit Jumps 1037% as Margins Expand Sharply
The pharmaceutical company's Q2 FY27 saw a dramatic profit turnaround, driven by operational scale and a strategic shift towards higher-margin businesses.
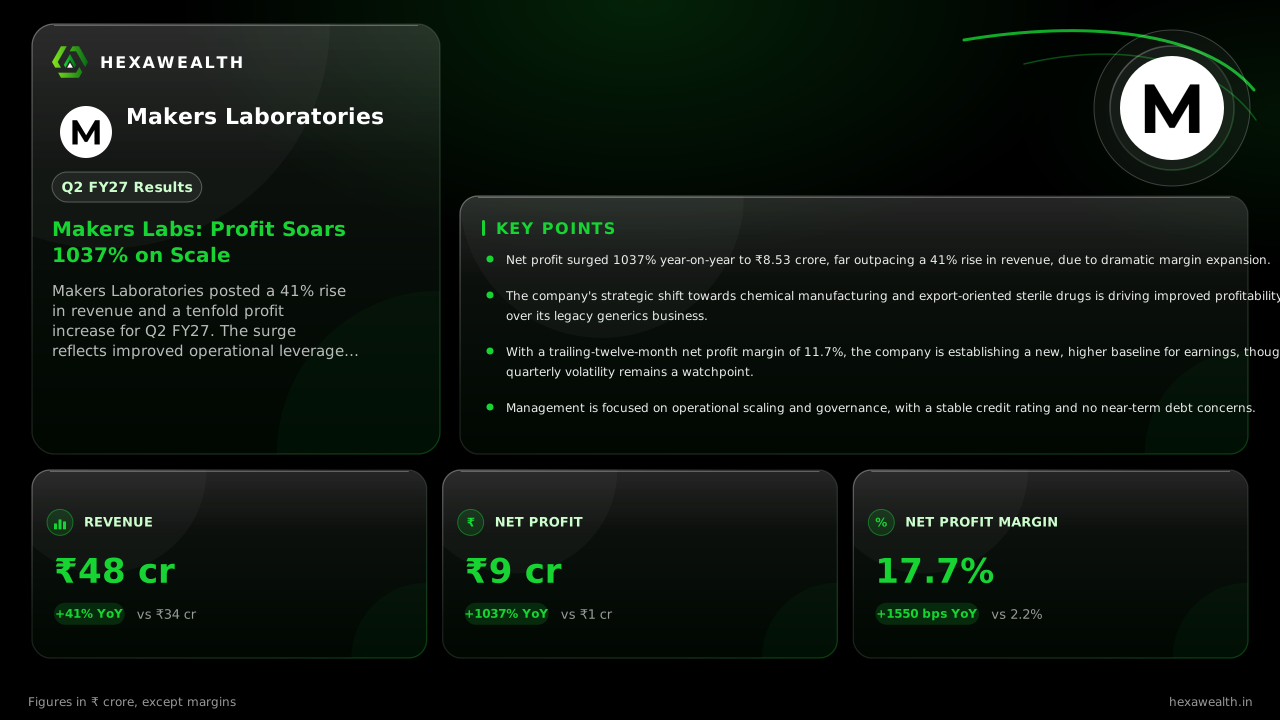
Makers Laboratories posted a 41% rise in revenue and a tenfold profit increase for Q2 FY27. The surge reflects improved operational leverage as the company transitions from a legacy generics business.
For Makers Laboratories, the September quarter marked a decisive shift from a legacy generics player to a more profitable, scaled operation. Revenue grew 41% year-on-year to ₹48.21 crore, but the real story was a 1037% surge in net profit to ₹8.53 crore, signaling a fundamental improvement in earnings quality.
The numbers show a clear trajectory of operating leverage. While revenue has climbed for four consecutive quarters, profit growth has accelerated even faster. The net profit margin expanded to 17.7%, a 700 basis point improvement from the June quarter and a massive 1,550 point jump from a weak year-ago base.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 48.21 | 42.77 |
| Profit (₹ Cr) | 8.53 | 4.60 |
| Net Profit Margin | 17.7% | 10.7% |
The Engine Behind the Margin Leap
The profit surge stems from a strategic business shift, not a one-off event. Analysis from StockScans.in notes the company's centre of gravity has moved to its chemical manufacturing subsidiary, Resonance Specialties, which now generates over half of group revenue. This, along with an export-focused sterile manufacturing platform for injectables and eye drops, is driving better margins than the legacy domestic generics business.
Operational discipline is also evident. Total expenses grew just 0.9% quarter-on-quarter against a 12.7% revenue increase, showing strong cost control. Interest costs fell 31% year-on-year, aided by a conservative debt-to-equity ratio of 0.07.
A Transition in Progress
Management has not provided explicit forward guidance, according to StockFin.ai. The focus appears to be on validating this sustained performance, with the board recently approving a new non-executive director for governance continuity. The company's credit rating was reaffirmed at BBB+ Stable in September 2026, indicating financial stability.
The key risk, noted by Univest.in, is quarterly profit volatility. While the recent trend is sharply up, the company must demonstrate it can maintain this new level of profitability. The full-year FY26 net profit margin was just 1.7%, highlighting how recent quarters represent a significant departure from the past.
Key Points
- Net profit surged 1037% year-on-year to ₹8.53 crore, far outpacing a 41% rise in revenue, due to dramatic margin expansion.
- The company's strategic shift towards chemical manufacturing and export-oriented sterile drugs is driving improved profitability over its legacy generics business.
- With a trailing-twelve-month net profit margin of 11.7%, the company is establishing a new, higher baseline for earnings, though quarterly volatility remains a watchpoint.
- Management is focused on operational scaling and governance, with a stable credit rating and no near-term debt concerns.
Hexa Perspective
The quarter confirms Makers Laboratories is in a tangible turnaround, moving from negligible profitability to double-digit margins. The improvement appears structural, linked to a changing business mix and operating leverage, rather than just a low base effect.
The sustainability of these margins is the critical question. It hinges on the continued ramp-up of its export sterile manufacturing platform and stable performance of the chemical subsidiary. If the company can report another quarter of margin stability, it will signal this is a durable step-change, not a fleeting peak.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.