Maheshwari Logistics (MAHESHWARI) Q2 FY27 Profit Rises 7% as Revenue Rebounds, But Debt Weighs on Margins
The logistics firm posted a 7% yearly profit gain on a 14.7% sequential revenue recovery, yet high interest costs and a debt-heavy balance sheet keep profitability thin.
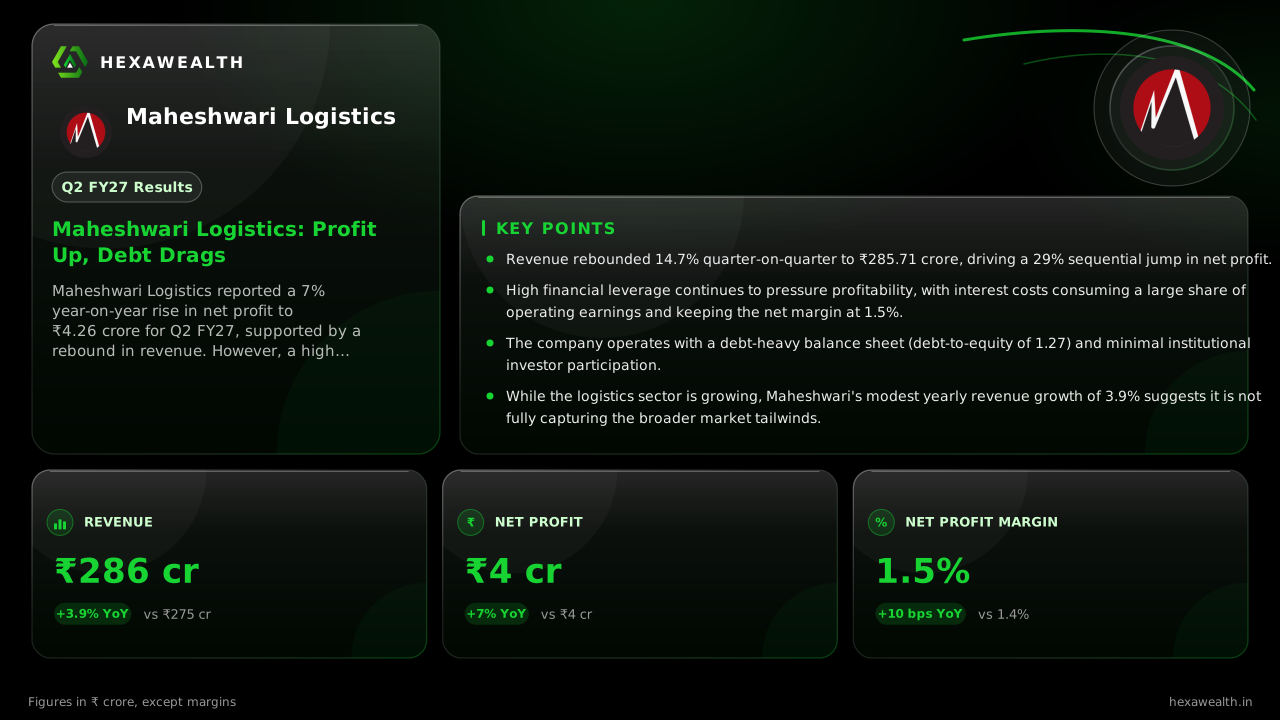
Maheshwari Logistics reported a 7% year-on-year rise in net profit to ₹4.26 crore for Q2 FY27, supported by a rebound in revenue. However, a high debt load continues to pressure margins, with interest consuming a large portion of operating earnings.
For Maheshwari Logistics, the September quarter was about recovering from a soft June period. The company's diverse operations in trading, manufacturing, and transport saw revenue bounce back sequentially, lifting profit. Yet, the underlying story remains one of thin margins constrained by a significant debt burden.
The numbers show a clear recovery path. Revenue reached ₹285.71 crore, up 3.9% from a year ago and a sharp 14.7% from the previous quarter. Net profit followed, rising 7% year-on-year to ₹4.26 crore. The net profit margin improved slightly to 1.5%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 285.71 | 249.00 |
| Net Profit (₹ Cr) | 4.26 | 3.30 |
| Net Profit Margin | 1.5% | 1.3% |
The Cost That Won't Budge
Profit before tax actually fell 2.5% from a year ago. The reason lies in the cost structure. Employee expenses rose nearly 9% year-on-year, while other income fell sharply by 24.9%. Most critically, interest costs of ₹8.05 crore absorbed a large part of operating earnings. A Univest.in preview noted that interest of ₹8-9 crore a quarter sits against operating profit of ₹16-18 crore, meaning roughly half goes to servicing debt.
This is not a one-quarter issue. The company's debt-to-equity ratio stands at 1.27, and its interest cover is a low 1.67 times. These figures, from the verified payload, show limited room to absorb further rate hikes or a slowdown. The absence of institutional investors, as noted in a Stockfin.ai analysis, may also reflect concerns over this financial leverage.
A Sector in Motion, A Company in Place
The broader logistics environment is active. A Knight Frank India report cited by IANS Live noted warehousing leasing rose 12% year-on-year in Q3 2026, driven by manufacturing and third-party logistics demand. However, Maheshwari's revenue growth of 3.9% year-on-year lags this sector momentum, suggesting its specific business mix or competitive positioning may be a factor.
Management has not provided explicit forward guidance, according to Stockfin.ai. The company's focus appears to be on operational stability rather than aggressive expansion. The lack of a dividend for FY26 suggests retained earnings are being preserved, possibly for debt management.
Key Points
- Revenue rebounded 14.7% quarter-on-quarter to ₹285.71 crore, driving a 29% sequential jump in net profit.
- High financial leverage continues to pressure profitability, with interest costs consuming a large share of operating earnings and keeping the net margin at 1.5%.
- The company operates with a debt-heavy balance sheet (debt-to-equity of 1.27) and minimal institutional investor participation.
- While the logistics sector is growing, Maheshwari's modest yearly revenue growth of 3.9% suggests it is not fully capturing the broader market tailwinds.
Hexa Perspective
The quarter shows Maheshwari Logistics can generate a profit recovery when its top line improves. The sequential bounce is encouraging after a weak Q1. However, the structural constraint is evident. With interest cover barely above 1.5 times, earnings are highly sensitive to any increase in borrowing costs or a dip in operating profit.
The path to sustainable shareholder returns likely requires a material reduction in debt. Until that happens, even decent revenue performance will translate into only slender net profits. Investors are weighing this modest growth against the significant balance sheet risk, which explains the stock's deep discount to the industry average P/E.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.