Aeron Composite (AERON) Profit Falls 36% Despite 11% Revenue Growth in Q2 FY27
The fiberglass products maker saw sales rise to ₹130 crore, but profits were squeezed by higher depreciation and interest costs from a major capacity expansion.
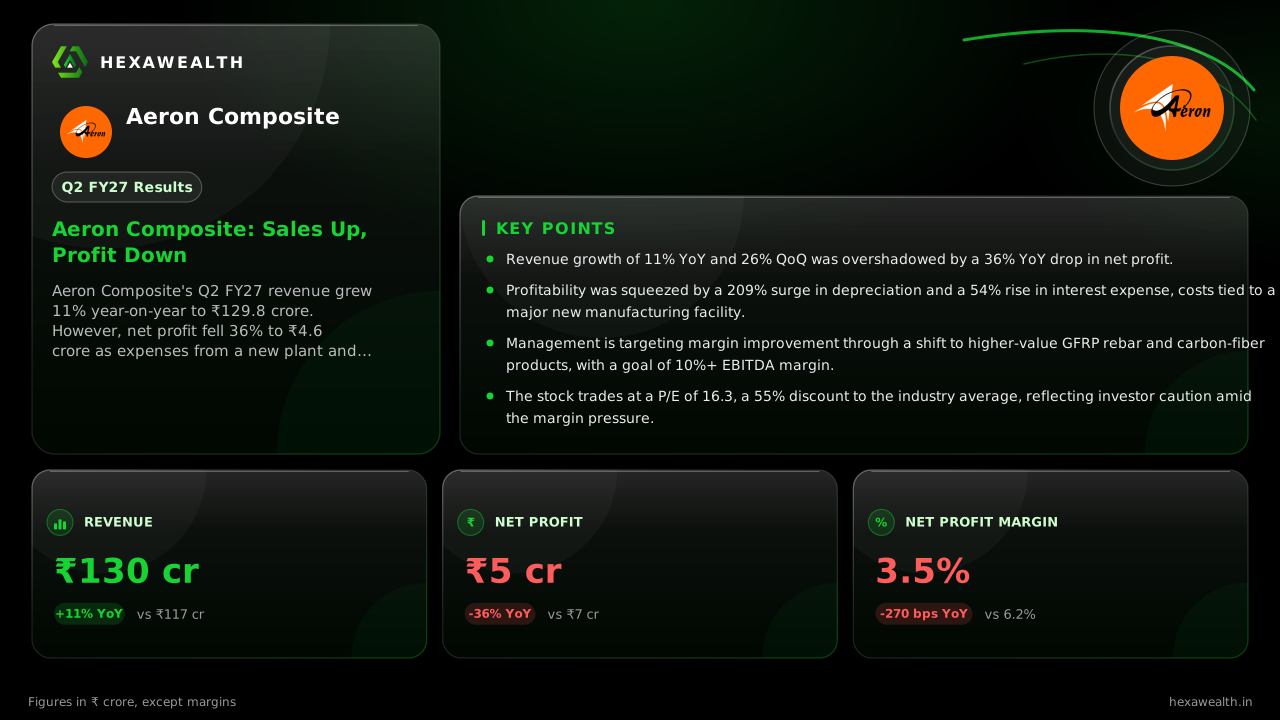
Aeron Composite's Q2 FY27 revenue grew 11% year-on-year to ₹129.8 crore. However, net profit fell 36% to ₹4.6 crore as expenses from a new plant and higher interest costs compressed margins.
For Aeron Composite, a manufacturer of corrosion-proof fiberglass products, the September quarter was a story of building for the future while paying for it today. Revenue grew, but the cost of a major new factory and the debt to fund it kept a firm lid on profitability.
Sales rose 11% year-on-year to ₹129.8 crore, a solid sequential jump from the ₹103 crore reported in the March 2026 quarter. Yet net profit fell 36% from the same period last year to ₹4.6 crore, as the net profit margin compressed by 270 basis points to 3.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 129.81 | 103.01 |
| Profit (₹ Cr) | 4.60 | 1.48 |
| Net Profit Margin | 3.5% | 1.4% |
The cost of a bigger factory
The profit squeeze stems directly from the company's expansion. Depreciation expense surged 209% year-on-year, while interest costs jumped 54%. According to the company's FY26 annual report, cited by Newboard, this reflects the larger asset base after commissioning a fully-owned 51,671-square-metre facility in Mehsana, Gujarat.
Raw materials, primarily glass fiber and resin, already make up about 65% of manufacturing costs. The Newboard report notes that last year's profit fell when polymer prices rose faster than Aeron could pass them on. Now, fixed costs from the new plant add another layer of pressure.
A pivot to higher-margin products
Management is betting that new products will improve the margin profile. The company is pivoting towards glass-fiber reinforced polymer (GFRP) rebar and planned carbon-fiber products, according to an Alfafinder report. Each new rebar line can generate ₹5-7 crore of annual revenue.
In its June 2026 investor presentation, the company guided for revenue growth of at least 15% annually over three years and an EBITDA margin of 10% or more. It aims to increase rebar production lines from two to five by FY27 and launch carbon-fiber products by the first half of FY27.
The market's wait-and-see stance
The stock has reflected the challenging transition, falling 34% over the past year to close at ₹72.95 on November 4. While the company trades at a significant discount to the industry average P/E, an analysis by Equitytale suggested the stock looked overpriced relative to several valuation models based on its filings.
With capacity utilization reported at just 48% in FY26, the immediate task is filling the new plant. The promised margin expansion hinges on successfully ramping up new, higher-value product lines and improving plant efficiency.
Key Points
- Revenue growth of 11% YoY and 26% QoQ was overshadowed by a 36% YoY drop in net profit.
- Profitability was squeezed by a 209% surge in depreciation and a 54% rise in interest expense, costs tied to a major new manufacturing facility.
- Management is targeting margin improvement through a shift to higher-value GFRP rebar and carbon-fiber products, with a goal of 10%+ EBITDA margin.
- The stock trades at a P/E of 16.3, a 55% discount to the industry average, reflecting investor caution amid the margin pressure.
Hexa Perspective
This quarter underscores the classic growth-investment trade-off. Aeron Composite has built significant capacity in a promising niche—corrosion-resistant materials for infrastructure. The revenue growth suggests demand is there.
The next few quarters will test whether the company can achieve the operating leverage it needs. Success depends on two factors: raising plant utilization from its current sub-50% level and achieving the planned mix shift to higher-margin rebar and carbon fiber. Until those are visible in the margins, profits will likely remain under pressure despite top-line gains.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.