Dollex Agrotech (DOLLEX) Q2 FY27 Profit Stalls Even as Revenue Nearly Doubles
Dollex Agrotech's Q2 FY27 revenue surged 95% sequentially, but net profit was unchanged as rising costs halved the profit margin.
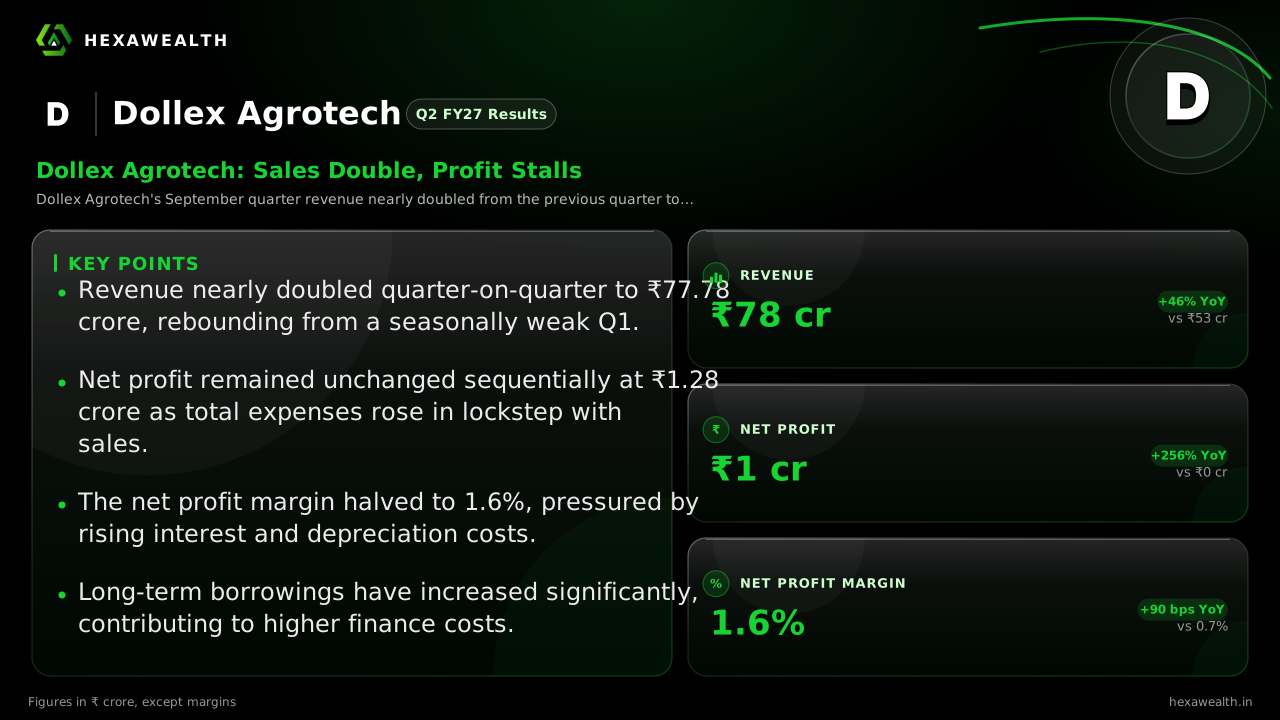
Dollex Agrotech's September quarter revenue nearly doubled from the previous quarter to ₹77.78 crore. However, net profit remained flat at ₹1.28 crore as total expenses rose sharply, squeezing the net profit margin to 1.6%.
For Dollex Agrotech, the September quarter delivered a powerful sales rebound but left profitability stuck in place. Revenue nearly doubled from a seasonally weak June quarter, yet net profit did not budge, highlighting a margin squeeze that defines the current challenge.
The numbers show a stark divergence. Revenue jumped 94.7% quarter-on-quarter to ₹77.78 crore, also rising 45.8% from a year ago. Net profit, however, was flat sequentially at ₹1.28 crore, even as it grew 255.6% year-on-year from a very low base. The net profit margin halved from 3.2% in Q1 to just 1.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 77.78 | 39.95 |
| Profit (₹ Cr) | 1.28 | 1.28 |
| Net Profit Margin (%) | 1.6 | 3.2 |
Why the profit didn't follow sales
A 99% surge in total expenses consumed nearly all the extra revenue. Interest costs rose 27.6% and depreciation was up 11%, according to the analysis. The company's core business profit grew 353.6% year-on-year, as noted by FlashFinance, showing operational improvement but not enough to offset the sequential cost jump.
The debt and policy backdrop
Financing this growth has come with higher leverage. Long-term borrowings rose to ₹177.21 crore as of September 2026, up from ₹137.64 crore in March 2025, per Arthneeti. This contributed to the rising interest burden. Meanwhile, a major policy shift is unfolding. The government has barred procurement of ethanol from sugarcane juice for 2026-27 to prioritise sugar availability, reports The Week.
This move redirects the industry's ethanol focus towards grains, potentially altering long-term revenue streams for sugar mills like Dollex. The company has received in-principle approval for a distillery, but the new policy may affect its plans.
How long can this last?
The margin pressure is unlikely to ease soon with debt levels elevated. MarketsMojo rates the stock a 'Sell', citing high leverage and flat financial trends. The stock trades at a P/E of 13.0, a 52.6% discount to the industry average, reflecting these concerns. With capital work in progress at over ₹90 crore, the company is still investing for growth amid these headwinds.
Key Points
- Revenue nearly doubled quarter-on-quarter to ₹77.78 crore, rebounding from a seasonally weak Q1.
- Net profit remained unchanged sequentially at ₹1.28 crore as total expenses rose in lockstep with sales.
- The net profit margin halved to 1.6%, pressured by rising interest and depreciation costs.
- Long-term borrowings have increased significantly, contributing to higher finance costs.
Hexa Perspective
The quarter reveals a business growing its top line but struggling to convert that into bottom-line momentum. The year-on-year profit surge is flattered by a very weak base in Q2 FY26, when net profit was just ₹0.36 crore. The real story is the sequential margin compression.
Investors are weighing sales recovery against persistent cost pressures and a shifting regulatory landscape for ethanol. The company's expansion, seen in rising capital work, adds capacity but also debt. For the profit story to improve, Dollex needs to demonstrate operating leverage—where revenue growth outpaces cost growth—which was absent this quarter.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.