Teja Engineering (TEJA) Q2 FY27 Profit Jumps 52% as a Lower Tax Bill Boosts the Bottom Line
Revenue grew 15% sequentially, but a sharp drop in the tax expense was the primary driver for the 52% surge in net profit for the September quarter.
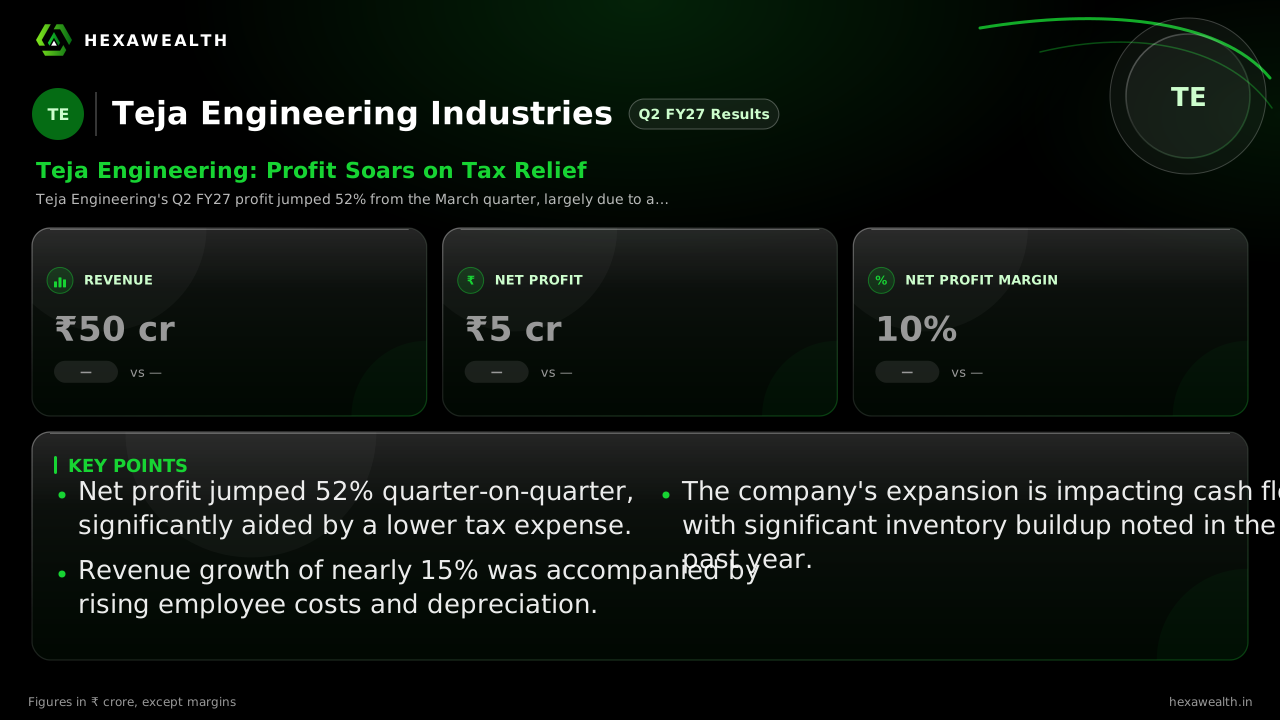
Teja Engineering's Q2 FY27 profit jumped 52% from the March quarter, largely due to a significantly lower tax provision. Revenue rose nearly 15%, but employee costs and depreciation also climbed sharply.
For Teja Engineering, a newly listed engineering services firm, the September quarter was about converting top-line growth into a stronger bottom line. The company delivered a sharp jump in profit, though the driver was more financial than operational.
The numbers show a business scaling up. Revenue rose 14.8% sequentially to ₹50.5 crore, while net profit surged 52.1% to ₹5.05 crore. This pushed the net profit margin to 10.0%, a 240 basis point improvement from the March quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 |
|---|---|
| Period | Sep 2026 |
| Revenue (₹ Cr) | 50.5 |
| Profit (₹ Cr) | 5.05 |
| Net Profit Margin | 10.0% |
Why Profit Outpaced Revenue
The profit surge was not matched by profit before tax, which grew a more modest 16.7%. The key difference was a 73.8% sequential drop in the tax provision, from ₹1.30 crore to ₹0.34 crore. This one-time tax relief provided a substantial lift to the final profit number.
Operating costs rose in step with revenue. Total expenses increased 13.8%, led by a 34.8% jump in employee costs, likely linked to project staffing. Depreciation also rose sharply by 169%, as noted by Flash Finance, indicating recent capital asset additions.
The Working Capital Trade-Off
Growth is coming with a working capital cost. Research from Flash Finance highlights that the company's operating cash flow turned negative in FY26 due to a near-doubling of inventory. This suggests revenue growth is being funded by building up assets and potentially higher borrowings.
The company's debt-to-equity ratio stands at 1.0, according to the payload, indicating a balanced but leveraged capital structure as it funds its expansion.
Key Points
- Net profit jumped 52% quarter-on-quarter, significantly aided by a lower tax expense.
- Revenue growth of nearly 15% was accompanied by rising employee costs and depreciation.
- The company's expansion is impacting cash flow, with significant inventory buildup noted in the past year.
Hexa Perspective
This quarter shows Teja Engineering successfully growing its topline in a supportive infrastructure environment. However, the quality of earnings is mixed. The profit boost was heavily reliant on a lower tax outlay, while core operating costs are rising.
The real test will be sustaining growth while improving cash conversion. The inventory buildup and associated working capital needs, as flagged in earlier reports, will demand careful management as the company executes its order book.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.