LAPL Automotive Q2 FY27 Profit Drops 10.5% as Costs Outpace 4% Revenue Growth
LAPL Automotive's Q2 FY27 saw a clear margin squeeze, with profit falling despite a modest revenue increase as the company invested heavily ahead of a new plant.
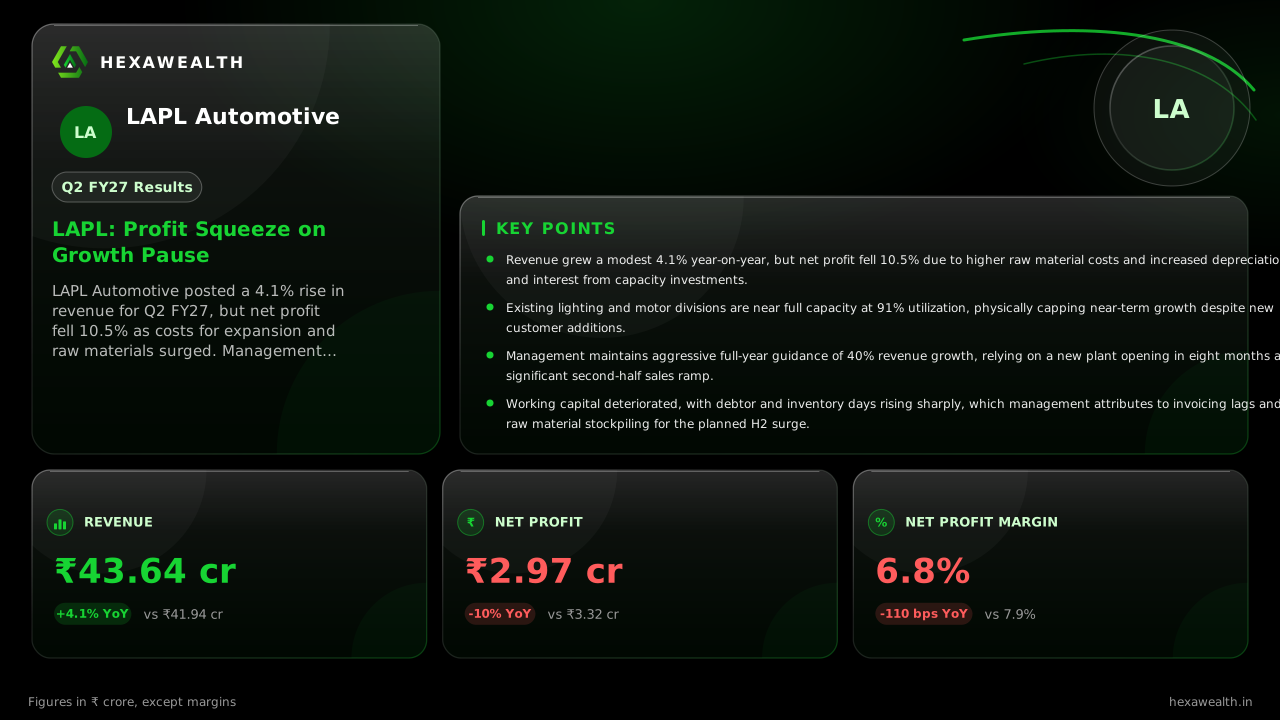
LAPL Automotive posted a 4.1% rise in revenue for Q2 FY27, but net profit fell 10.5% as costs for expansion and raw materials surged. Management maintains a 40% full-year growth target, hinging on a new facility and a sharp second-half ramp.
For LAPL Automotive, the September quarter was a story of investment before the payoff. The auto component maker delivered modest top-line growth while absorbing the full cost of preparing for a major capacity expansion, leading to a clear profit squeeze.
Revenue for the quarter ended September 2026 grew 4.1% year-on-year to ₹43.64 crore. However, net profit declined 10.5% to ₹2.97 crore. The net profit margin compressed by 110 basis points to 6.8%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 41.94
- Revenue (₹ Cr), Q2 FY27: 43.64
- Net Profit (₹ Cr), Q2 FY26: 3.32
- Net Profit (₹ Cr), Q2 FY27: 2.97
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 41.94
- Revenue (₹ Cr), Q2 FY27: 43.64
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY26: 3.32
- Net Profit (₹ Cr), Q2 FY27: 2.97
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 7.9
- Net Profit Margin (%), Q2 FY27: 6.8
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 43.64YoY +4.1% | 41.94 |
| Net Profit (₹ Cr) | 2.97YoY -11% | 3.32 |
| Net Profit Margin (%) | 6.8YoY -14% | 7.9 |
The Costs of Building Ahead
Total expenses rose 6.8%, outpacing revenue growth. Management, cited in the earnings call, explained that raw material costs took a higher share of revenue. The company also added to its team for new programs.
Below the operating line, the pressure was more pronounced. Depreciation surged 30.9% and interest expense jumped 22.6% as LAPL invested in new machinery and capacity. These are the upfront costs of a growth phase that has yet to generate sales.
A Capacity Ceiling and a Promising Pipeline
The modest 4% revenue growth came despite a robust automotive market. Management pointed to a key constraint: its lighting and motor divisions were running at about 91% utilization. This capacity ceiling limited its ability to fulfill new orders immediately.
Live Chart
· LAPL
(BSE)
ISIN: INE0X9I01023
The promise lies in what comes next. The company has begun constructing a fourth manufacturing plant, funded by ₹19.56 crore of its IPO proceeds. According to the concall transcript, this facility is expected to be operational in about eight months, focusing entirely on the higher-margin lighting division.
New customer wins add to the outlook. LAPL added three global vendor codes and started supplying EV makers like Samarth E-Mobility. Its mirror order book reportedly reached 75,000 units. Management, as reported by StockWatch, is guiding for a conservative 40% revenue growth for FY27, implying a dramatic second-half acceleration.
The Market's Wait-and-See Stance
The stock fell 2.3% the day after the earnings call, underperforming the Nifty 50. Analysis from StockWatch noted the stock's repricing reflects high execution risk. Investors are being asked to trust a 76% second-half growth acceleration after a 4% first-half showing, with margin recovery dependent on new volumes.
The quarter underscores a classic transition. Profitability is being sacrificed today to fund the capacity and customer pipeline for tomorrow. The investment case now rests entirely on the timely ramp-up of the new plant and the conversion of its promising order book into sustained revenue.
Key Points
- Revenue grew a modest 4.1% year-on-year, but net profit fell 10.5% due to higher raw material costs and increased depreciation and interest from capacity investments.
- Existing lighting and motor divisions are near full capacity at 91% utilization, physically capping near-term growth despite new customer additions.
- Management maintains aggressive full-year guidance of 40% revenue growth, relying on a new plant opening in eight months and a significant second-half sales ramp.
- Working capital deteriorated, with debtor and inventory days rising sharply, which management attributes to invoicing lags and raw material stockpiling for the planned H2 surge.
Hexa Perspective
This quarter places LAPL at an inflection point. The 4% revenue growth and margin compression are the visible costs of investing ahead of demand. The thesis is straightforward: if the new plant opens on schedule and the promised order flow from new global vendors materializes in the second half, the current profit squeeze will look like a necessary prelude to scaling.
The risks are equally clear. The guidance requires a near-quadrupling of the growth rate in the next six months. Any delay in plant commissioning or customer order conversion would break the narrative, leaving the company with higher costs but not the intended growth. Investors are effectively underwriting a execution-dependent turnaround story in the making.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.