Kwick Forensic (KWICK) Q2 FY27 Profit Jumps 20% Despite Revenue Dip
Kwick Forensic posted a 20% yearly profit rise in Q2 FY27, but revenue fell sharply from the previous quarter as government payment cycles stretched.
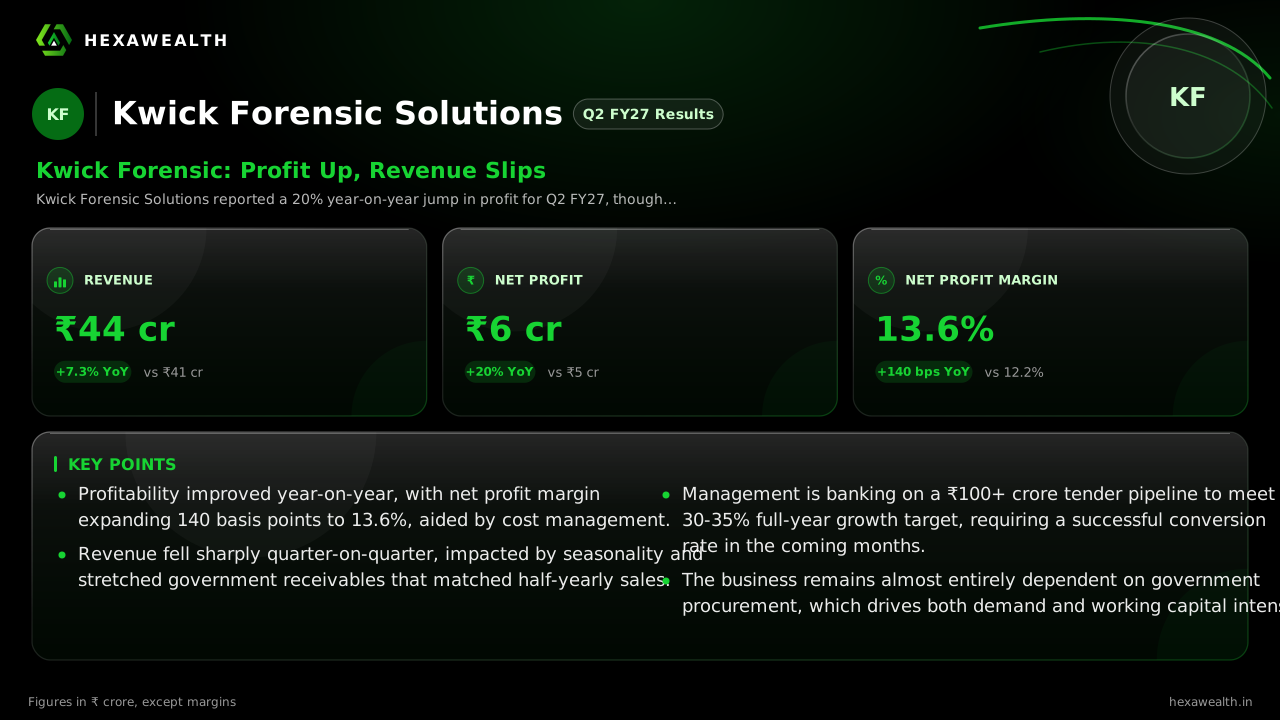
Kwick Forensic Solutions reported a 20% year-on-year jump in profit for Q2 FY27, though revenue fell 32% sequentially. The company's margin improved, but its growth hinges on converting a large tender pipeline.
For Kwick Forensic, the story this quarter is one of profitability holding up as revenue takes a seasonal step back. The forensic solutions provider managed to lift its net profit by a fifth compared to last year, even as its top line fell sharply from the March quarter's high.
The numbers show a business in transition. Revenue of ₹44 crore was up 7.3% from a year ago but down 32.3% from the previous quarter. Profit followed a similar path, rising 20% year-on-year to ₹6 crore but falling 33.3% quarter-on-quarter. The net profit margin improved to 13.6%, up 140 basis points from last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 41.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 65.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 44.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 5.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 9.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 41.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 65.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 44.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 5.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 9.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 12.2
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 13.8
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 13.6
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 44.0 | 65.0 |
| Profit (₹ Cr) | 6.0 | 9.0 |
| Net Profit Margin (%) | 13.6 | 13.8 |
The Squeeze from Government Payments
The sequential drop is partly seasonal, but a key pressure point is cash collection. According to the earnings call summary by ALFA Finder, trade receivables stood at about ₹44 crore against H1 revenue of ₹43.7 crore. This reflects the 90-120 day payment cycle typical of government clients, who make up over 90% of sales.
Management, cited in a Sovrenn report, says collections should improve in the second half as government budgets are released. The company's recent IPO has bolstered its balance sheet, providing a ₹41 crore cushion. This working capital support is critical for executing new orders without a cash crunch.
A Pipeline of Promises
The immediate future rests on converting promises into billed sales. Management, in the Q2 concall, reaffirmed full-year revenue growth guidance of 30-35%. This is ambitious, requiring roughly ₹80 crore of business in the second half.
Live Chart
· KWICK
(BSE)
ISIN: INE1SFA01019
Confidence stems from a tender pipeline exceeding ₹100 crore. Reports from MarketPing note the company's historical hit ratio is 70-75%. If that holds, it could translate to ₹70-75 crore of new orders executable within this financial year, given most projects wrap up in 45-60 days.
Key Points
- Profitability improved year-on-year, with net profit margin expanding 140 basis points to 13.6%, aided by cost management.
- Revenue fell sharply quarter-on-quarter, impacted by seasonality and stretched government receivables that matched half-yearly sales.
- Management is banking on a ₹100+ crore tender pipeline to meet its 30-35% full-year growth target, requiring a successful conversion rate in the coming months.
- The business remains almost entirely dependent on government procurement, which drives both demand and working capital intensity.
Hexa Perspective
The quarter underscores the operational reality of a government-focused forensic integrator. Profitability is demonstrating resilience, but growth is lumpy and tied to the pace of public tenders and payments.
The guidance implies a significant execution leap in H2. Investors are weighing a strong market tailwind—with India's digital forensics market projected to grow rapidly—against the company's ability to consistently win and convert large tenders. The recent IPO provides a runway, but the stock's reaction suggests the market is looking for more tangible evidence of that pipeline turning into revenue.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.