Gujarat Peanut (GPAPL) Q2 FY27's Profit Lags Behind a 56% Revenue Surge
The agri-processor posted its highest quarterly revenue yet, but rising costs kept profit growth in check and squeezed margins sequentially.
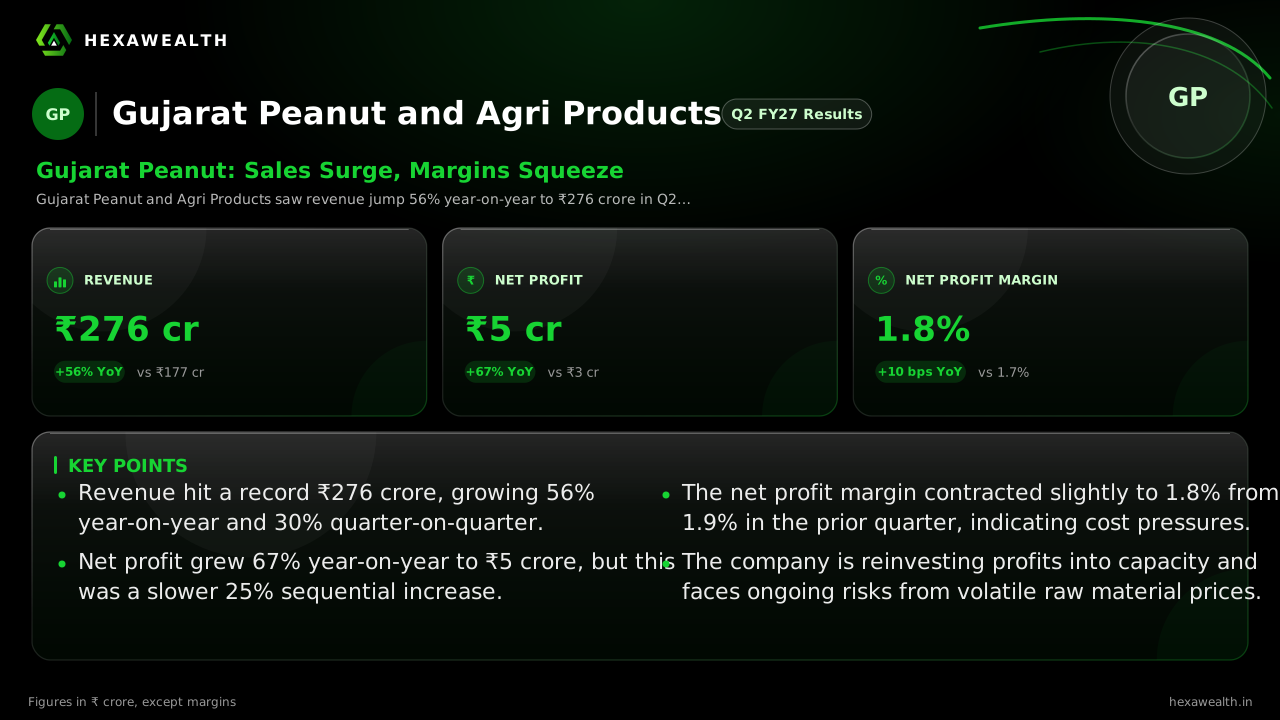
Gujarat Peanut and Agri Products saw revenue jump 56% year-on-year to ₹276 crore in Q2 FY27. However, profit growth of 67% lagged the top-line surge, and net margins contracted slightly from the previous quarter.
For an agricultural processor, a quarter of explosive sales growth is a clear win. The catch comes when costs rise just as fast, leaving profitability struggling to keep up. Gujarat Peanut and Agri Products delivered that exact story in the September quarter, posting record revenue while its margins tightened.
The numbers show a business scaling rapidly. Revenue soared 56% from a year ago to ₹276 crore, also jumping 30% from the March quarter. Net profit grew a healthy 67% year-on-year to ₹5 crore, but that was a slower 25% rise sequentially.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 276.0 | 212.0 |
| Profit (₹ Cr) | 5.0 | 4.0 |
| Net Profit Margin (%) | 1.8 | 1.9 |
Why profit growth trailed sales
The sequential margin squeeze, a 10-basis-point dip, points to costs keeping pace with sales. Total expenses rose 57% year-on-year, mirroring the revenue jump. A key factor, according to StockFin.ai, is raw material price volatility from fluctuating peanut procurement costs.
Market data supports this. A Commodity Board Europe report from late October noted groundnut prices in Gujarat were firming as oil mills stepped up procurement. While the company's other income tripled year-on-year to ₹3 crore, it wasn't enough to fully offset the operating cost pressure.
The outlook hinges on crop and cost
The company's near-term performance is tied to two opposing forces. On one hand, India's 2026 peanut crop is projected to be 25% lower, which could tighten supply and support prices. On the other, current export prices have shown only modest strength, suggesting cautious demand.
Management, as noted in its annual report by StockFin.ai, is in a reinvestment phase, retaining earnings to fund expansion in processing, R&D, and sustainability. This growth focus comes with the persistent risk of input cost swings in a competitive trading segment.
Key Points
- Revenue hit a record ₹276 crore, growing 56% year-on-year and 30% quarter-on-quarter.
- Net profit grew 67% year-on-year to ₹5 crore, but this was a slower 25% sequential increase.
- The net profit margin contracted slightly to 1.8% from 1.9% in the prior quarter, indicating cost pressures.
- The company is reinvesting profits into capacity and faces ongoing risks from volatile raw material prices.
Hexa Perspective
This quarter underscores the classic commodity processor's dilemma: volume growth is achievable, but translating it into consistent margin expansion is harder. The revenue surge is impressive, but the flat profit before tax quarter-on-quarter reveals that costs are rising in lockstep.
The path forward depends on whether the company's reinvestment into processing can create a durable cost advantage or value-added products. For now, with a P/E of 12.5 trading at a 78% discount to its industry, the market is pricing in the volatility, not the growth.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.