Gujarat Industries Power (GIPCL) Q2 FY27 Profit Plunges 75% as Expansion Costs Bite
The utility's revenue grew over a third year-on-year, but a sharp drop in other income and surging finance costs led to a severe sequential profit contraction.
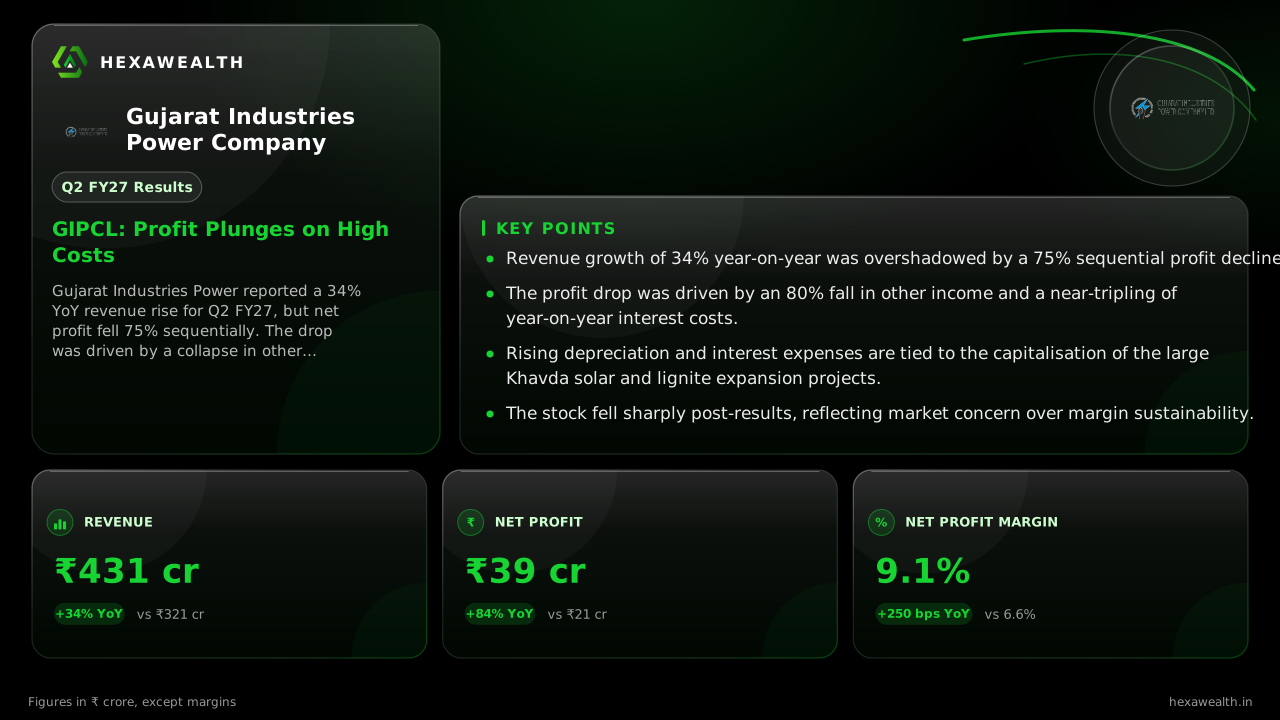
Gujarat Industries Power reported a 34% YoY revenue rise for Q2 FY27, but net profit fell 75% sequentially. The drop was driven by a collapse in other income and sharply higher interest and depreciation costs from ongoing capacity expansion.
For Gujarat Industries Power, this quarter was a story of two diverging trends. While a growing power portfolio lifted revenue, the financial burden of building it dragged profitability sharply lower.
The numbers show the split. Revenue rose 34.2% year-on-year to ₹431.2 crore, but fell 13.6% from the seasonally strong June quarter. Net profit dropped 75.1% sequentially to ₹39.2 crore, despite an 84.2% gain over a low year-ago base. The net profit margin compressed to 9.1% from 31.6% last quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 431.16 | 499.28 |
| Net Profit (₹ Cr) | 39.24 | 157.90 |
| Net Profit Margin (%) | 9.1 | 31.6 |
Why the profit fell off a cliff
Two factors explain most of the sequential profit collapse. First, other income plummeted 80% to ₹22.5 crore from an unusually high ₹112 crore in Q1, as noted by Stockwatch. That prior-quarter boost did not repeat.
Second, the cost of funding and operating new capacity is rising fast. Interest expense nearly tripled year-on-year to ₹51.2 crore, while depreciation rose 44% to ₹92.5 crore. Stockwatch links this directly to capitalisation of the massive Khavda solar park and lignite expansion.
The expansion engine is still running
Despite the profit squeeze, the company is executing a significant growth plan. Management, in a July analyst meet cited by Stockwatch, targets ₹600 crore in solar EBITDA for FY27, up from ₹332 crore in FY26. A 500 MW solar project at Khavda is slated for commissioning post-monsoon.
The balance sheet shows the funding. Work-in-progress capitalisation jumped, and non-current borrowings rose to ₹3,758 crore at the end of September from ₹3,248 crore at the end of March. This debt-funded expansion is the primary driver behind the surging finance costs.
Market reads the squeeze as structural
Investors reacted negatively to the margin pressure. MarketsMojo reported the stock fell 6.9% on the results day, closing at ₹162.10. The outlet assigned a 'Sell' rating, flagging concerns over earnings quality and the sustainability of profits given the high reliance on non-operating income in the past.
The valuation gap is stark, with the stock trading at a P/E of 4.2 against an industry average of 25.5. This deep discount reflects investor skepticism about near-term earnings stability amid heavy capital expenditure.
Key Points
- Revenue growth of 34% year-on-year was overshadowed by a 75% sequential profit decline.
- The profit drop was driven by an 80% fall in other income and a near-tripling of year-on-year interest costs.
- Rising depreciation and interest expenses are tied to the capitalisation of the large Khavda solar and lignite expansion projects.
- The stock fell sharply post-results, reflecting market concern over margin sustainability.
Hexa Perspective
This quarter highlights the transition phase GIPCL is in. The core power generation business is growing, but the financials are being reshaped by the cost of building its future capacity. The surge in interest and depreciation is not a one-off; it is the new run-rate as borrowed capital gets deployed.
The path ahead hinges on the timely commissioning of new solar capacity to start generating the EBITDA needed to cover these elevated fixed costs. Until those new cash flows materialise, quarterly profits will remain under pressure, and the stock's deep valuation discount is likely to persist.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.