DK Enterprises Global (DKEGL) Q2 FY27 Profit Lags Revenue Surge as Interest Costs Triple
A 58% sequential sales jump delivered record revenue, but a tripling of interest expense kept profit growth in check and margins below last year's level.
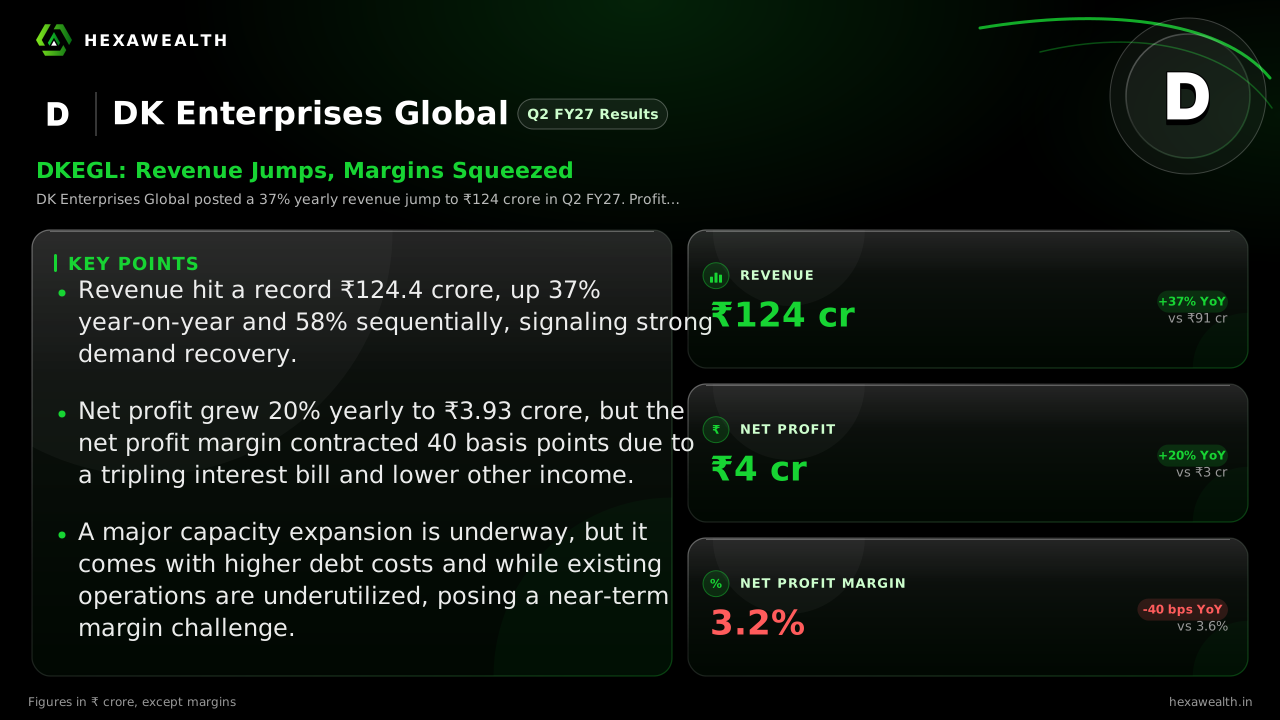
DK Enterprises Global posted a 37% yearly revenue jump to ₹124 crore in Q2 FY27. Profit grew 20%, but a tripling interest bill and lower other income squeezed the net margin down 40 basis points from a year ago.
For a packaging supplier, the quarter is a test of whether sales growth can outrun the cost of funding it. DK Enterprises Global's September quarter delivered a record ₹124.4 crore in revenue, a 58% surge from the prior quarter. Yet the bottom line tells a story of costs keeping pace.
The numbers show a business accelerating. Revenue jumped 37% from a year ago, while profit rose 20% to ₹3.93 crore. Sequentially, profit grew 61%, slightly outpacing sales. The margin picture is more nuanced. The net profit margin inched up 10 basis points from last quarter to 3.2%, but remains 40 basis points below where it stood a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period Ended | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 124.37YoY +37% | 90.56 |
| Profit (₹ Cr) | 3.93YoY +20% | 3.27 |
| Net Profit Margin (%) | 3.2YoY -11% | 3.6 |
Why the profit didn't keep up
Two items explain the margin pressure. Interest expense nearly tripled year-on-year to ₹0.88 crore, according to the company's financials. This likely reflects higher debt to fund operations or expansion. At the same time, other income halved, removing a ₹0.43 crore cushion that supported last year's profit.
Costs rose in lockstep with sales. Total expenses grew 38% year-on-year, matching the revenue increase. Employee costs were up 26%, while depreciation rose 11%. The company is spending to grow, but the financial burden is rising faster.
The expansion paradox
This cost pressure arrives as the company embarks on a significant capacity expansion. A report from Flash Finance notes a ₹44.9 crore, two-phase capex plan to more than double capacity from ₹140 crore to ₹310 crore. The first phase in Baddi is set for operations by end-2026.
The paradox, as the same report highlights, is that management has disclosed existing operations run at only 50-60% utilization. Funding this expansion with debt, as seems likely, will add more interest and depreciation charges. The payoff depends on filling the new capacity in a market where price is often the deciding factor.
How long the squeeze lasts
The outlook hinges on demand and debt. The India industrial tapes market is projected to grow at a 12.8% CAGR through 2033, according to Markntel Advisors, driven by automotive and electronics manufacturing. This tailwind supports DKEGL's top line.
Yet the margin squeeze has at least a few more quarters to run. The new interest costs are now baked in. The company must achieve higher utilization on its existing and new lines to generate operating leverage. Until then, profit growth will likely continue to trail revenue.
Key Points
- Revenue hit a record ₹124.4 crore, up 37% year-on-year and 58% sequentially, signaling strong demand recovery.
- Net profit grew 20% yearly to ₹3.93 crore, but the net profit margin contracted 40 basis points due to a tripling interest bill and lower other income.
- A major capacity expansion is underway, but it comes with higher debt costs and while existing operations are underutilized, posing a near-term margin challenge.
Hexa Perspective
The quarter confirms DK Enterprises Global can capture demand in a growing packaging market. The 58% sequential revenue jump is unambiguous. The concern is financial: the business model appears capital-intensive, with rising debt costs directly eroding profitability.
Investors are weighing a strong growth trajectory against thin and pressured margins. The stock trades at a P/E of 9.2, a 58% discount to the industry average, reflecting these risks. The next few quarters will show if sales momentum can finally deliver operating leverage, or if the cost of growth continues to bite.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.