Party Cruisers (PARTYCRUS) Q2 FY27 Growth Slows Sharply After Record Quarter
The event manager's revenue fell 43% sequentially from a record March quarter, with profit dropping 58% as the wedding season peak faded.
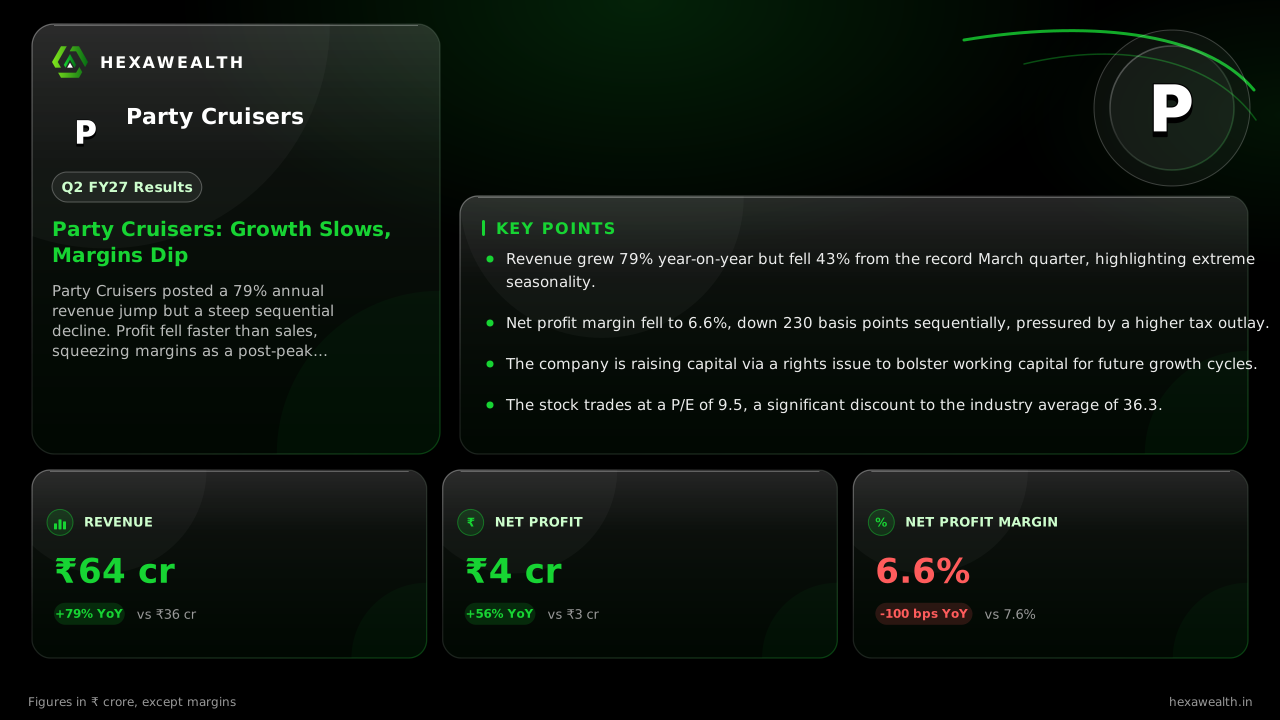
Party Cruisers posted a 79% annual revenue jump but a steep sequential decline. Profit fell faster than sales, squeezing margins as a post-peak season slowdown took hold.
For an event manager, the quarter after the peak wedding season is always a test of endurance. Party Cruisers passed that test with annual growth but stumbled hard from its record March high, revealing the sharp seasonal swing in its business.
The numbers show a company caught between a strong year-on-year comparison and a steep seasonal drop. Revenue of ₹63.8 crore was up 79% from a soft September 2025 quarter. Yet it fell 43% from the ₹111.3 crore record set in March. Profit followed the same path, rising 55% year-on-year to ₹4.2 crore but plunging 58% quarter-on-quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 63.79YoY +79% | 35.56 |
| Profit (₹ Cr) | 4.23YoY +56% | 2.72 |
| Net Profit Margin | 6.6%YoY -13% | 7.6% |
The costs that kept rising
Profit fell faster than revenue because margins compressed. The net profit margin dropped 230 basis points from the prior quarter to 6.6%. A 220% year-on-year jump in tax expense, as reported by Alfafinder, was a key pressure point. Operating leverage reversed as the business scaled down from its seasonal peak.
A rights issue for the next season
Management is preparing for future cycles with a capital raise. The company has a ₹30 crore fund raise approved and recently concluded a rights issue, according to Alfafinder announcements. The proceeds are earmarked for working capital to support growth, indicating investment for the next upswing rather than a reaction to the current slowdown.
Key Points
- Revenue grew 79% year-on-year but fell 43% from the record March quarter, highlighting extreme seasonality.
- Net profit margin fell to 6.6%, down 230 basis points sequentially, pressured by a higher tax outlay.
- The company is raising capital via a rights issue to bolster working capital for future growth cycles.
- The stock trades at a P/E of 9.5, a significant discount to the industry average of 36.3.
Hexa Perspective
The quarter confirms Party Cruisers operates on a boom-and-trough calendar. The stellar March quarter set an exceptionally high bar, making the September slowdown appear more severe. The margin squeeze from higher taxes is a near-term headwind, but the debt-free balance sheet and rights issue provide a cushion.
Investors are weighing robust annual growth against punishing volatility. The deep valuation discount reflects the market's pricing of this operational risk. The coming quarters will show if the company can smooth the peaks and troughs or if this sharp seasonal pattern is the enduring rhythm of the business.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.