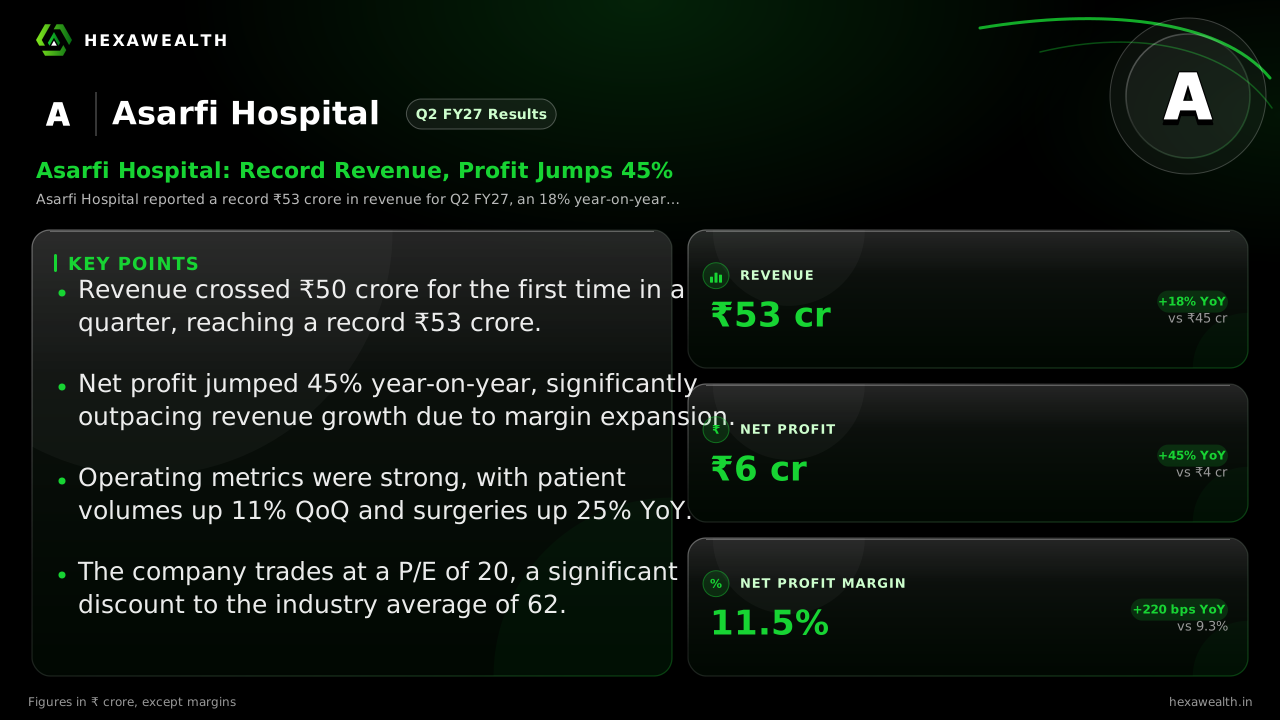
Asarfi Hospital (ASARFI) Q2 FY27 Profit Surges 45% as Operations Scale and Margins Expand
The Dhanbad-based hospital chain posted its highest-ever quarterly revenue, with profit growth far outpacing sales, signaling strong operational leverage.
Asarfi Hospital reported a record ₹53 crore in revenue for Q2 FY27, an 18% year-on-year rise. Net profit jumped 45% to ₹6.1 crore, as the company's focus on high-margin services and cost management drove significant margin expansion.
For regional hospital chains, growth is measured in patient volumes and the ability to command better prices for complex care. Asarfi Hospital’s second quarter shows it is winning on both fronts, delivering a record ₹53 crore in revenue and a 45% surge in profit.
The numbers tell a story of accelerating momentum. Revenue grew 18% from a year ago and 12% from the previous quarter. Profit leapt 45% year-on-year and 43% sequentially, pushing the net profit margin to 11.5%, a 250 basis point improvement from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 53.04YoY +18% | 47.53 | 44.89 |
| Profit (₹ Cr) | 6.09YoY +45% | 4.27 | 4.20 |
| Net Profit Margin (%) | 11.5YoY +24% | 9.0 | 9.3 |
Operational Leverage Kicks In
The profit surge was driven by core operations, not a lower tax rate. According to an Alfafinder report, profit before tax grew 46% year-on-year to ₹8.2 crore. This was powered by a record 22.4% EBITDA margin, as cited in the company’s investor presentation.
Patient volume rose 11% quarter-on-quarter, while surgeries jumped 25% year-on-year to 2,295. The company also saw a 17% rise in average revenue per occupied bed. This volume growth, combined with a focus on higher-margin specialties, created powerful operating leverage.
A Clear Runway for Growth
Management’s confidence is backed by a stark demand-supply gap. A CBRE report highlighted that states like Jharkhand have low hospital bed density relative to disease burden, indicating significant unmet demand. Asarfi is moving to capture this, planning to expand its cancer hospital from 65 to 150 beds by the end of FY27.
The company is also pursuing a migration from the BSE SME to the Main Board, subject to approvals. Its credit profile strengthened, with CRISIL upgrading its bank facility rating and total assets reaching ₹212 crore at the half-year mark.
Key Points
- Revenue crossed ₹50 crore for the first time in a quarter, reaching a record ₹53 crore.
- Net profit jumped 45% year-on-year, significantly outpacing revenue growth due to margin expansion.
- Operating metrics were strong, with patient volumes up 11% QoQ and surgeries up 25% YoY.
- The company trades at a P/E of 20, a significant discount to the industry average of 62.
Hexa Perspective
This quarter demonstrates Asarfi Hospital’s ability to translate regional demand into financial performance. The profit jump is meaningful because it stems from operational scale, not one-off gains.
The path ahead hinges on executing its capacity expansion without margin dilution. If it can maintain this discipline while growing its bed count, the current valuation gap with the broader hospital sector may narrow. Investors are weighing this execution capability against the company’s concentrated geographic footprint.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.