Ashram (ASHRAM) Q1 FY27 Online's Revenue Gain Is Erased by Surging Costs
The company's 30% year-on-year sales growth was overshadowed by a 44.5% jump in total expenses, leading to a wider quarterly loss.
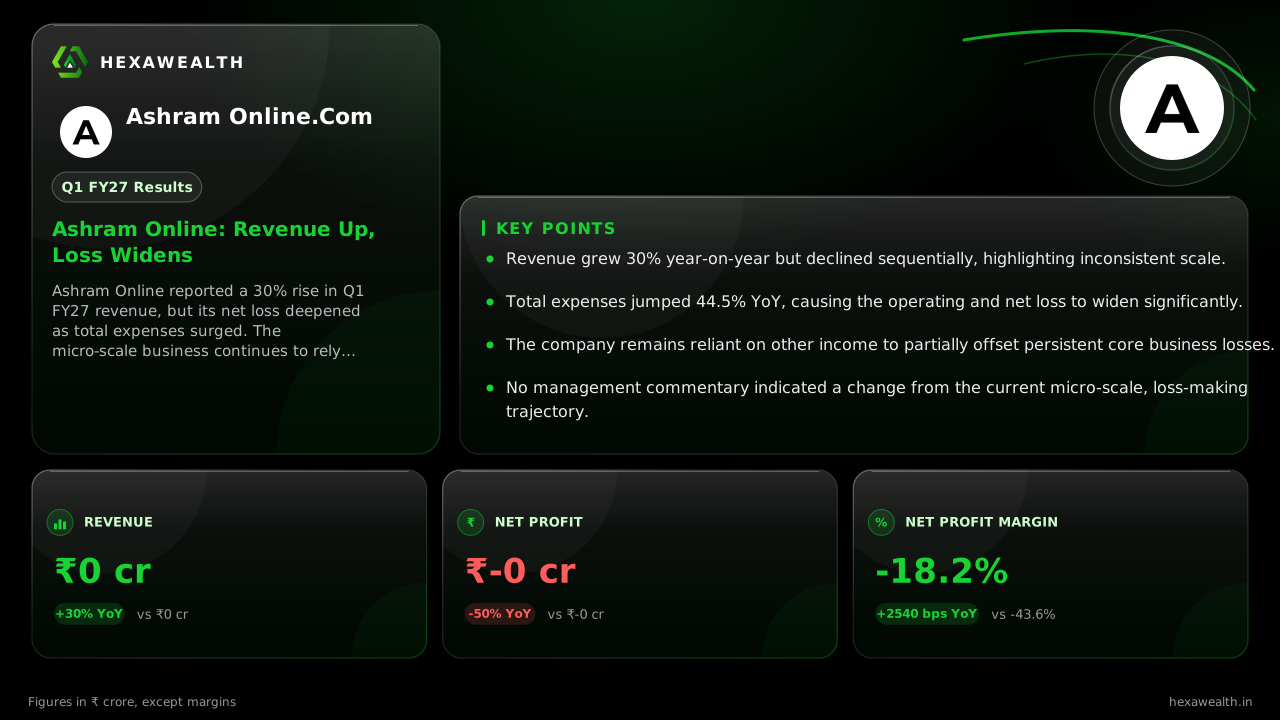
Ashram Online reported a 30% rise in Q1 FY27 revenue, but its net loss deepened as total expenses surged. The micro-scale business continues to rely on other income to offset persistent operating losses.
For Ashram Online, a micro-cap firm in infrastructure and trading, the story remains one of a top line struggling to cover a much larger cost base. The June quarter delivered a familiar tension: revenue growth was positive, but the loss from operations widened.
The numbers show a business still searching for scale. Revenue rose 30% year-on-year to ₹0.13 crore, but fell 7% from the previous quarter. The net loss deepened to ₹0.02 crore, a 50% larger deficit compared to last year. The net profit margin, while improved from a deeply negative base, worsened sequentially by over 10 percentage points.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ1 FY27 (Jun 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 0.13 | 0.14 |
| Profit (₹ Cr) | -0.02 | -0.01 |
| Net Profit Margin (%) | -18.2 | -7.9 |
Why the loss deepened
A 44.5% year-on-year surge in total expenses to ₹0.32 crore erased the revenue gain. According to Flash Finance, costs included purchase of stock-in-trade and rising finance charges. This pushed the operating loss wider, a trend noted by mCapital.in, which estimates the company's operating margin remains deeply negative.
The reported net loss was somewhat cushioned by other income, which more than doubled year-on-year to ₹0.17 crore. Flash Finance reported this includes interest income, but the core trading and infrastructure operations continued to bleed.
A static business trajectory
Management provided no new guidance with these results. Analysis from mCapital.in suggests the business trajectory is unchanged, with quarterly sales stuck around ₹0.12-0.13 crore and persistent losses. The firm's spiritual products trading business, as noted by Flash Finance, continues to operate at a sub-scale level with no announced plans for material expansion.
Market reaction was muted, reflecting the lack of a fundamental shift. The stock had declined 7.8% in the year leading up to the results date. With negligible institutional ownership and no analyst coverage, the quarter passed without the scrutiny that drives larger price moves.
Key Points
- Revenue grew 30% year-on-year but declined sequentially, highlighting inconsistent scale.
- Total expenses jumped 44.5% YoY, causing the operating and net loss to widen significantly.
- The company remains reliant on other income to partially offset persistent core business losses.
- No management commentary indicated a change from the current micro-scale, loss-making trajectory.
Hexa Perspective
The quarter confirms Ashram Online is trapped in a cycle of sub-scale revenue and high relative costs. The 2540 basis point year-on-year margin improvement is a function of an exceptionally weak base, not operational strength. For the loss to narrow sustainably, revenue must not just grow but accelerate meaningfully beyond the ₹0.15 crore quarterly run-rate. The current cost structure, including interest expense on rising borrowings, makes that hurdle steep. Investors are left weighing a negligible equity value against a business model that has yet to prove it can reach profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.