CHL (CHLLTD) Q2 FY27's Profit Crashes 83% as a Foreign Exchange Windfall Vanishes
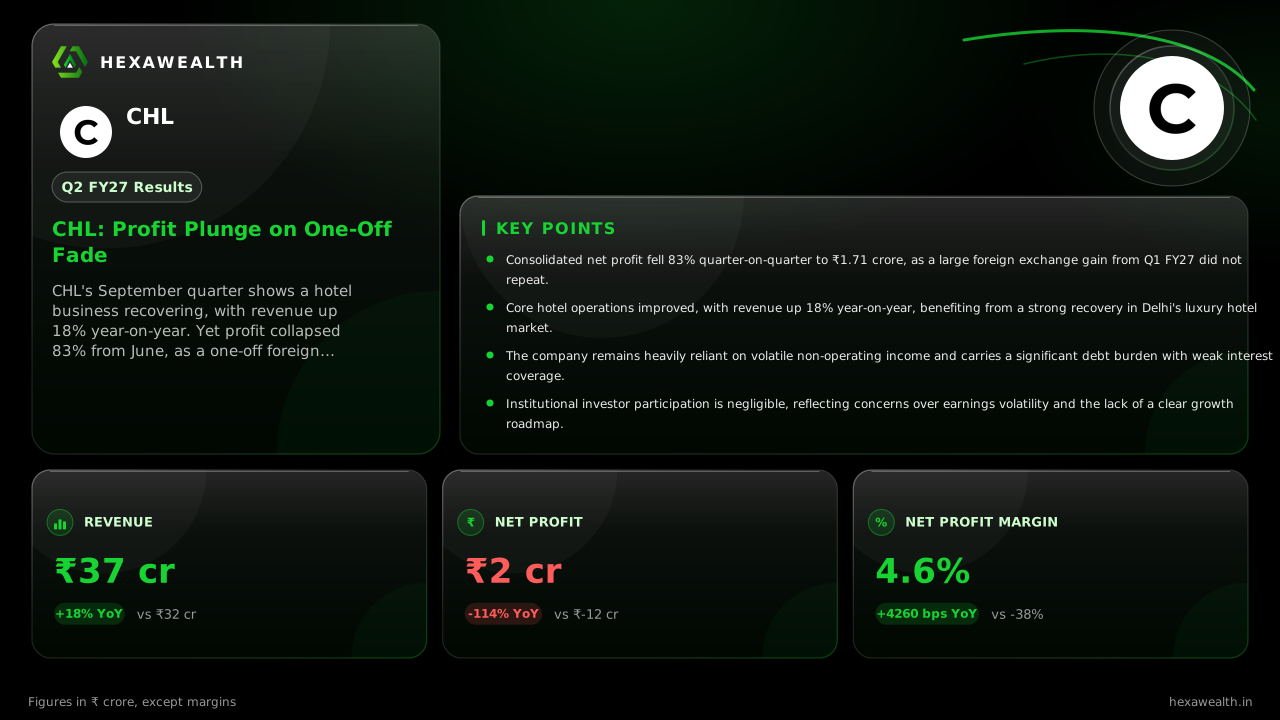
CHL's Q2 FY27 revenue grew 18% year-on-year, but profit plunged 83% sequentially as a large foreign exchange gain from the prior quarter did not repeat.
CHL's September quarter shows a hotel business recovering, with revenue up 18% year-on-year. Yet profit collapsed 83% from June, as a one-off foreign exchange gain faded, exposing a heavy reliance on non-operating income.
For a single-hotel operator like CHL, a steady recovery in room demand is the core story. The September quarter delivered that, with revenue rising 18% from a weak year-ago period. Yet the bottom line tells a different tale, as profit crashed 83% from the previous quarter, revealing how fleeting one-off gains can be.
The numbers show a business pulled in two directions. Consolidated revenue reached ₹37.3 crore, a solid 7.3% sequential increase. But net profit collapsed to ₹1.71 crore from ₹10.14 crore in June. The net profit margin shrank to 4.6% from 29.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 37.30 | 34.76 |
| Profit (₹ Cr) | 1.71 | 10.14 |
| Net Profit Margin | 4.6% | 29.2% |
Why the profit vanished
This dramatic swing is almost entirely due to a precipitous drop in other income, which fell 66% to ₹5.09 crore. MarketsMojo reports that other income constituted 171% of profit before tax this quarter, highlighting a dangerous dependency. The prior quarter's profit was inflated by a ₹11.4 crore foreign exchange translation gain from its Tajikistan subsidiary, a non-cash, non-repeatable item.
The underlying hotel is improving
Strip away the forex noise, and the flagship Hotel The Suryaa in Delhi shows signs of life. Standalone revenue rose 18% year-on-year, according to ScanX, reflecting a stronger market. Delhi's hotel market saw RevPAR grow 37% in September, reports Jefferies, driven by events like BRICS. This suggests CHL's core operations are riding a sector recovery.
A debt burden that won't fade
However, a structural challenge remains. The company carries a heavy debt load of over ₹262 crore. MarketsMojo notes its interest coverage ratio averages just 0.28 times, meaning operating profit barely covers interest costs. This limits financial flexibility and makes consistent profitability from operations crucial.
The market reaction was muted, with the stock largely ignored by institutions. Promoters hold a stable 73%, but FIIs and mutual funds have zero stake, as per MarketsMojo data. This lack of institutional interest underscores skepticism about earnings quality and sustainability.
Key Points
- Consolidated net profit fell 83% quarter-on-quarter to ₹1.71 crore, as a large foreign exchange gain from Q1 FY27 did not repeat.
- Core hotel operations improved, with revenue up 18% year-on-year, benefiting from a strong recovery in Delhi's luxury hotel market.
- The company remains heavily reliant on volatile non-operating income and carries a significant debt burden with weak interest coverage.
- Institutional investor participation is negligible, reflecting concerns over earnings volatility and the lack of a clear growth roadmap.
Hexa Perspective
This quarter lays bare the tension between CHL's improving hotel business and its fragile financial structure. The operating recovery is real but is being overshadowed by extreme profit volatility driven by forex moves at a distant subsidiary. For the story to turn convincing, the company needs to demonstrate it can consistently service its debt from hotel earnings alone. Until then, the stock will likely remain a play on sporadic forex gains rather than a sustainable hospitality turnaround.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.