Shankara Buildpro (BUILDPRO) Q2 FY27 Profit Jumps 56.5% on Record Steel Sales
Shankara Buildpro's Q2 FY27 revenue surged 42.9%, driven by a 27% volume jump in steel, though thin retail margins limited profit expansion.
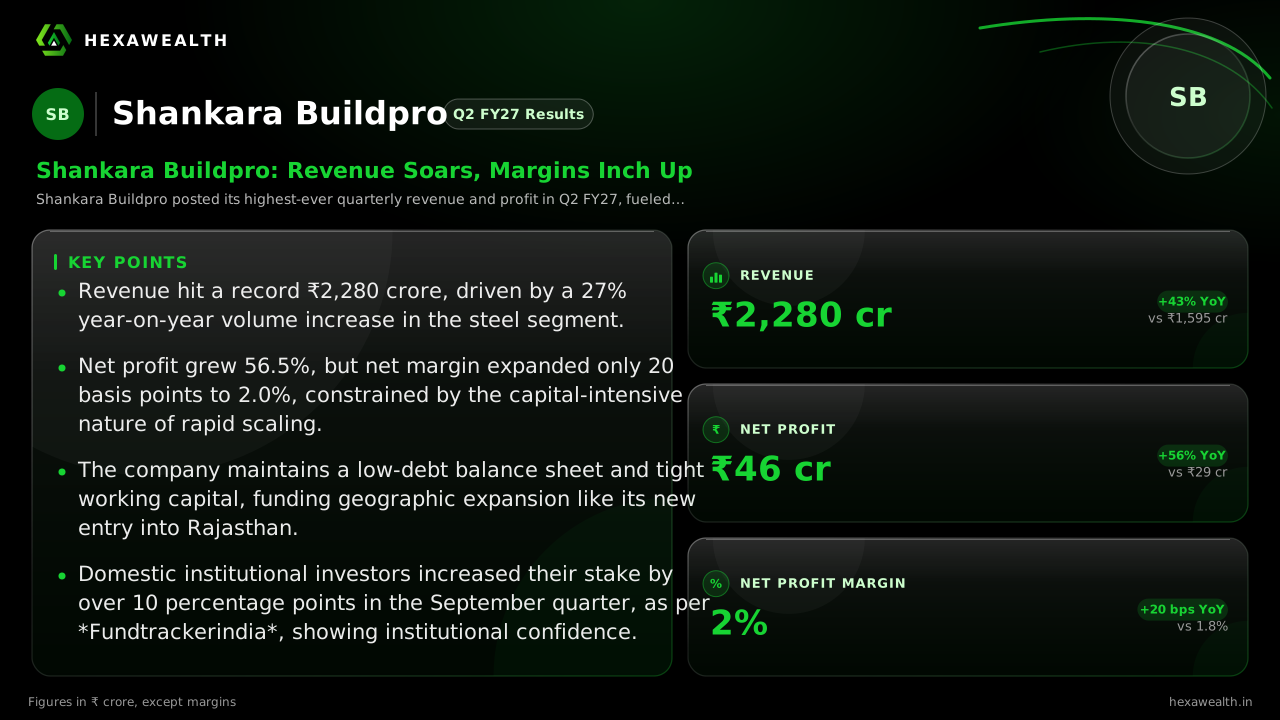
Shankara Buildpro posted its highest-ever quarterly revenue and profit in Q2 FY27, fueled by strong steel demand. Profit grew 56.5% year-on-year, but net margin improvement was modest at 20 basis points.
For a retailer of building materials, growth hinges on moving more tonnes through its stores. Shankara Buildpro did exactly that in the September quarter, posting its highest-ever sales on the back of a booming steel market. The result was a 42.9% revenue surge and a 56.5% jump in profit, though the notoriously thin margins of the trade kept bottom-line expansion in check.
The numbers show broad-based momentum. Revenue reached ₹2,280 crore, while net profit climbed to ₹46 crore. Sequentially, both grew over 20%, indicating the first quarter's strength was no fluke. The net profit margin, however, remains wafer-thin, inching up just 20 basis points year-on-year to 2.0%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,280.0YoY +43% | 1,889.8 | 1,595.0 |
| Profit (₹ Cr) | 46.0YoY +56% | 35.8 | 29.4 |
| Net Profit Margin (%) | 2.0YoY +11% | 1.9 | 1.8 |
Steel Volumes Carry the Quarter
The engine of growth was unmistakably steel. According to the company's investor presentation, steel sales jumped 46% year-on-year to ₹2,100 crore. Volumes rose 27% to 3.03 lakh tonnes, as reported by Multibagg.ai. This outpaced national finished steel consumption growth of 8% for September, noted in a PIB release, suggesting market share gains. Non-steel categories like sanitaryware grew a slower 17%.
Why Margins Stayed Skinny
Profit growth vastly outpaced revenue, a sign of operating leverage. Yet the net margin gain was minimal. Rising costs to support this scale played a role. Interest expense grew nearly 25% year-on-year to ₹12 crore, which MarketsMojo attributed to higher working capital needs. Depreciation also rose sharply. The retail building materials sector operates on razor-thin margins, making even this modest 20-basis-point improvement a hard-won gain.
The Funding for Future Growth
To sustain this pace, the company is expanding its footprint. It entered Rajasthan with a new fulfillment center in the quarter. Earlier guidance, noted in a Q1 FY27 presentation, pointed to adding 7-10 new centers this fiscal year. This expansion is funded by a strong, asset-light balance sheet with near-zero debt, as highlighted by MarketsMojo. Working capital was held at 22 days.
Key Points
- Revenue hit a record ₹2,280 crore, driven by a 27% year-on-year volume increase in the steel segment.
- Net profit grew 56.5%, but net margin expanded only 20 basis points to 2.0%, constrained by the capital-intensive nature of rapid scaling.
- The company maintains a low-debt balance sheet and tight working capital, funding geographic expansion like its new entry into Rajasthan.
- Domestic institutional investors increased their stake by over 10 percentage points in the September quarter, as per Fundtrackerindia, showing institutional confidence.
Hexa Perspective
The quarter confirms Shankara Buildpro's ability to capture robust construction demand, particularly in steel. The path ahead, however, is defined by a persistent tension. Growth is clear and funded, but profitability is hemmed in by the fundamental economics of distribution. The company must continue to win market share and manage working capital deftly to translate top-line surges into more meaningful margin improvement. For now, it is a story of volume-led scale.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.