Brawn Biotech (BRAWN) Q2 FY27 Profit Plunges 57% as Costs Outpace Revenue Growth
The pharmaceutical distributor's Q2 FY27 revenue grew 15% year-on-year, but a sharp rise in employee and operational expenses erased nearly all profitability.
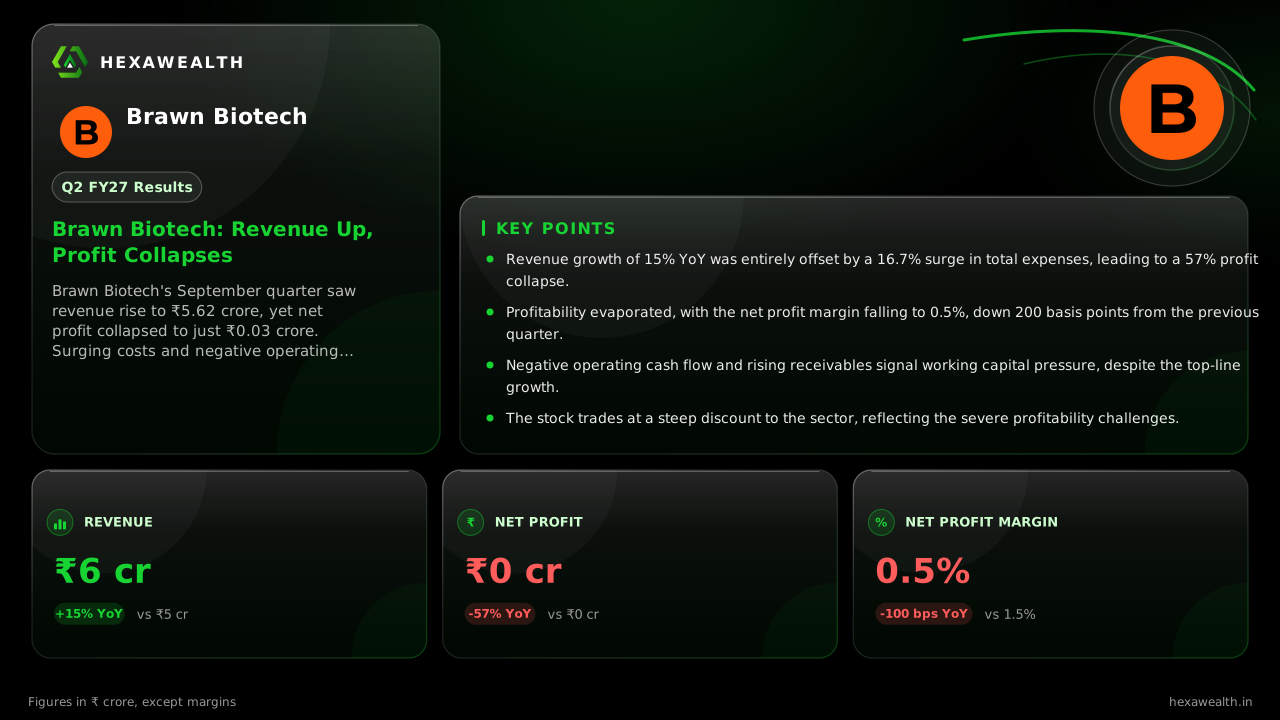
Brawn Biotech's September quarter saw revenue rise to ₹5.62 crore, yet net profit collapsed to just ₹0.03 crore. Surging costs and negative operating cash flow highlight significant margin pressure and working capital strain for the company.
For a pharmaceutical distributor, growth is meant to bring operating leverage. Brawn Biotech's September quarter delivered the opposite, with a 15% revenue rise completely undone by a faster cost surge that pushed profitability to the edge.
The numbers tell a story of divergence. Revenue reached ₹5.62 crore, up from ₹4.89 crore a year ago. Yet net profit shrank to a mere ₹0.03 crore, an 80% drop from the previous quarter. The net profit margin collapsed to 0.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 5.62 | 6.08 |
| Profit (₹ Cr) | 0.03 | 0.15 |
| Net Profit Margin | 0.5% | 2.5% |
Where the money went
Total expenses jumped 16.7% year-on-year, outpacing sales. According to a scanx.trade report, employee costs rose over 50% and other operational expenses increased significantly. This squeezed margins in a quarter where, as Flash Finance noted, all pre-tax profit came from other income.
The strain is not just on the income statement. The company reported negative operating cash flow for the first half, per the same scanx.trade analysis. Cash reserves dwindled while trade receivables ballooned, indicating capital is getting tied up in working capital.
A sector tailwind, a company headwind
This comes against a robust industry backdrop. The Indian pharmaceutical market grew 12% in the September quarter, led by chronic therapies, according to an Elets eHealth report citing PharmaTrac data. Brawn Biotech captured some of that demand but could not convert it into earnings.
The valuation reflects deep skepticism. At a P/E of 7.7, the stock trades at an 85% discount to the industry average. The share price was down nearly 5% in the week following the results announcement.
Key Points
- Revenue growth of 15% YoY was entirely offset by a 16.7% surge in total expenses, leading to a 57% profit collapse.
- Profitability evaporated, with the net profit margin falling to 0.5%, down 200 basis points from the previous quarter.
- Negative operating cash flow and rising receivables signal working capital pressure, despite the top-line growth.
- The stock trades at a steep discount to the sector, reflecting the severe profitability challenges.
Hexa Perspective
The quarter reveals a fundamental disconnect. Brawn Biotech is riding a sector tailwind but lacks the cost control or pricing power to benefit from it. The cash flow statement is the clearest warning: profit is a book entry not supported by cash generation.
For this to change, the company must demonstrate it can manage its cost base and convert sales into cash. Until then, the deep valuation discount is less a bargain and more a accurate reflection of the operational challenges at hand.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.