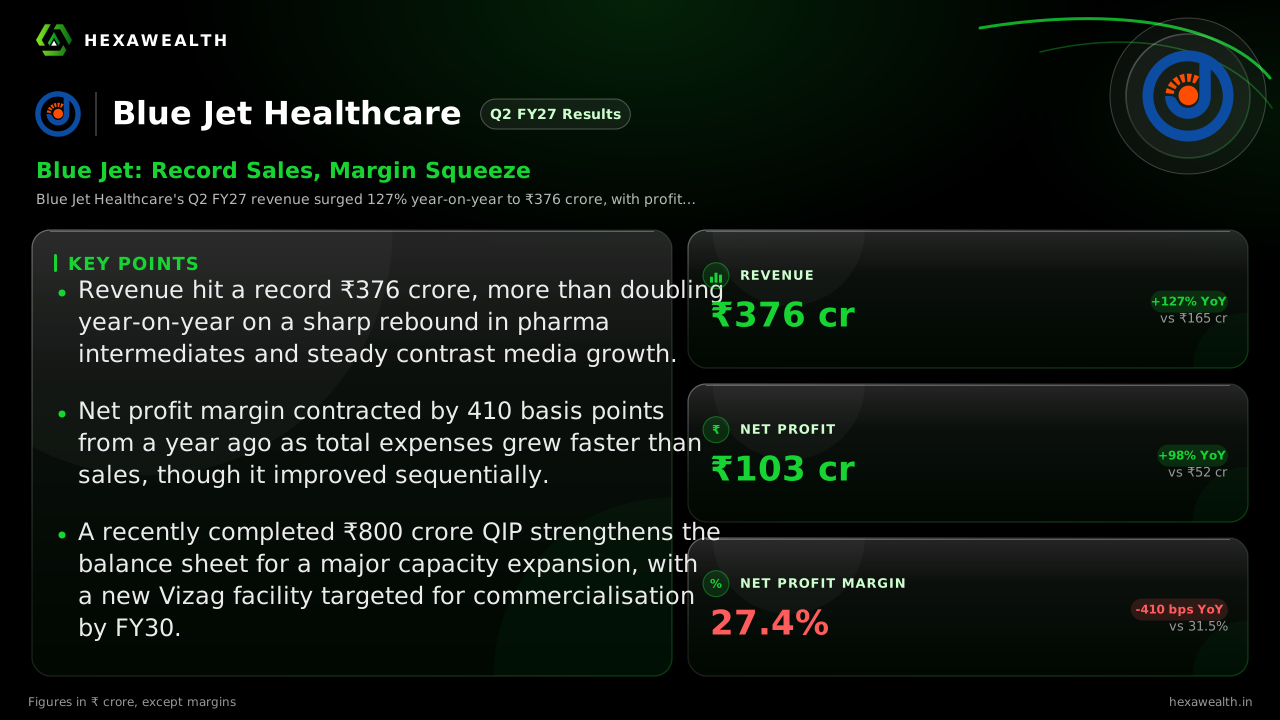
Blue Jet Healthcare (BLUEJET) Q2 FY27 Profit Doubles on Record Sales, But Margins Narrow
The pharmaceutical intermediates maker posted its highest-ever quarterly revenue, yet profitability softened as costs rose faster than sales.
Blue Jet Healthcare's Q2 FY27 revenue surged 127% year-on-year to ₹376 crore, with profit nearly doubling. However, net profit margin contracted by 410 basis points, highlighting underlying cost pressures.
For Blue Jet Healthcare, the September quarter was about a powerful recovery finally arriving. After a year of destocking in its pharma intermediates segment, the company posted its highest-ever quarterly revenue, driven by a sharp rebound in orders and strong contrast media demand.
Revenue for Q2 FY27 stood at ₹376 crore, more than double the ₹165 crore from a year ago. Net profit followed, nearly doubling to ₹103 crore. The sequential story is equally strong, with revenue and profit up 28% and 32% from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 376.0YoY +127% | 293.1 | 165.5 |
| Profit (₹ Cr) | 103.0YoY +98% | 78.3 | 52.1 |
| Net Profit Margin (%) | 27.4YoY -13% | 26.7 | 31.5 |
Yet, the headline growth masks a squeeze. The net profit margin fell 410 basis points year-on-year, even as it improved slightly from the prior quarter. This margin compression, noted by Stockwatch, was partly due to a high base effect from an unusually large inventory cost offset in Q2 FY26.
Why the profit didn't keep pace
The massive revenue jump was led by a 322% surge in pharma intermediates and API sales, as customer destocking ended, and a 80% rise in contrast media intermediates. However, total expenses grew even faster, up 119% year-on-year. Material costs, the largest expense, more than doubled.
Management, cited by insights.dsij.in, expects three new contrast media launches in FY27, with commercial batches due soon. The Hyderabad R&D centre is now operational, targeting peptides and GLP-1 intermediates for future growth.
Funding a long-term build-out
A key development was the completion of an ₹800 crore Qualified Institutional Placement (QIP) during the quarter. This significantly bolstered the cash balance, which helped slash interest costs by 78% year-on-year and boosted other income.
The funds are earmarked for a multi-year expansion. Management has guided for ₹250 crore of capital expenditure in FY27, part of a larger ₹1,000 crore plan for a new Vizag facility, according to a concall summary by Sovrenn. This long-dated investment underpins the growth thesis but defers near-term returns.
Key Points
- Revenue hit a record ₹376 crore, more than doubling year-on-year on a sharp rebound in pharma intermediates and steady contrast media growth.
- Net profit margin contracted by 410 basis points from a year ago as total expenses grew faster than sales, though it improved sequentially.
- A recently completed ₹800 crore QIP strengthens the balance sheet for a major capacity expansion, with a new Vizag facility targeted for commercialisation by FY30.
Hexa Perspective
The quarter confirms the operational recovery is underway, with the volatile pharma intermediates segment bouncing back strongly. The core contrast media business, with its regulatory moat, provides a stable foundation.
Investors are now weighing robust near-term growth against a margin profile that remains below peak levels. The large, freshly funded capex cycle commits the company to a multi-year build-out, making consistent execution the critical factor for the story to hold.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.