Bharat Forge (BHARATFORG) Q2 FY27 Profit Dips 7% Despite 21% Revenue Jump on Cost Squeeze
The forging giant's Q2 FY27 revenue surged on strong domestic demand, but profit fell as raw material and restructuring costs outpaced sales growth.
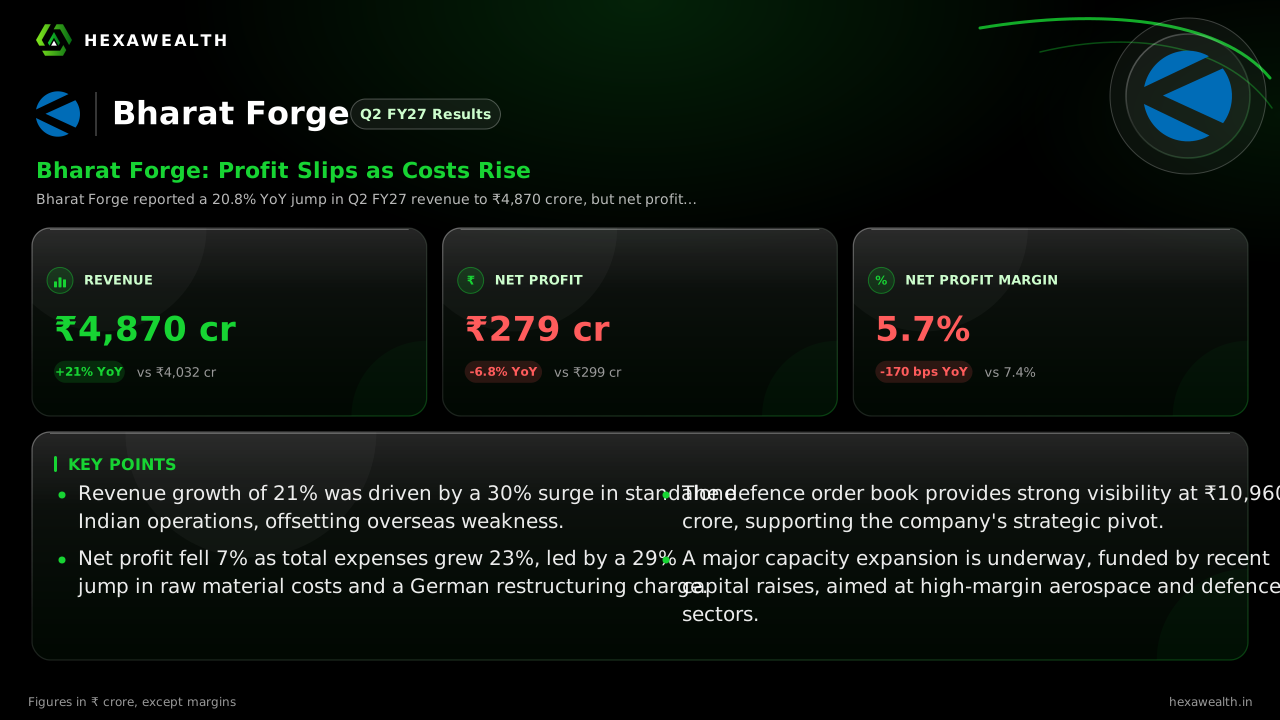
Bharat Forge reported a 20.8% YoY jump in Q2 FY27 revenue to ₹4,870 crore, but net profit fell 6.8%. The squeeze came from raw material costs rising 29% and a ₹25 crore restructuring charge at its German unit.
Bharat Forge's September quarter shows a business accelerating into new sectors but still wrestling with old-world costs. Revenue jumped 21% year-on-year, yet profit slipped 7% as expenses grew even faster, a margin squeeze that overshadowed a strong top-line performance.
The numbers tell a story of divergence. Consolidated revenue reached ₹4,870 crore, a solid 5% sequential increase. Profit, however, was ₹279 crore, down from ₹299 crore a year ago. The net profit margin contracted 170 basis points to 5.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4,870.0YoY +21% | 4,639.9 | 4,031.9 |
| Profit (₹ Cr) | 279.0YoY -6.8% | -89.9 | 299.3 |
| Net Profit Margin (%) | 5.7YoY -23% | -1.9 | 7.4 |
Why Profit Couldn't Keep Pace
The profit decline was not from a lack of demand. According to Autocar Professional, raw material costs soared 29% and other expenses rose 27%. This was compounded by a ₹24.6 crore restructuring charge for its German subsidiary, Bharat Forge CDP GmbH. The standalone India business was a bright spot, with revenue up 30% and profit up 20%, reports Upstox.
Management, in the earnings call, pointed to a lag in passing on higher freight and energy costs to customers. They expect this recovery, along with new business ramp-ups, to boost the second half. The defence order book provides a long runway, standing at ₹10,960 crore as of September, per The Hindu Businessline.
The Investment Phase Ahead
Growth is coming, but it requires capital. The company is executing a ₹2,000+ crore capex program across aerospace, defence, and semiconductors, as noted by Chairman B.N. Kalyani. A new forging facility in Baramati will add 100,000 tons of capacity, much of it for high-value non-automotive work. This expansion is building capacity ahead of demand, which pressures near-term margins but sets up future growth.
The market reacted to the margin pressure, with shares falling 4% after the results, reports Faxioms. Brokerages cut target prices, reflecting scepticism that near-term earnings can justify a trailing P/E of 74, which trades at a 52% premium to the industry.
Key Points
- Revenue growth of 21% was driven by a 30% surge in standalone Indian operations, offsetting overseas weakness.
- Net profit fell 7% as total expenses grew 23%, led by a 29% jump in raw material costs and a German restructuring charge.
- The defence order book provides strong visibility at ₹10,960 crore, supporting the company's strategic pivot.
- A major capacity expansion is underway, funded by recent capital raises, aimed at high-margin aerospace and defence sectors.
Hexa Perspective
Bharat Forge is in a clear transition. The quarter underscores the tension between its high-growth, high-investment future and the cost-heavy legacy operations it must manage today. The 170-basis-point margin compression is the price of that shift.
The path forward hinges on execution. The defence order book must convert to revenue at promised margins, and new facilities must ramp up without further cost overruns. Until then, the stock's rich valuation leaves little room for disappointment, as the immediate market reaction showed.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.