Campus Activewear (CAMPUS) Q2 FY27 Profit Slips 8% Despite Strong Sales Growth
The footwear brand's revenue jumped 17% year-on-year, but a sharp rise in expenses squeezed quarterly profitability, with margins falling 150 basis points.
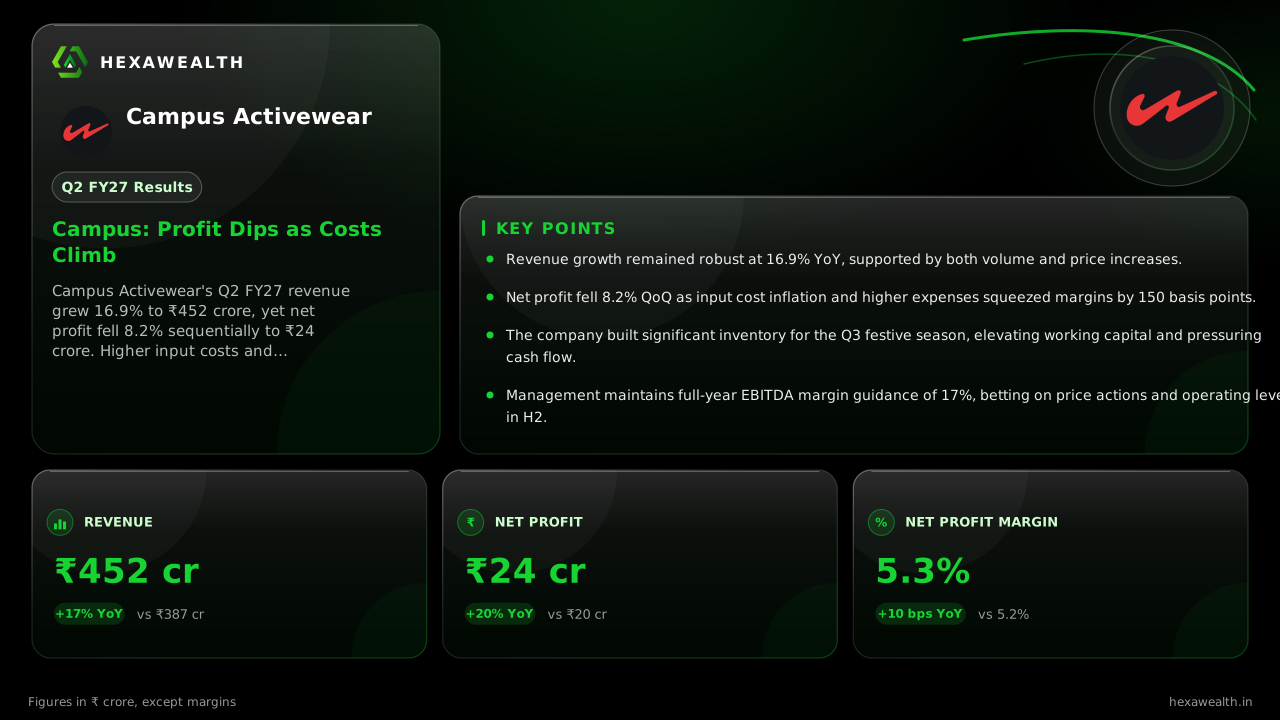
Campus Activewear's Q2 FY27 revenue grew 16.9% to ₹452 crore, yet net profit fell 8.2% sequentially to ₹24 crore. Higher input costs and inventory build-up for the festive season pressured margins, even as volume and average selling price rose.
For Campus Activewear, the September quarter was about building momentum before the festive rush, but the cost of that preparation landed squarely on the bottom line. Revenue grew a healthy 16.9% year-on-year, yet profit slipped 8.2% from the previous quarter as expenses climbed faster than sales.
The numbers show a business in a growth squeeze. Revenue reached ₹452 crore, driven by a 10.2% rise in volumes and a 6.1% increase in average selling price. However, total expenses surged 18.5% quarter-on-quarter, pulling the net profit margin down to 5.3% from 6.8% in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 452.0YoY +17% | 385.2 | 386.61 |
| Profit (₹ Cr) | 24.0YoY +20% | 26.14 | 20.07 |
| Net Profit Margin (%) | 5.3YoY +1.9% | 6.8 | 5.2 |
Why margins narrowed
The sequential profit decline stemmed from a sharp rise in costs. According to the earnings call transcript from AlphaStreet, management cited significant inflation in key input costs as a primary pressure. While the company took calibrated price increases, there is a lag before these fully offset higher material costs flowing through inventory.
Other expenses also rose. Best Media Info reported that advertising and promotion spend increased 19.1% sequentially to about ₹36 crore. This, combined with higher costs for materials and employee benefits reported by Indian Television Dot Com, led to the 150-basis-point margin contraction from the June quarter.
The inventory bet on Q3
A major factor behind the working capital strain was a strategic inventory build. Multibagg.ai reported the company lifted net working capital to 94 days to stock up for anticipated festive demand in Q3. This inventory-led build absorbed ₹164 crore in cash from operations during the half-year.
CEO Nikhil Aggarwal, quoted by ETRetail, noted the company delivered double-digit volume growth in both Q1 and Q2 despite the festive season shifting to Q3 this year. The quarter's record production volumes were aimed at meeting this expected demand spike.
The road to margin recovery
Management's guidance offers a path forward. In the earnings call, the company expressed confidence in delivering a full-year EBITDA margin of 17%, implying a meaningful recovery in the second half. This hinges on the benefits of earlier price hikes, a richer product mix, and operating leverage kicking in.
Brokerage Motilal Oswal, in a report cited by DSIJ, retained its Buy rating with a target of ₹290. It expects margin expansion from premiumisation, better mix, and the scaling of in-house capacity at the Pantnagar facility.
Key Points
- Revenue growth remained robust at 16.9% YoY, supported by both volume and price increases.
- Net profit fell 8.2% QoQ as input cost inflation and higher expenses squeezed margins by 150 basis points.
- The company built significant inventory for the Q3 festive season, elevating working capital and pressuring cash flow.
- Management maintains full-year EBITDA margin guidance of 17%, betting on price actions and operating leverage in H2.
Hexa Perspective
Campus Activewear's quarter illustrates the classic tension between top-line growth and near-term profitability. The 16.9% revenue jump confirms strong brand demand, but the margin squeeze reveals the lag in passing through input cost inflation.
The inventory build is a calculated bet on festive demand. Its success in Q3 will determine if working capital normalises and cash flow improves. For the margin guidance to hold, the benefits of premiumisation and recent price hikes must fully materialise before any new cost pressures emerge.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.