Berger Paints (BERGEPAINT) Q2 FY27 Profit Crashes 60% as Raw Material Inflation Squeezes Margins
The paintmaker's net profit fell sharply despite steady revenue, as delayed price hikes and high-cost inventory eroded profitability in a competitive quarter.
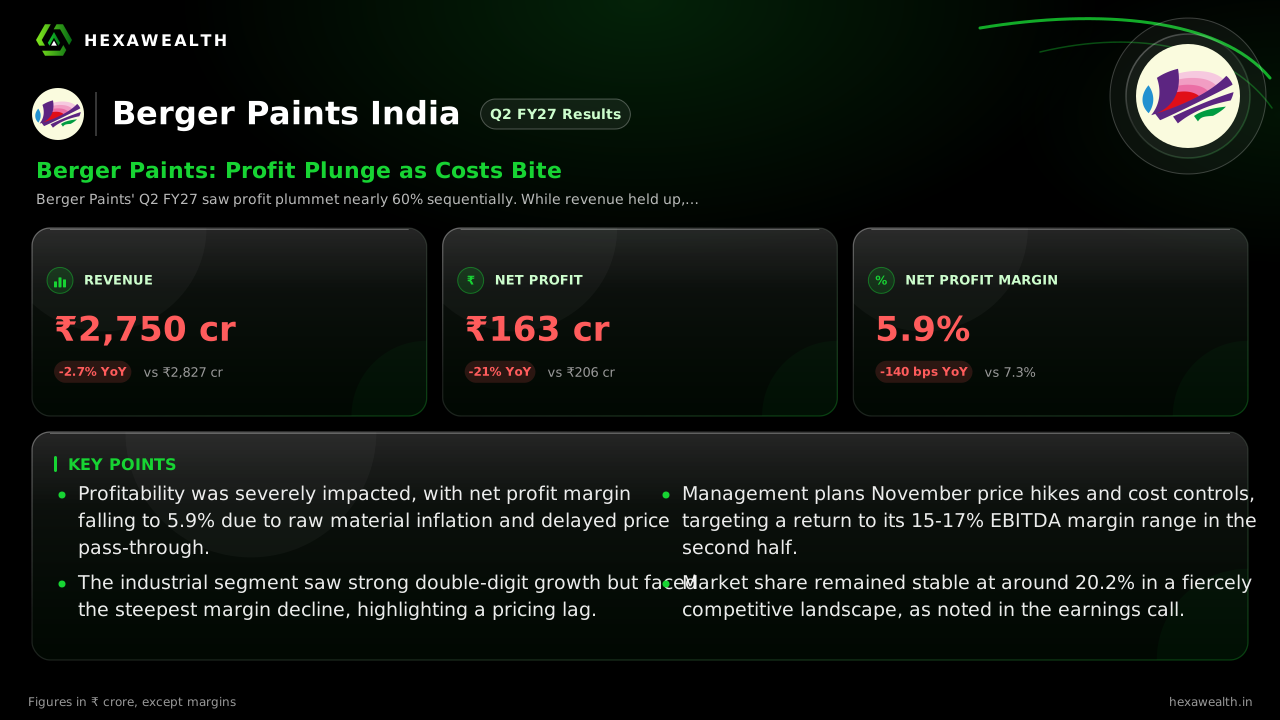
Berger Paints' Q2 FY27 saw profit plummet nearly 60% sequentially. While revenue held up, severe margin pressure from raw material costs and delayed price pass-through defined a challenging quarter for India's second-largest paint company.
For Berger Paints, the September quarter was a story of costs arriving faster than prices. The company navigated steady demand but saw its profitability erode as it worked through high-cost inventory while trying to pass on increases to customers.
The numbers show a sharp divergence. Standalone revenue was ₹2,750 crore, down 2.7% from a year ago. Profit, however, fell much harder, dropping 20.9% year-on-year to ₹163 crore. The sequential drop was steeper, with profit down 59.7% from a strong June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
Metric
CurrentQ2 FY27
PreviousQ1 FY27
Same quarter LYQ2 FY26
Revenue (₹ Cr)
2,750.1YoY -2.7%
3,583.8
2,827.5
Profit (₹ Cr)
163.3YoY -21%
405.0
206.4
Net Profit Margin
5.9%YoY -19%
11.3%
7.3%
The net profit margin collapsed by 540 basis points from the prior quarter to 5.9%. This was well below the company's trailing twelve-month average of 9.6%.
Why Margins Collapsed
The pressure came from a perfect storm of input costs. Management, cited in an Indian Television Dot Com report, blamed double-digit raw material inflation, liquidation of high-cost inventory, and delayed price increases in the industrial business. The impact intensified during the quarter.
Material costs as a share of operating income rose to 63.4% from 60.4% a year ago. An additional ₹22 crore spent on the new 'Rang Bana Rahe' brand campaign also weighed on quarterly margins. The company noted that excluding this campaign spend, operating profit growth would have been around 3%.
A Split Performance
Business segments told two different stories. The decorative paints unit saw 10% value growth, driven by price increases, according to the earnings call transcript. However, volume growth moderated as a later Diwali shifted festive demand into Q3.
In contrast, the industrial business delivered robust high double-digit volume and value growth. Yet, margins here were under the most pressure. The company told analysts it was unable to pass on cost hikes in a timely manner, with industrial gross margins falling about 5-5.5%.
The Path to Recovery
Management has a clear, if challenging, plan to restore profitability. The company will implement further calibrated price increases in November and beyond. It expects to recover almost 90% of the required industrial price hikes by end-November.
CEO Abhijit Roy, quoted by The Financial Express, said there is "no sign of easing of the inflationary trend of raw materials." The company is banking on these price actions, cost-saving initiatives, and potentially softer crude-linked input costs to lift margins.
Confidence is high for the coming quarters. Management told analysts it expects to get close to its guided 15-17% EBITDA margin band in Q3 and possibly Q4. October already recorded the company's highest sales growth in about 25-30 months, setting a positive tone for festive demand.
Key Points
Profitability was severely impacted, with net profit margin falling to 5.9% due to raw material inflation and delayed price pass-through.
The industrial segment saw strong double-digit growth but faced the steepest margin decline, highlighting a pricing lag.
Management plans November price hikes and cost controls, targeting a return to its 15-17% EBITDA margin range in the second half.
Market share remained stable at around 20.2% in a fiercely competitive landscape, as noted in the earnings call.
“
Hexa Perspective
The quarter underscores the vulnerability of paint margins to crude-linked input costs when pricing power is delayed. Berger's challenge is execution: successfully passing on November's price increases without losing volume in a market where new entrants are competing aggressively on rebates.
The guidance for a sharp H2 margin recovery is ambitious but credible if price hikes stick and crude softens. Investors are weighing this promised rebound against the demonstrated squeeze, with the stock's 12.9% one-year decline reflecting that caution. The next quarter will show if costs are finally under control.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Berger Paints' Q2 FY27 results?
For Q2 FY27 (quarter ended September 2026), Berger Paints reported standalone revenue of ₹2,750.1 crore, down 2.7% year-on-year. Net profit was ₹163.3 crore, a decline of 20.9% from the same quarter last year. The net profit margin compressed to 5.9%.
Why did Berger Paints' Q2 profit drop nearly 60% quarter-on-quarter?
Berger Paints' Q2 FY27 profit fell 59.7% sequentially primarily due to a severe margin squeeze. The company faced double-digit raw material inflation, had to liquidate high-cost inventory, and could not pass on price increases in its industrial business quickly enough, as reported by Indian Television Dot Com.
What caused the margin collapse in Berger Paints' Q2 FY27?
Berger Paints' net profit margin fell 540 basis points QoQ to 5.9%. The collapse was driven by a sharp rise in material costs, which consumed 63.4% of operating income. Delayed price hikes in the industrial segment and an additional ₹22 crore brand campaign spend also pressured margins.
How did Berger Paints' decorative and industrial segments perform in Q2 FY27?
The decorative business saw 10% value growth driven by price increases, though volumes moderated. The industrial segment delivered robust high double-digit volume and value growth, but its margins fell about 5-5.5% due to delayed price pass-through, as per the company's earnings call.
What is Berger Paints' management outlook for the rest of FY27?
Management expects a stronger second half, targeting a return to its 15-17% EBITDA margin band in Q3 and Q4. The plan involves implementing further price increases in November, achieving 90% recovery on industrial hikes by month-end, and continuing cost-saving initiatives.
Is Berger Paints losing market share to new competitors?
No, Berger Paints' market share remained broadly stable. Management estimated its share among listed peers at about 20.2% at the end of H1 FY27, compared to 20.3% earlier. The competitive environment is described as intense but stable.
How did Berger Paints' stock react to the Q2 FY27 results?
Berger Paints' stock closed at ₹505 on November 5, 2026, reacting positively to the results announcement. Reports from BusinessToday and CNBC TV18 noted the stock rose 2-4% on the day, as investors looked past the weak margin print toward the company's recovery plans.
Did Berger Paints' Q2 FY27 results beat analyst estimates?
The results likely missed some analyst expectations on margins. A preview report from Stockwatch noted the Street was watching for an EBITDA margin of 18-19%. The actual standalone EBITDA margin came in at 10.8%, indicating significant pressure versus those hopes.
What are Berger Paints' expansion and capex plans?
Berger Paints plans to use internal funds for new factories in Panagar, West Bengal, and Odisha. It has completed expansion at its Hindupur plant. Management intends to maintain a net-cash balance sheet while funding this capacity growth, as noted in a Multibagg.ai analysis.
Are institutional investors buying or selling Berger Paints stock?
Foreign institutional investors (FIIs) modestly increased their stake to 4.96% in Q2 FY27 from 4.83% in Q1. Domestic institutional (DII) holdings were relatively stable. This suggests cautious optimism from global investors despite the margin pressures.
Berger Paints Q2 profit drop
Berger Paints' Q2 FY27 standalone net profit dropped 20.9% year-on-year to ₹163.3 crore. The sharper 59.7% sequential decline was due to severe margin pressure from raw material inflation and delayed price increases in its industrial business.
Berger Paints Q2 FY27 results November 2026
Berger Paints announced its Q2 FY27 results on November 5, 2026. For the September 2026 quarter, standalone revenue was ₹2,750.1 crore and net profit was ₹163.3 crore. The company flagged margin pressure but outlined price hikes for recovery.
Why did Berger Paints profits plunge despite higher sales?
Berger Paints' profits plunged despite value growth because costs rose faster. Double-digit raw material inflation and the liquidation of high-cost inventory severely squeezed gross margins. The company also cited a ₹22 crore brand campaign spend that affected quarterly profitability.
Berger Paints margin guidance Q3 FY27
Berger Paints' management expects to get close to its guided 15-17% EBITDA margin band in Q3 FY27. This recovery is predicated on the full impact of November price increases, cost-saving initiatives, and potentially softer crude-linked input costs.
Berger Paints industrial business Q2 FY27
Berger Paints' industrial business delivered robust high double-digit volume and value growth in Q2 FY27. However, margins were under significant pressure as price hikes could not be fully passed on to customers in a timely manner, according to the company's earnings call.