BEML Profit Falls 31% Despite a 42% Revenue Jump in Q2 FY27
The defence and engineering PSU's quarterly revenue hit a multi-quarter high, but cost pressures and a higher tax outgo squeezed its bottom line.
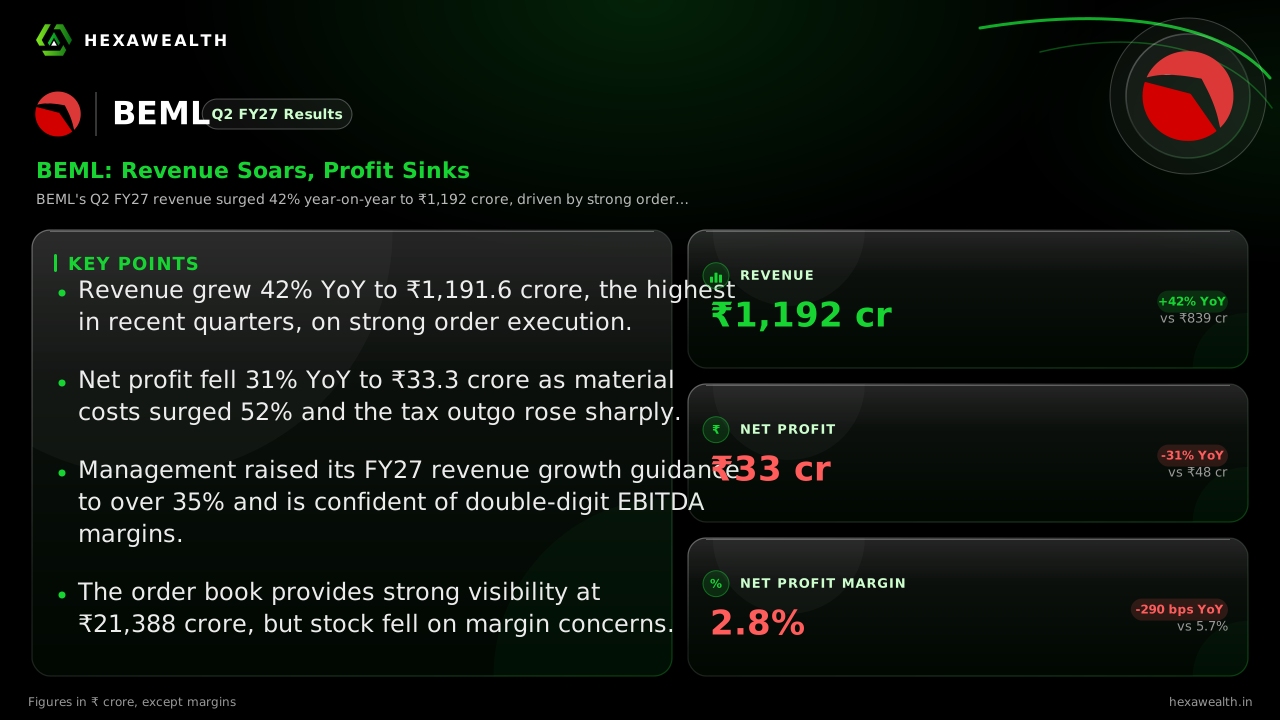
BEML's Q2 FY27 revenue surged 42% year-on-year to ₹1,192 crore, driven by strong order execution. However, net profit fell 31% to ₹33 crore as material costs and taxes rose sharply, compressing margins.
For BEML, a strong order book is translating into top-line momentum, but the path to the bottom line is proving costly. The September quarter saw the company swing back to a small profit after a loss, yet the year-on-year comparison reveals a persistent squeeze where revenue growth is not feeding through to earnings.
Revenue for the quarter ended September 2026 rose 42% year-on-year to ₹1,191.6 crore, a multi-quarter high. Sequentially, it jumped 45% from the June quarter. Net profit, however, fell 31% from a year ago to ₹33.3 crore, though it marked a sharp recovery from the previous quarter's loss. The net profit margin contracted to 2.8% from 5.7% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,191.6YoY +42% | 819.6 | 839.1 |
| Profit (₹ Cr) | 33.3YoY -31% | -27.0 | 48.0 |
| Net Profit Margin (%) | 2.8YoY -51% | -3.3 | 5.7 |
The Cost Squeeze That Ate the Growth
Material costs, which rose 52% year-on-year to ₹724 crore, outpaced revenue growth. According to The Hindu BusinessLine, this was compounded by higher employee and other operational expenses. Interest costs also jumped 50% to ₹14.9 crore. The effective tax rate normalized to 30% from an unusually low 4.5% in the year-ago quarter, further pressuring the bottom line.
Management, as reported by CNBC-TV18, has raised its full-year revenue growth outlook to over 35% from 30% previously. It remains confident of achieving a double-digit EBITDA margin for the year, expecting better execution and a favourable product mix in the second half. The order book stood at a robust ₹21,388 crore at the end of September, providing clear revenue visibility.
Market Reaction and the Road Ahead
The stock fell over 4% on results day, as CNBC-TV18 noted the print largely missed analyst estimates. While revenue beat expectations, profit and EBITDA fell short. Brokerage Antique Stock Broking retained a 'Buy' rating, but the market is clearly weighing the margin disappointment against the growth promise.
The coming quarters hinge on BEML's ability to manage input costs and improve execution efficiency. With a debt-free balance sheet and a massive order backlog, the company has the foundation. The challenge is turning that backlog into profits that match the top-line excitement.
Key Points
- Revenue grew 42% YoY to ₹1,191.6 crore, the highest in recent quarters, on strong order execution.
- Net profit fell 31% YoY to ₹33.3 crore as material costs surged 52% and the tax outgo rose sharply.
- Management raised its FY27 revenue growth guidance to over 35% and is confident of double-digit EBITDA margins.
- The order book provides strong visibility at ₹21,388 crore, but stock fell on margin concerns.
Hexa Perspective
BEML's quarter illustrates the classic tension between order-book-driven growth and project-execution profitability. The revenue jump confirms demand strength across defence, rail, and mining, but the margin compression suggests pricing power or cost control is not keeping pace. The company's guidance implies a significant margin recovery is baked into the second half, a key assumption for investors. With the stock trading at a premium to the industry, the narrative must shift from 'revenue growth' to 'profit delivery' for sustained outperformance.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.