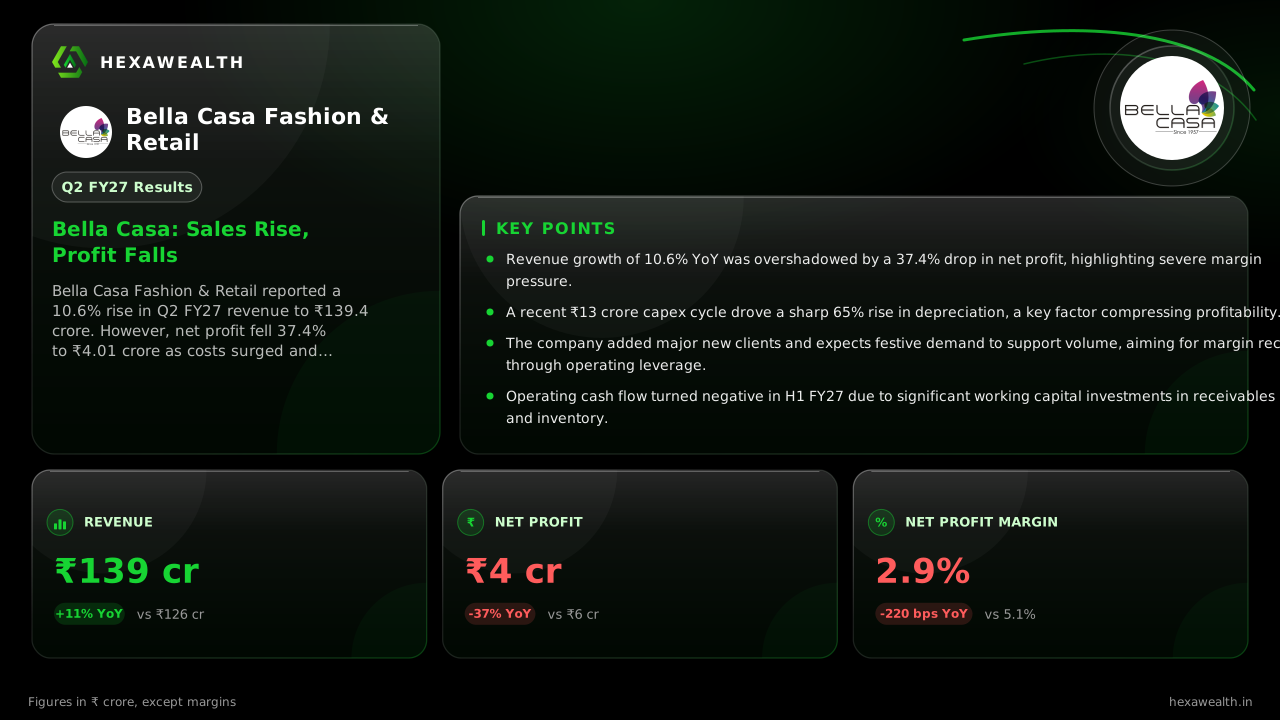
Bella Casa Fashion & Retail reported a 10.6% rise in Q2 FY27 revenue to ₹139.4 crore. However, net profit fell 37.4% to ₹4.01 crore as costs surged and margins compressed.
For Bella Casa Fashion & Retail, the September quarter was a story of two diverging lines. Revenue climbed on the back of new client wins and a seasonal uptick, but profit fell sharply as the costs of a recent expansion cycle and competitive pressures weighed heavily on margins.
The numbers show the tension clearly. Revenue grew 10.6% year-on-year to ₹139.4 crore, but net profit dropped 37.4% to ₹4.01 crore. Sequentially, the picture improved from a weak Q1, with profit up 58% on a 16% rise in sales.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
Metric
CurrentQ2 FY27 (Sep 2026)
PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
139.4
119.94
Net Profit (₹ Cr)
4.01
2.54
Net Profit Margin
2.9%
2.1%
Why the profit squeeze deepened
Total expenses grew faster than sales, rising 14% year-on-year. A key driver was a 65% surge in depreciation, which FlashFinance linked to the completion of a ₹13 crore half-yearly capital expenditure cycle. This spending focused on debottlenecking and vertical integration across its seven plants.
Higher employee and interest costs also contributed, squeezing the operating profit line. The company’s net profit margin contracted by 220 basis points to just 2.9%.
A sequential recovery with a festive tailwind
The strong quarter-on-quarter bounce was partly seasonal. According to a FlashFinance analysis, the company onboarded a UAE-based fast-fashion retailer and a leading home furnishing brand, supporting volume. The late Diwali also pushed some festive demand into October, which may benefit the third quarter.
Management is betting on this volume-led operating leverage to improve margins now that the immediate capex cycle is over. The half-yearly EBITDA margin stood at 5.4%, as reported by the same outlet.
The cash flow challenge
Growth came at a cost to the balance sheet. For the first half of FY27, operating cash flow turned negative at ₹13.47 crore, down from a positive ₹41.08 crore a year earlier. FlashFinance attributed this to rising receivables and inventory as the company funded its expansion.
This working capital absorption highlights the strain of scaling up, even as the company maintains a manageable debt-to-equity ratio of 0.49.
Key Points
Revenue growth of 10.6% YoY was overshadowed by a 37.4% drop in net profit, highlighting severe margin pressure.
A recent ₹13 crore capex cycle drove a sharp 65% rise in depreciation, a key factor compressing profitability.
The company added major new clients and expects festive demand to support volume, aiming for margin recovery through operating leverage.
Operating cash flow turned negative in H1 FY27 due to significant working capital investments in receivables and inventory.
“
Hexa Perspective
The quarter underscores a transition phase. Bella Casa is paying for capacity it has just built, with depreciation and interest costs hitting the income statement before the new volumes can fully offset them. The path forward hinges on two things: sustaining the sales momentum from new client relationships and successfully passing on input costs in a competitive market.
The stock’s 44% decline over the past year already prices in much of this profitability shock. Investors are now watching for the promised operating leverage to materialize in the coming quarters, turning top-line growth into bottom-line strength.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Bella Casa Fashion & Retail's Q2 FY27 results?
Bella Casa Fashion & Retail reported Q2 FY27 revenue of ₹139.4 crore, a 10.6% increase year-on-year. Net profit for the quarter was ₹4.01 crore, which represents a 37.4% decline compared to the same period last year.
Why did Bella Casa's Q2 FY27 profit fall despite higher sales?
Bella Casa's profit fell 37.4% YoY in Q2 FY27 because total expenses grew faster than revenue, rising 14%. A significant 65% jump in depreciation expense, linked to recent capital expenditure, and higher employee and interest costs severely compressed margins.
What caused the 220 bps drop in Bella Casa's net profit margin in Q2 FY27?
Bella Casa's net profit margin fell 220 basis points to 2.9% in Q2 FY27 due to a sharp rise in costs. Depreciation surged 65% YoY following a ₹13 crore H1 capex cycle, while employee and interest expenses also increased, outpacing the 10.6% revenue growth.
Was Bella Casa's 57.9% QoQ profit growth in Q2 FY27 driven by seasonal demand?
Bella Casa's 57.9% quarterly profit growth was supported by seasonal factors and operational improvements. According to FlashFinance, new client wins and festive demand spillover into October helped drive a 16% QoQ revenue increase, while the completion of an immediate capex cycle set the stage for better efficiency.
What are Bella Casa Fashion & Retail's expansion plans and capex?
Bella Casa recently completed a ₹13 crore capital expenditure cycle in H1 FY27, focusing on debottlenecking and vertical integration. As per a Financial Express report, the company has doubled annual capacity to 20 million pieces and has plans for long-term capex of ₹30 crore, funded partly by a past rights issue.
What guidance did Bella Casa management provide for FY27?
Specific FY27 guidance was not detailed in the results. However, analysis from FlashFinance suggests management is focusing on volume-led operating leverage post-capex, with festive demand in Q3 expected to support growth. The challenge is to sustain margins above 6% as new capacity is utilized.
Did Bella Casa's Q2 FY27 results beat analyst estimates?
No verified analyst consensus estimates were publicly available for Bella Casa's Q2 FY27 results, as noted in a Univest preview. The results were therefore judged against the year-ago base of ₹126.03 crore in revenue and ₹6.41 crore in profit.
How did Bella Casa's stock price react to the Q2 FY27 results?
Bella Casa's stock price was largely neutral around the Q2 FY27 results announcement. Data from EdgeTest shows the share has fallen on the day of the last five quarterly results, reflecting a market that has been pricing in profitability challenges over time.
What is Bella Casa Fashion & Retail's debt-to-equity ratio?
As of the latest data, Bella Casa Fashion & Retail maintains a debt-to-equity ratio of 0.49, which is considered a manageable level of financial leverage. The company's interest coverage ratio stands at 4.5 times.
Are FIIs or DIIs increasing their stake in Bella Casa?
Institutional ownership in Bella Casa remains minimal. As of September 2026, FIIs held 0.05% and DIIs held 0.00% of the company, according to shareholding pattern data. Promoters hold a steady 58.34% stake.
Bella Casa Fashion & Retail Q2 Results FY27
Bella Casa Fashion & Retail's Q2 FY27 results, announced in November 2026, showed revenue of ₹139.40 crore and a net profit of ₹4.01 crore. This represented a 10.6% year-on-year revenue increase but a 37.4% decline in profit compared to Q2 FY26.
Bella Casa Q2 FY27 revenue
Bella Casa Fashion & Retail's revenue for Q2 FY27 (the September 2026 quarter) was ₹139.4 crore. This marks a 10.6% increase from the ₹126.03 crore reported in the same quarter the previous year.
Bella Casa Q2 FY27 PAT
Bella Casa Fashion & Retail's Profit After Tax (PAT) for Q2 FY27 was ₹4.01 crore. This is a decline of 37.4% from the ₹6.41 crore PAT the company reported in Q2 FY26.