Balrampur Chini (BALRAMCHIN) Q2 FY27 Profit Jumps 89% as Sugar Prices Offset Ethanol Shift
The sugar major posted a net profit of ₹102 crore for the September quarter, driven by a 14.5% rise in average sugar realizations and a sharp drop in interest costs.
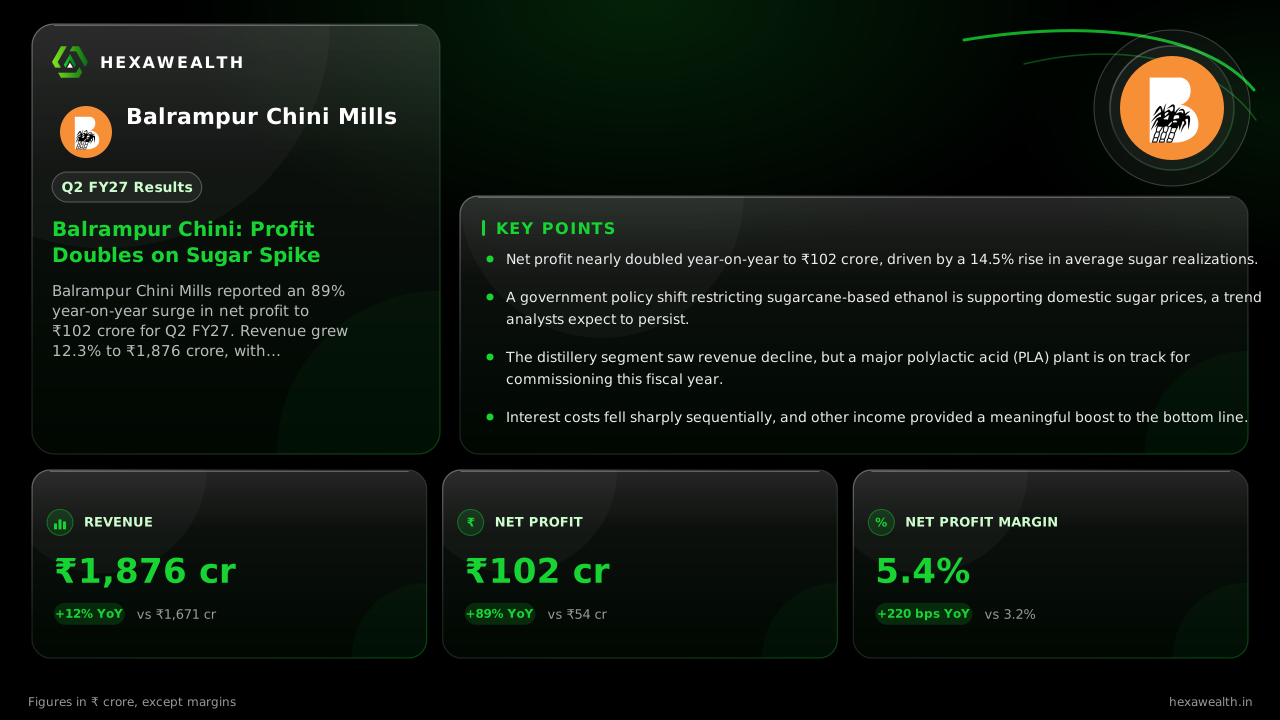
Balrampur Chini Mills reported an 89% year-on-year surge in net profit to ₹102 crore for Q2 FY27. Revenue grew 12.3% to ₹1,876 crore, with profitability boosted by higher sugar prices and lower interest expenses.
For India's sugar companies, the quarter was defined by a pivot. The government's move to restrict sugarcane-based ethanol shifted the focus squarely back to sugar sales. Balrampur Chini Mills navigated this turn with a strong September quarter, where higher sugar prices more than compensated for the policy change.
The numbers show a decisive recovery from a soft June quarter. Revenue rose 12.3% year-on-year to ₹1,876 crore. Net profit surged 89% to ₹102 crore, with the net profit margin expanding to 5.4% from 3.2% a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 1,876.0 | 1,636.8 |
| Profit (₹ Cr) | 102.0 | 44.2 |
| Net Profit Margin | 5.4% | 2.7% |
Why Profit Outpaced Revenue
The profit jump was powered by the sugar segment. According to the company's investor presentation, average sugar realization rose about 14.5% year-on-year. This more than offset a decline in distillery revenue, which fell to ₹324.59 crore from ₹405.01 crore a year ago, as reported by Arthneeti.
A sharp 51% sequential drop in interest expense and a 369% surge in other income provided a further lift. The other income boost, notes a ScanX report, came from interest income and foreign exchange gains.
The Policy Pivot and Its Duration
The backdrop is a government directive excluding sugarcane juice and B-heavy molasses from the latest ethanol tender. This aims to boost domestic sugar availability amid tight supplies. The policy reduces feedstock flexibility for integrated mills like Balrampur Chini.
Analysts see this supporting sugar prices. Prashant Biyani of Elara Securities told CNBC-TV18 that India's sugar shortage may continue for at least a year. He views Balrampur Chini as a structural growth opportunity, citing rising prices and its upcoming polylactic acid (PLA) project.
The Distillery Drag and Future Capex
While the ethanol segment was softer this quarter, it remains a long-term pillar. The company is commissioning an 80,000-tonne PLA plant in the second half of this fiscal year. This ₹3,080 crore project, detailed by Arthneeti, is a key diversification into bioplastics.
The stock closed at ₹673.65 on the results date, gaining nearly 3%. It trades at a P/E of 26.5, a 46% premium to the industry average, reflecting the market's pricing in of both sugar tailwinds and future projects.
Key Points
- Net profit nearly doubled year-on-year to ₹102 crore, driven by a 14.5% rise in average sugar realizations.
- A government policy shift restricting sugarcane-based ethanol is supporting domestic sugar prices, a trend analysts expect to persist.
- The distillery segment saw revenue decline, but a major polylactic acid (PLA) plant is on track for commissioning this fiscal year.
- Interest costs fell sharply sequentially, and other income provided a meaningful boost to the bottom line.
Hexa Perspective
This quarter underscores the company's ability to leverage its integrated model. The immediate sugar price strength is countering the ethanol policy headwind, a dynamic likely to hold for the coming quarters given the tight supply outlook. The premium valuation suggests investors are looking past the cyclical sugar win toward the PLA project's potential. The risk is that the ethanol segment's contribution remains subdued for longer if policy does not reverse, making the success of the new PLA venture even more critical for diversified growth.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.