Aeroflex Enterprises (AEROENTER) Q2 FY27 Profit Drops 63% Sequentially as One-Off Gains Fade
The September quarter saw revenue jump 45% year-on-year, but profit fell sharply from a Q1 peak inflated by a major stake sale.
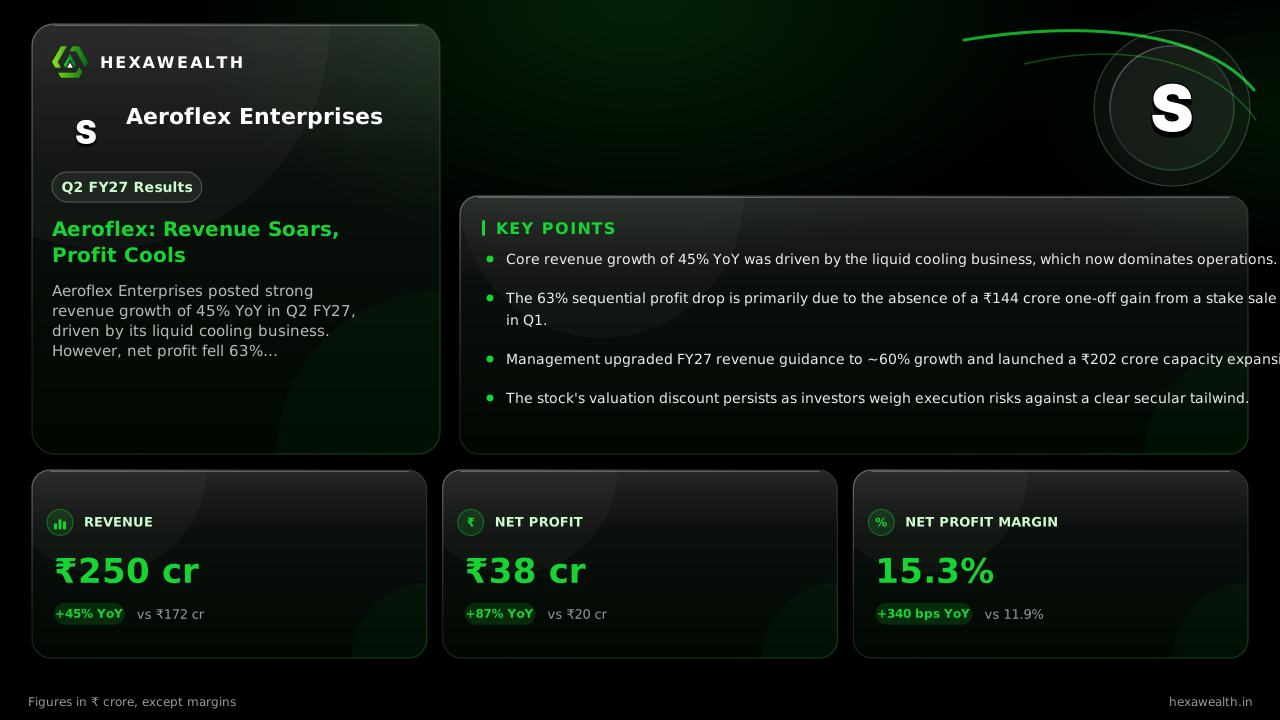
Aeroflex Enterprises posted strong revenue growth of 45% YoY in Q2 FY27, driven by its liquid cooling business. However, net profit fell 63% sequentially as a one-off gain from a stake sale in the previous quarter did not repeat.
For Aeroflex Enterprises, the September quarter was a story of two halves. Core operations, led by surging demand for data center liquid cooling, delivered record revenue. Yet the bottom line retreated sharply, revealing how much the previous quarter's profit was propped up by a non-recurring event.
The numbers show the split. Revenue climbed 45% year-on-year to ₹249.9 crore, and 32% from the June quarter. Net profit, however, fell 63% sequentially to ₹38.24 crore, even as it remained 87% higher than a year ago. The net profit margin compressed to 15.3% from an unsustainably high 54.6% in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 249.9 | 189.0 |
| Profit (₹ Cr) | 38.24 | 103.22 |
| Net Profit Margin (%) | 15.3 | 54.6 |
Why the profit fell from its Q1 peak
The dramatic sequential profit drop stems from a ₹144.17 crore one-off gain in Q1. According to Univest, this came from the sale of the company's stake in its MRO business to Ingersoll Rand. That gain, booked as other income, vanished in Q2, pulling total income and profit back toward a level supported by operations.
Another accounting shift also flattered the Q2 profit figure. The company changed its depreciation method, which Stockwatch.live reported reduced the expense by ₹8.41 crore for the quarter. Strip this out, and the underlying profit expansion looks more modest.
The real engine: liquid cooling
Beneath the accounting noise, a powerful growth story is intact. Scanx.trade reported the Flexible Flow Solution segment, which includes liquid cooling skids, contributed over 81% of operational revenue. Management, cited by Investing.com, highlighted this vertical as a "multi-decade opportunity" driven by AI data center buildouts.
This confidence prompted a major capacity bet. The board approved a fresh ₹202 crore capex plan, as noted by Stockwatch.live. The goal is to double skid assembly capacity by March 2028, targeting incremental revenue of ₹500-550 crore at peak utilization.
Guidance upgraded, execution is key
Management used the strong print to raise its targets. Asad Daud, the Managing Director, guided for approximately 60% full-year revenue growth to ₹715-725 crore for FY27, according to a call transcript on AlphaStreet. The skid business target was lifted to ₹150-200 crore from ₹125 crore.
The market's read is cautiously optimistic. Stockwatch.live noted that while coverage is thin, JM Financial maintains a Buy rating and ICICI Securities is Neutral. The stock trades at a P/E of 11.5, a 44% discount to its industry, reflecting both growth potential and skepticism over the capex payoff.
Key Points
- Core revenue growth of 45% YoY was driven by the liquid cooling business, which now dominates operations.
- The 63% sequential profit drop is primarily due to the absence of a ₹144 crore one-off gain from a stake sale in Q1.
- Management upgraded FY27 revenue guidance to ~60% growth and launched a ₹202 crore capacity expansion.
- The stock's valuation discount persists as investors weigh execution risks against a clear secular tailwind.
Hexa Perspective
The quarter confirms Aeroflex's strategic pivot to liquid cooling is gaining real traction. The underlying operating margin expansion, even after adjusting for accounting benefits, is a positive signal. Yet the path ahead is capital-intensive and hinges on flawless execution of the ₹202 crore capex plan. Investors are left weighing a compelling growth narrative against earnings quality concerns and the stock's persistent discount. The next few quarters will be less about accounting adjustments and more about converting this capacity build into sustained, cash-backed profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.