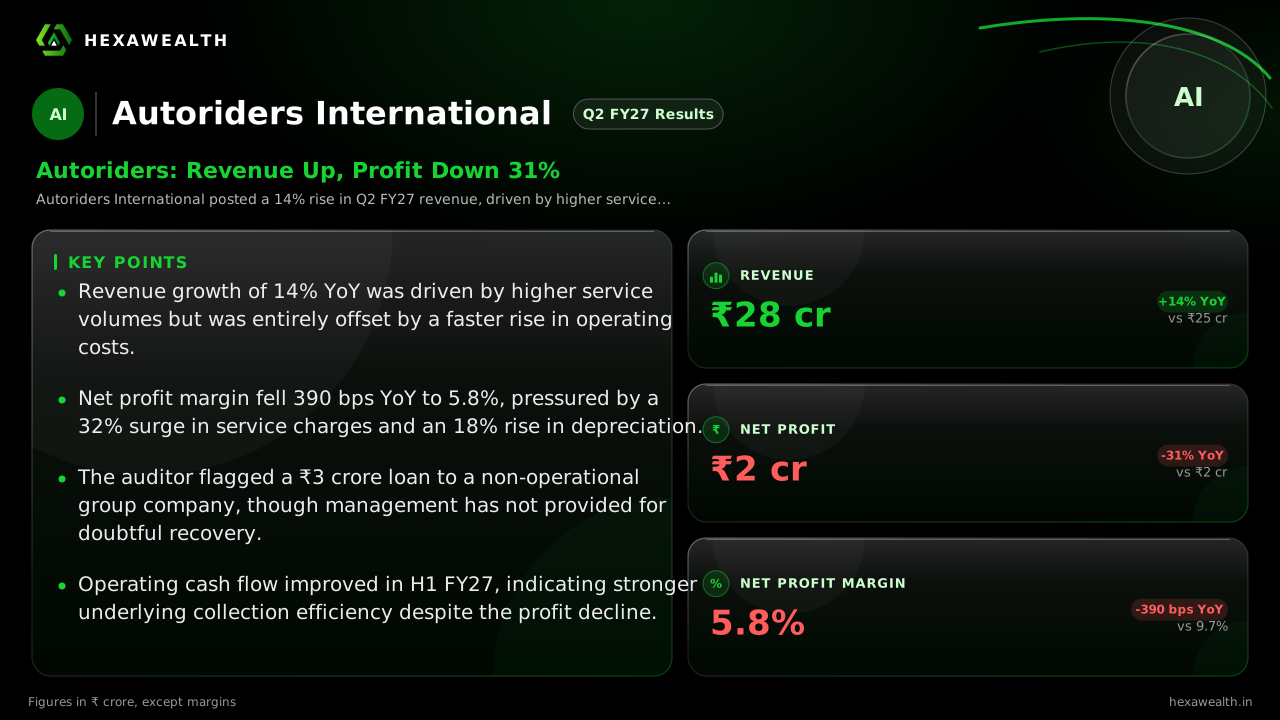
Autoriders International (AUTOINT) Q2 FY27 Profit Slumps 31% Despite Strong Revenue Growth
The car rental firm's Q2 revenue jumped 14% year-on-year, but a sharp rise in service charges and depreciation erased gains, cutting net profit margin by 390 basis points.
Autoriders International posted a 14% rise in Q2 FY27 revenue, driven by higher service volumes. However, net profit fell 31% as soaring operational costs and depreciation compressed margins. The company also flagged a ₹3 crore loan to a group company that has ceased operations.
For Autoriders International, a car rental business built on fleet utilization and cost control, the September quarter delivered a clear split. Demand was strong, but the cost of meeting it was stronger.
Revenue rose 14% year-on-year to ₹28.1 crore, a solid sequential jump from the June quarter. Yet net profit fell 31% to ₹1.64 crore. The net profit margin compressed to 5.8%, down 390 basis points from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 28.09YoY +14% | 24.38 | 24.64 |
| Profit (₹ Cr) | 1.64YoY -31% | 1.02 | 2.39 |
| Net Profit Margin | 5.8%YoY -40% | 4.2% | 9.7% |
Where the Growth Went
The revenue increase, attributed to higher service volumes by ScanX, never reached the bottom line. Total expenses surged 16.5% year-on-year, outpacing sales growth. A 32% jump in service charges was the primary culprit, according to the same report.
Depreciation also rose 18%, likely from fleet additions or upgrades. Meanwhile, other income—a buffer in past quarters—collapsed by 85% year-on-year to just ₹0.05 crore, removing a prior-period tailwind.
A Note of Caution
The statutory auditor included an Emphasis of Matter in the limited review report. It highlights a ₹3 crore loan to a group company that has ceased to be a going concern. Management believes it is recoverable and has made no provision, but the note adds a layer of scrutiny to the balance sheet.
Operationally, cash flow showed a brighter side. ScanX reported cash from operations improved significantly in the first half, driven by better working capital management. This suggests the profit pain is more about accounting costs than cash collection.
Key Points
- Revenue growth of 14% YoY was driven by higher service volumes but was entirely offset by a faster rise in operating costs.
- Net profit margin fell 390 bps YoY to 5.8%, pressured by a 32% surge in service charges and an 18% rise in depreciation.
- The auditor flagged a ₹3 crore loan to a non-operational group company, though management has not provided for doubtful recovery.
- Operating cash flow improved in H1 FY27, indicating stronger underlying collection efficiency despite the profit decline.
Hexa Perspective
The quarter reveals a business caught between healthy demand and intense cost inflation. The margin squeeze is structural, tied to service and depreciation costs that are unlikely to reverse soon. Profitability recovery hinges on the company's ability to pass these costs through pricing or achieve greater operational scale.
The improved cash flow is a positive, suggesting the core rental engine is functioning. However, the auditor's note on the inter-corporate loan introduces an element of balance-sheet risk that investors will watch. With a trailing P/E of 10.1, a steep discount to the industry, the market is pricing in these persistent headwinds.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.