Austere Systems (AUSTERE) Q2 FY27 Profit Crashes 38% as Expenses Overwhelm Revenue
The IT services firm saw a sharp sequential drop in profit as total expenses jumped nearly 23% year-on-year, eroding its net margin.
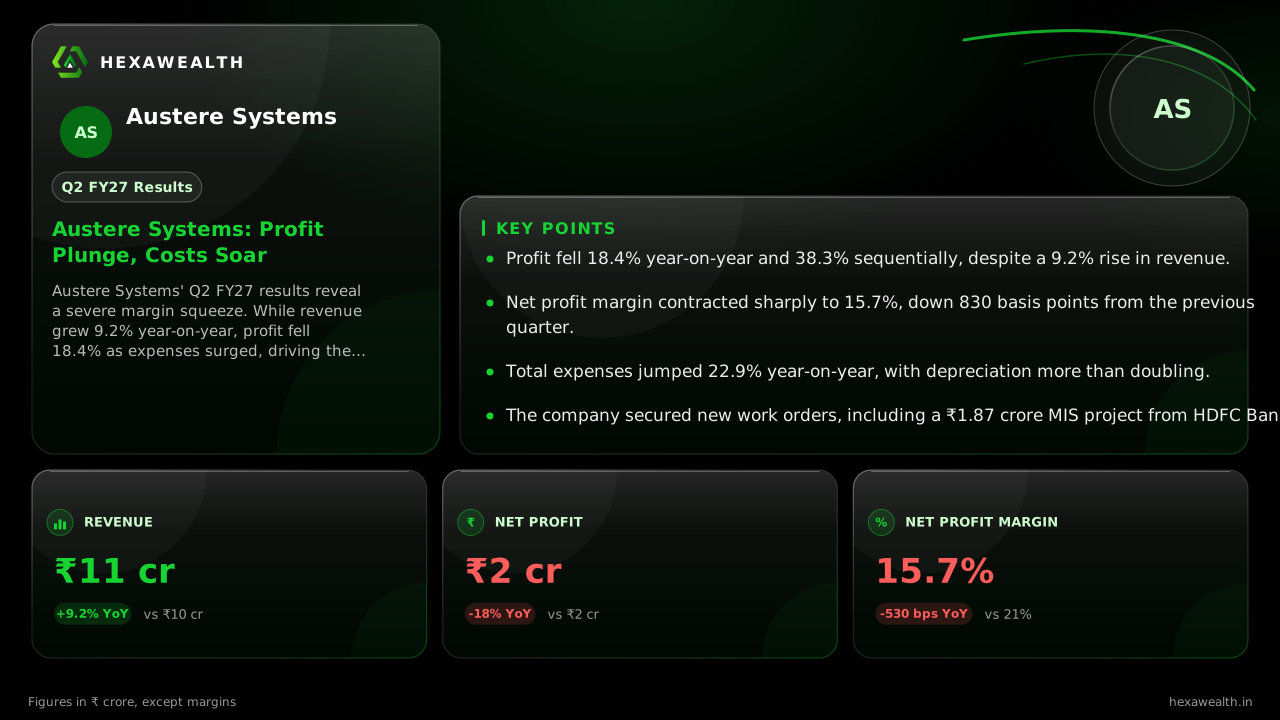
Austere Systems' Q2 FY27 results reveal a severe margin squeeze. While revenue grew 9.2% year-on-year, profit fell 18.4% as expenses surged, driving the net profit margin down 830 basis points from the previous quarter.
For Austere Systems, the September quarter was a story of costs running ahead of business. The IT services firm posted higher revenue but saw its profitability erode sharply, as investments and operational expenses bit deep into the bottom line.
Revenue for Q2 FY27 stood at ₹11.29 crore, up 9.2% from a year ago. Profit, however, fell 18.4% year-on-year to ₹1.77 crore. Sequentially, the picture was worse, with profit down 38.3% and revenue down 5.4%. The net profit margin collapsed to 15.7%, a drop of 830 basis points from the March quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 11.29YoY +9.2% | 10.34 |
| Profit (₹ Cr) | 1.77YoY -18% | 2.17 |
| Net Profit Margin (%) | 15.7YoY -25% | 21.0 |
Where the money went
Total expenses surged 22.9% year-on-year to ₹9.45 crore. A key driver was depreciation, which more than doubled to ₹0.46 crore. This suggests recent capital expenditure is now hitting the income statement. Other income provided a cushion, rising 172% YoY to ₹0.68 crore, but it wasn't enough to offset the operating cost pressure.
The company is navigating a tough sector climate. Analysts at HDFC Securities noted the Indian IT sector is likely to register another muted quarter, with deal wins soft and pricing pressure persisting. Austere's own pipeline shows some promise, with new work orders including a ₹1.87 crore project from HDFC Bank, as per an Alfafinder report.
The road ahead
Management has scheduled an earnings call for November 17 to discuss the results. The key question is whether the expense surge is a one-time investment phase or a new normal. With the stock trading at a P/E of 8.5, a deep discount to the industry average of 20.6, the market has priced in significant skepticism.
Key Points
- Profit fell 18.4% year-on-year and 38.3% sequentially, despite a 9.2% rise in revenue.
- Net profit margin contracted sharply to 15.7%, down 830 basis points from the previous quarter.
- Total expenses jumped 22.9% year-on-year, with depreciation more than doubling.
- The company secured new work orders, including a ₹1.87 crore MIS project from HDFC Bank.
Hexa Perspective
The quarter highlights the execution challenge in a slow-growth IT environment. Revenue growth is being achieved, but at a high cost. The margin compression is severe, and the sustainability of the elevated other income is unclear. Investors are weighing whether current expenses are building capacity for future growth or simply eroding returns. The upcoming management commentary will be crucial to determine if this is a temporary squeeze or a structural shift in profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.