Astal Laboratories (ASTALLTD) Q1 FY27 Profit Rises 23% Even as Revenue Slips 25%
The pharma API maker delivered a 360-basis-point margin expansion sequentially, with a sharp drop in expenses offsetting lower sales in Q1 FY27.
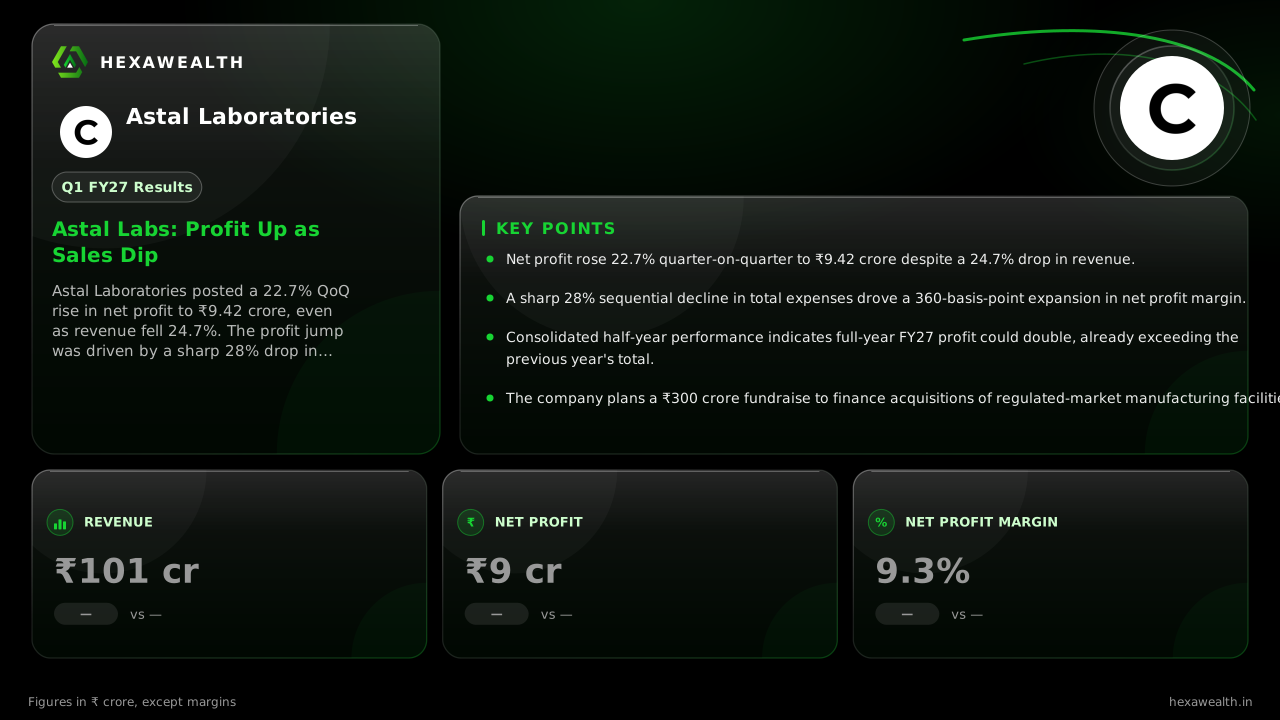
Astal Laboratories posted a 22.7% QoQ rise in net profit to ₹9.42 crore, even as revenue fell 24.7%. The profit jump was driven by a sharp 28% drop in total expenses, boosting the net profit margin to 9.3%.
For a company in the midst of a radical transformation, a quarter of falling sales and rising profit tells a story of execution. Astal Laboratories, pivoting from retail to pharmaceutical APIs, saw revenue dip 25% from the prior quarter, but profit climbed 23%. The gap between the two lines reveals a business learning to run leaner.
Revenue settled at ₹100.94 crore, down from ₹134.05 crore in Q4 FY26. Yet net profit improved to ₹9.42 crore, lifting the net profit margin to 9.3%. The company’s trailing-twelve-month profit stands at ₹22.2 crore on revenue of ₹310.69 crore.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
Net Profit Margin (%)
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 |
|---|---|---|
| Revenue (₹ Cr.) | 100.94 | 134.05 |
| Profit (₹ Cr.) | 9.42 | 7.68 |
| Net Profit Margin (%) | 9.3 | 5.7 |
Where the Profit Came From
The quarter’s profit growth was purely operational. Total expenses fell 28%, led by a 15% drop in employee costs, according to the company’s filings. A report from mcapital.in shows operating profit margin jumped to 12.1%, from 7.6% in the prior quarter. This suggests a focus on cost control and a possible shift in sales mix toward higher-margin products.
The Bigger Picture Emerges
The standalone Q1 numbers are just one piece. Research from mcapital.in indicates the consolidated story is far stronger, driven by the Sriven Pharmachem subsidiary. Consolidated revenue for the first half of FY27 was ₹208.9 crore, already 84% of last year’s full-year sales. More strikingly, H1 profit of ₹19.2 crore has already surpassed FY26’s full-year profit of ₹14.8 crore.
This run-rate implies a potential doubling of profit this year. The company’s board has also approved a plan to raise up to ₹300 crore, with a mandate to seek acquisitions of USFDA or EU-GMP certified manufacturing units, as per an alfafinder.com report.
Key Points
- Net profit rose 22.7% quarter-on-quarter to ₹9.42 crore despite a 24.7% drop in revenue.
- A sharp 28% sequential decline in total expenses drove a 360-basis-point expansion in net profit margin.
- Consolidated half-year performance indicates full-year FY27 profit could double, already exceeding the previous year's total.
- The company plans a ₹300 crore fundraise to finance acquisitions of regulated-market manufacturing facilities.
Hexa Perspective
This quarter shows Astal Labs navigating the volatility of a young API business. The sequential sales dip is less concerning than the demonstrated ability to protect and even expand margins when revenue softens. The real story is the explosive growth visible in the half-year consolidated numbers, which points to a successful integration of its key subsidiary.
The path ahead hinges on converting its acquisition mandate into tangible capacity that can serve regulated markets. If executed, this could be the step that moves the company from a domestic bulk drug player to a globally relevant manufacturer. The current valuation, trading at a 55% discount to the industry PE, reflects the market’s wait for that proof.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.