All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20262 min read

Energy-Mission (EMMIL) Q2 FY27 Profit Falls 30% Despite Higher Revenue as Costs Bite

Energy-Mission Machineries posted a 6.6% rise in Q2 FY27 revenue, but net profit fell 30% year-on-year as expenses climbed and margins contracted sharply.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 14 November 2026

Energy-Mission Machineries reported a 6.6% year-on-year revenue increase to ₹80.86 crore for Q2 FY27. However, net profit declined 30% to ₹4.49 crore, with the net profit margin contracting 300 basis points due to rising costs.

For a capital goods maker riding an industrial expansion wave, the second quarter should have been about converting capacity into profit. Energy-Mission Machineries saw its revenue rise, but the bottom line told a different story.

Revenue for the September 2026 quarter grew 6.6% year-on-year to ₹80.86 crore. Net profit, however, fell 30% to ₹4.49 crore. The net profit margin compressed to 5.5%, down 300 basis points from the same quarter last year.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
80.86YoY +6.6%
75.85
Profit (₹ Cr)
4.49YoY -30%
6.42
Net Profit Margin (%)
5.5YoY -35%
8.5

The squeeze from higher costs

Total expenses rose over 10% year-on-year, outpacing revenue growth. A sharp 87% drop in other income, as per the payload, also removed a cushion. Higher depreciation and interest costs, up 21% and 17% respectively, point to the financial impact of recent capital expenditure.

Management had previously expanded capacity from 900 to 1,500 machines annually, reports Arthneeti. A new backward integration facility also became operational in June 2026, aimed at cutting future job-work costs.

Demand visibility versus margin pressure

The underlying demand story appears intact. An investor presentation in June 2026, cited by Newboard, noted a ₹47.23 crore order book and said orders in the first two months of FY27 were 16% higher year-on-year. The industry is also growing at a 12-15% CAGR, according to Mordor Intelligence.

The challenge is that these benefits are yet to fully offset the current cost inflation and the drag from new asset depreciation. The company's three-year target, as per Newboard, is an 8% profit margin, but the Q2 print of 5.5% shows a significant gap.

Key Points

  • Revenue grew 6.6% YoY to ₹80.86 crore, but net profit declined 30% to ₹4.49 crore.
  • Net profit margin contracted 300 basis points YoY to 5.5%, pressured by a >10% rise in total expenses and lower other income.
  • Higher depreciation and interest costs reflect investments in expanded capacity and backward integration, which are expected to aid margins in the future.
  • A healthy order book and strong industry growth provide revenue visibility, but near-term profitability remains under pressure.

Hexa Perspective

The quarter highlights the classic tension between growth investment and immediate profitability. Energy-Mission is funding its expansion, evident in rising fixed costs, while revenue is yet to catch up at a pace that protects margins.

The path to its targeted 8% profit margin hinges on two factors: realizing the cost savings from its new in-house component plant and achieving higher utilization of its expanded capacity. Until those operational levers are pulled effectively, the margin squeeze may persist for another quarter or two.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
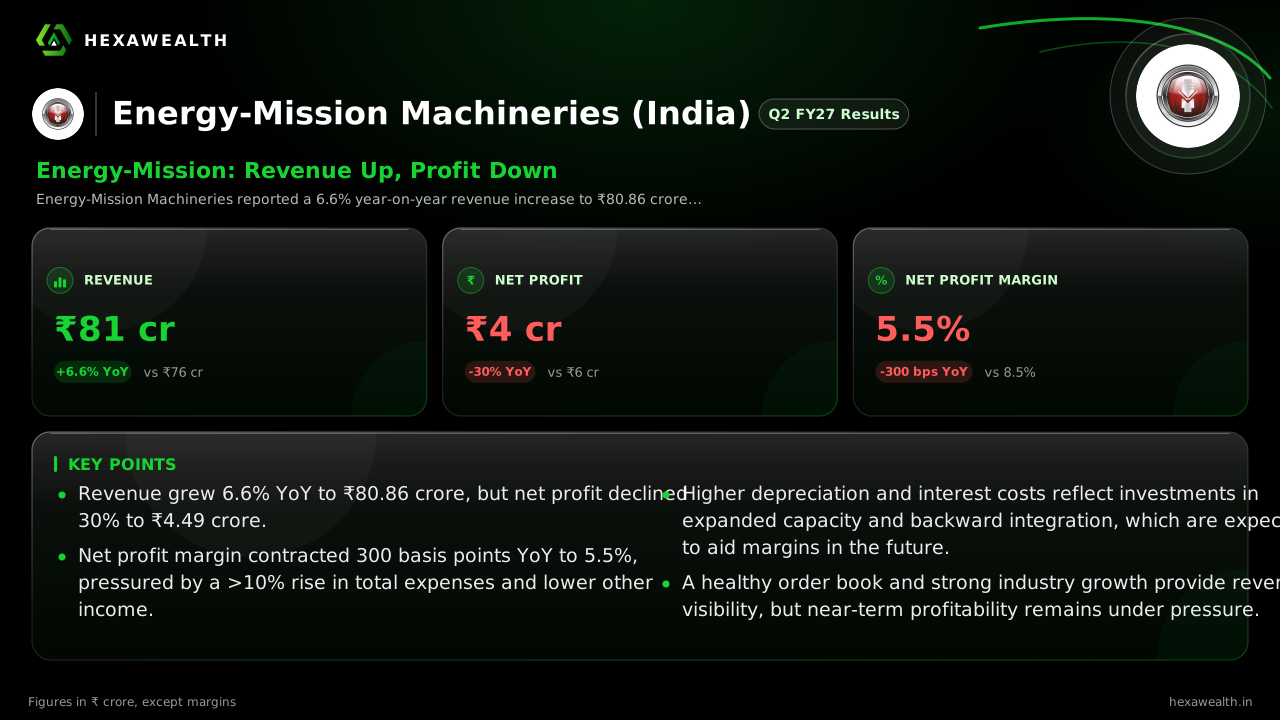
Energy-Mission Machineries (India) (EMMIL) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Energy-Mission Machineries' Q2 FY27 results?
For Q2 FY27 (September 2026 quarter), Energy-Mission Machineries reported revenue of ₹80.86 crore, a 6.6% year-on-year increase. Net profit was ₹4.49 crore, a decline of 30.1% from the same quarter last year. The net profit margin stood at 5.5%.
Why did Energy-Mission Machineries' profit fall 30% year-on-year despite a 6.6% rise in revenue in Q2 FY27?
Energy-Mission's profit fell due to a significant margin squeeze. Total expenses rose over 10% year-on-year, outpacing revenue growth. Furthermore, other income fell sharply by 87%, and depreciation and interest costs increased, reflecting the financial impact of recent capital expenditure.
What caused the 300 bps year-on-year contraction in net profit margin for Energy-Mission Machineries in the September 2026 quarter?
The 300 basis point margin contraction was driven by total expenses growing faster than revenue. Key factors included a 21% rise in depreciation and a 17% increase in interest costs, linked to capacity expansion, coupled with an 87% decline in other income.
Did lower other income contribute to Energy-Mission Machineries' weaker Q2 FY27 profit?
Yes, lower other income was a significant factor. It fell by 87.2% year-on-year to ₹0.05 crore in Q2 FY27, from ₹0.38 crore in Q2 FY26. This removed a financial cushion that had supported profit in the prior-year period.
Why did total expenses for Energy-Mission Machineries rise over 10% year-on-year in Q2 FY27?
The rise in total expenses was driven by multiple factors. Depreciation increased by 20.9% and interest costs rose by 16.8% year-on-year, reflecting the company's investment in expanded manufacturing capacity and a new backward integration facility.
Was the rise in depreciation and interest costs for Energy-Mission Machineries in Q2 FY27 due to new capex or higher debt?
The rise is attributed to new capital expenditure. The company expanded its annual manufacturing capacity from 900 to 1,500 machines, as reported by Arthneeti. This investment in fixed assets leads to higher depreciation and associated financing costs.
What was the demand and order book trend for Energy-Mission Machineries' hydraulic shearing and press brake machines in Q2 FY27?
Demand appears healthy. An investor presentation cited by Newboard noted a ₹47.23 crore order book as of June 2026. It also stated that order inflow in the first two months of FY27 was 16% higher than the same period a year earlier.
What guidance did Energy-Mission Machineries management provide for FY27?
While specific Q2 concall details for Energy-Mission are not in the research, past presentations outline a three-year target. Management aims for 18-20% revenue CAGR and a profit margin of 8% by FY29, driven by capacity utilization and backward integration savings.
What is the update on Energy-Mission Machineries' working capital and cash flow situation?
Annual data from Newboard shows operating cash flow improved significantly to ₹14.76 crore in FY26 from an outflow of ₹7.68 crore in FY25. However, the cash conversion cycle was 266 days in FY26, indicating a lengthy period to convert inventory and receivables into cash.
Is Energy-Mission Machineries undertaking any capacity expansion or major capex projects?
Yes. The company completed an expansion, raising capacity from 900 to 1,500 machines per annum in July 2025. A new 5,000 sq. m backward integration plant, EM Press Form Solutions, became operational in June 2026 to reduce external job-work costs.
Did Energy-Mission Machineries' Q2 FY27 results beat or miss analyst estimates?
The provided research does not contain specific analyst estimates or consensus figures for Energy-Mission Machineries' Q2 FY27 results to determine a beat or miss.
Have any brokerages changed their rating or target price for Energy-Mission Machineries after the Q2 FY27 results?
According to a Sharpely.in report from October 2026, there were no active analyst recommendations or target prices for Energy-Mission Machineries at that time. No updated post-research actions are indicated in the provided snippets.
How did Energy-Mission Machineries stock price react to the Q2 FY27 results announcement?
The provided research snippets do not contain specific information about the stock price movement on or immediately after the Q2 FY27 results announcement date of 14-Nov-2026.
Energy-Mission Machineries Q2 net profit
Energy-Mission Machineries' net profit for Q2 FY27 (September 2026 quarter) was ₹4.49 crore. This represents a 30.1% decline from the ₹6.42 crore net profit reported in the same quarter the previous year (Q2 FY26).
Energy-Mission Machineries September quarter profit
Energy-Mission Machineries' profit for the September 2026 quarter (Q2 FY27) was ₹4.49 crore. This is lower than the ₹6.42 crore profit from the September 2025 quarter, marking a 30.1% year-on-year decline.