Athena Global (ATHENAGLO) Q1 FY27 Revenue Jumps 57% as Losses Narrow from Prior Quarter
Athena Global Technologies posted a 57% year-on-year revenue surge in Q1 FY27, though a high interest burden kept the company in the red.
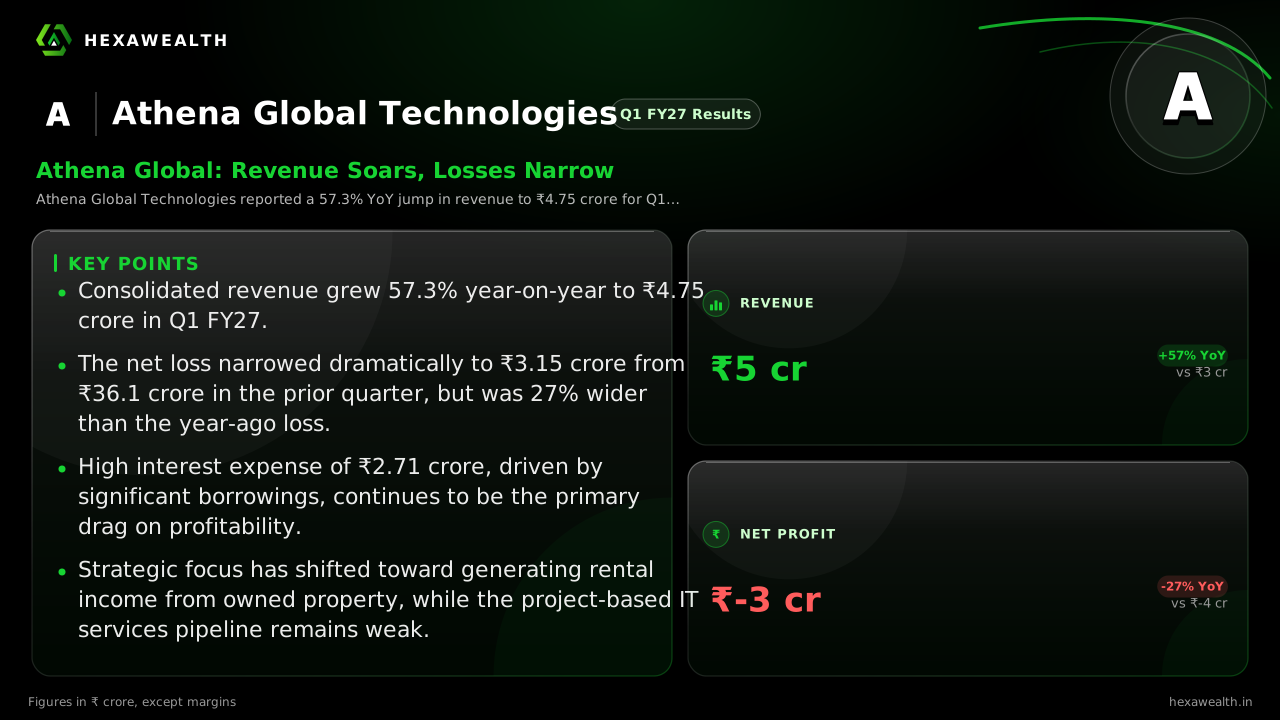
Athena Global Technologies reported a 57.3% YoY jump in revenue to ₹4.75 crore for Q1 FY27. The net loss narrowed sharply to ₹3.15 crore from the prior quarter's deep loss, but interest costs remain a heavy drag on profitability.
For a company navigating a multi-year turnaround, the headline for Athena Global Technologies' first quarter is a tale of two trends. Revenue surged past year-ago levels, yet the bottom line remains firmly negative, held down by a structural cost that won't ease soon.
Revenue rose 57% from a year ago to ₹4.75 crore, according to the company's consolidated results. Sequentially, sales grew 40% from the ₹3.4 crore reported in Q4 FY26. The net loss for the June quarter was ₹3.15 crore, a sharp improvement from the ₹36.1 crore loss in the prior quarter but 27% wider than the loss in Q1 FY26.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4.75YoY +57% | 3.40 | 3.02 |
| Net Profit (₹ Cr) | -3.15YoY +27% | -36.10 | -4.34 |
The Interest Burden That Won't Budge
The stark gap between rising revenue and persistent losses points directly to the company's debt. Interest expense consumed ₹2.71 crore this quarter, nearly 60% of total revenue. This stems from borrowings of ₹130 crore against equity of ₹142 crore, resulting in a debt-to-equity ratio of 0.92, as noted by analysis from StockFin.ai.
While employee costs fell 31% from the prior quarter, offering some relief, the interest line remains a fixed and heavy weight. It ensures that even significant revenue growth is quickly absorbed before reaching the bottom line.
A Pipeline of Property, Not Projects
Management's strategic moves, reported by outlets like ALFA Finder, highlight a pivot toward asset-based income. The board approved a ₹50 crore investment in optionally convertible debentures of its subsidiaries. More notably, the company signed a five-year lease agreement for a Hyderabad property, securing annual rental income of ₹11.19 crore.
This deal, as analysis from Scanx.trade points out, provides a recurring income stream but is distinct from project-based work orders. The company's core software services order book remains at zero coverage, indicating revenue stability is not yet driven by its primary IT business.
Key Points
- Consolidated revenue grew 57.3% year-on-year to ₹4.75 crore in Q1 FY27.
- The net loss narrowed dramatically to ₹3.15 crore from ₹36.1 crore in the prior quarter, but was 27% wider than the year-ago loss.
- High interest expense of ₹2.71 crore, driven by significant borrowings, continues to be the primary drag on profitability.
- Strategic focus has shifted toward generating rental income from owned property, while the project-based IT services pipeline remains weak.
Hexa Perspective
The quarter shows Athena Global is successfully stemming the bleeding from operations, with revenue recovering and employee costs falling. Yet the path to sustained profitability is blocked by its capital structure. The interest burden from past borrowings is a fixed cost that the current scale of operations cannot support.
The new rental income is a crucial lifeline that will improve cash flow, but it does not solve the core issue of a dormant project pipeline. Investors are left weighing the value of the company's real estate assets against the ongoing losses from its nominal IT services business. Until the debt is restructured or the core business scales dramatically, profits will remain out of reach.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.