TVS Srichakra (TVSSRICHAK) Q2 FY27 Profit Quadruples as Volume and Efficiency Offset Cost Surge
The tyre maker's Q2 net profit surged over 300% year-on-year, as operating leverage from strong volume growth more than countered a sharp rise in raw material costs.
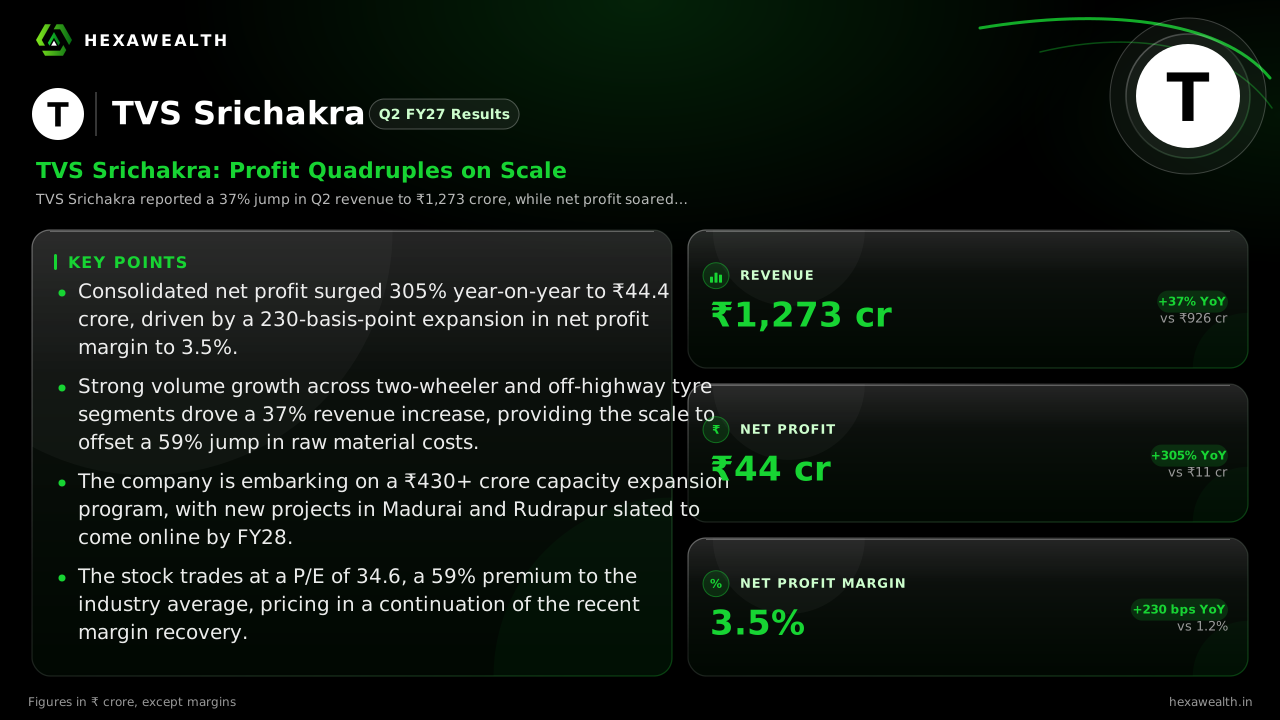
TVS Srichakra reported a 37% jump in Q2 revenue to ₹1,273 crore, while net profit soared 305% to ₹44.4 crore. The growth was margin-led, with efficiency gains offsetting significant input cost inflation across the industry.
For tyre makers, the story this quarter has been a painful squeeze between soaring raw material costs and the need to protect market share. TVS Srichakra’s September quarter shows it navigated that tension by growing fast enough to make efficiency count, turning a 37% revenue surge into a 305% profit explosion.
Revenue reached ₹1,273 crore, up 19% from the June quarter. Net profit climbed to ₹44.4 crore, extending a margin recovery that began last quarter. The company’s net profit margin expanded to 3.5%, a 230-basis-point improvement from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,272.63YoY +37% | 1,067.61 | 926.49 |
| Profit (₹ Cr) | 44.43YoY +305% | 34.02 | 10.96 |
| Net Profit Margin | 3.5%YoY +192% | 3.2% | 1.2% |
The efficiency that beat the cost surge
The headline profit jump is not a one-off. According to StockWatch, adjusted profit growth still exceeded 200% year-on-year after removing small voluntary retirement scheme costs. This was a margin-led story. The cost of materials consumed rose 59% year-on-year, outpacing revenue growth. But employee costs rose only 10%, and other expenses grew at a slower 34% pace, showing the power of operating leverage at scale. The calculated EBITDA margin, reports Perivis, was approximately 8.2%, up from about 6.8% a year earlier.
A sector-wide pressure test
This margin defence stands out. Peers like MRF saw profit skid 28% despite revenue growth, as raw material costs surged. Apollo Tyres reported its India EBITDA margin fell to 11.1% from 15.3% a year ago. The industry, notes Business Standard, is grappling with raw material costs that have risen about 25% since April, forcing frequent but gradual price hikes. TVS Srichakra’s performance suggests its volume growth in core two-wheeler and off-highway segments, as highlighted by Sahi.com, provided the necessary scale to absorb the hit.
Funding the next growth phase
The company is entering a new investment cycle to meet this demand. India Ratings affirms its credit profile, noting board approvals for up to ₹220 crore of capex in Madurai for off-highway and two-wheeler tyre capacity, and ₹210 crore in Rudrapur. A further ₹49.2 crore for debottlenecking was approved in October. These projects, funded by debt and internal accruals, aim to bring new capacity online by FY28. While this will moderate deleveraging, the rating agency expects credit metrics to improve as new capacities ramp up.
Key Points
- Consolidated net profit surged 305% year-on-year to ₹44.4 crore, driven by a 230-basis-point expansion in net profit margin to 3.5%.
- Strong volume growth across two-wheeler and off-highway tyre segments drove a 37% revenue increase, providing the scale to offset a 59% jump in raw material costs.
- The company is embarking on a ₹430+ crore capacity expansion program, with new projects in Madurai and Rudrapur slated to come online by FY28.
- The stock trades at a P/E of 34.6, a 59% premium to the industry average, pricing in a continuation of the recent margin recovery.
Hexa Perspective
The quarter answers a key question: TVS Srichakra can defend margins in a hostile cost environment if volumes are strong. The sustainability of this outperformance now hinges on two factors. First, whether industry-wide raw material inflation, expected by Apollo Tyres to peak toward year-end, actually moderates. Second, if the company’s own capacity additions can keep pace with demand without straining its balance sheet. The current valuation premium suggests the market is betting the momentum holds, but the margin buffer remains thin enough for any volume slowdown to quickly reverse the gains.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.