Auro Laboratories (AUROLAB) Q2 FY27 Profit Lags Behind a 58% Revenue Surge
The API maker's Q2 sales nearly doubled year-on-year, but higher finance and depreciation costs from its expanded plant kept a lid on profitability.
Auro Laboratories posted a 58% jump in Q2 FY27 revenue to ₹13.94 crore, yet net profit grew only 11% sequentially. The gap highlights the cost of its recent capacity expansion at the Tarapur plant.
For Auro Laboratories, a specialist in active pharmaceutical ingredients, the September quarter was about scale finally arriving. After years of modest sales, revenue surged to its highest level in at least five quarters, signaling a potential inflection. Yet the profit story was more muted, as the costs of building that capacity began to bite.
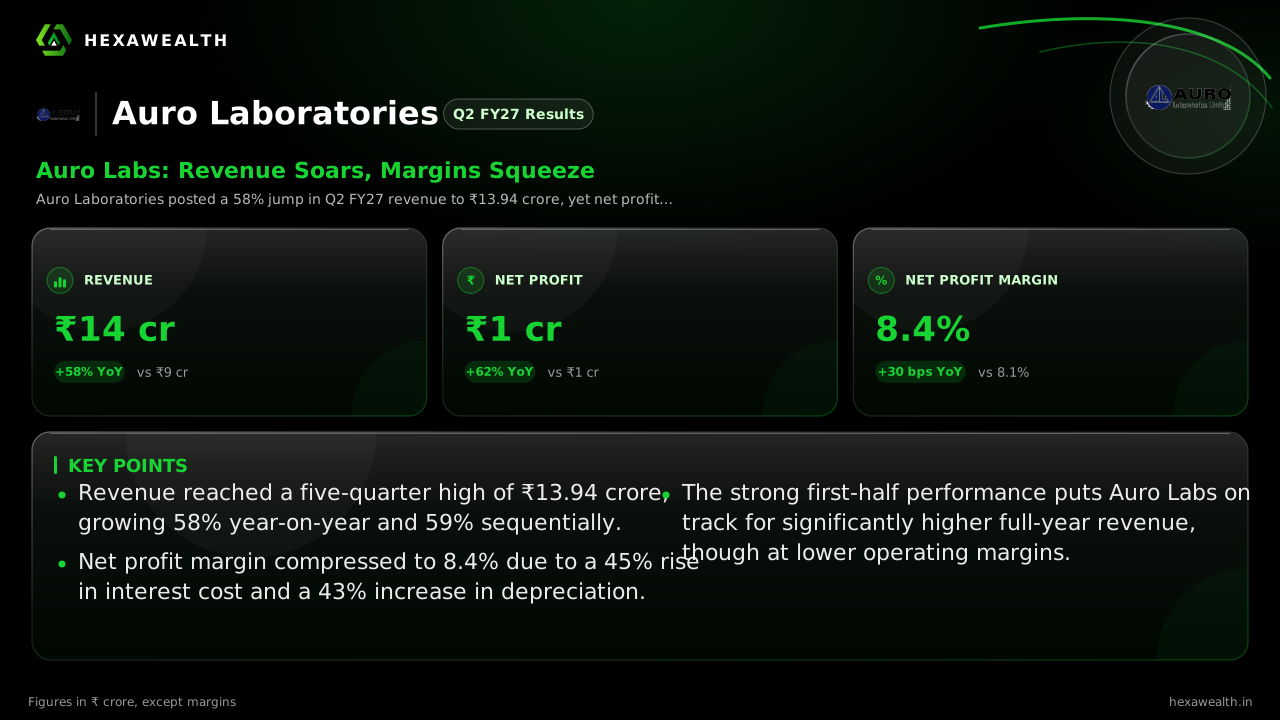
The numbers show a company in transition. Revenue hit ₹13.94 crore, up 58% from a year ago and 59% from the prior quarter. Net profit rose 62% year-on-year to ₹1.17 crore, but grew just 11% sequentially. The net profit margin slid to 8.4%, a 350-basis-point drop from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 13.94YoY +58% | 8.77 | 8.84 |
| Profit (₹ Cr) | 1.17YoY +63% | 1.05 | 0.72 |
| Net Profit Margin | 8.4%YoY +3.7% | 11.9% | 8.1% |
Why the profit didn't keep pace
The margin squeeze came from the very investment driving growth. Research from mCapital.in notes the surge comes with higher finance and depreciation costs from the company's expanded Tarapur plant. Interest expense rose 45% year-on-year to ₹1.39 crore, while depreciation climbed 43% to ₹0.93 crore.
Crucially, this growth was driven by core operations, not one-offs. Other income fell 75% year-on-year to just ₹0.24 crore, according to filings cited by Alfafinder.com. The profit increase was almost entirely operational.
The outlook hinges on utilization
Management appears confident the revenue run-rate can hold. An analysis by mCapital.in, based on the record first-half sales, suggests the company is on track for 40-55% higher revenue over the next 12 months. First-half revenue of ₹22.71 crore is already 74% of the full-year FY26 figure.
The key will be whether this new sales volume can outrun the fixed costs of expansion. The same analysis projects operating margins may settle 3-5 percentage points below the FY26 level of 33.2% for the next year. The stock closed flat at ₹234.30 on results day, as the market digested the high-growth, lower-margin print.
Key Points
- Revenue reached a five-quarter high of ₹13.94 crore, growing 58% year-on-year and 59% sequentially.
- Net profit margin compressed to 8.4% due to a 45% rise in interest cost and a 43% increase in depreciation.
- The strong first-half performance puts Auro Labs on track for significantly higher full-year revenue, though at lower operating margins.
Hexa Perspective
This quarter frames Auro Laboratories' central challenge: monetizing a major capacity build. The revenue leap confirms demand for its APIs, a positive shift from its historical sales base. Yet, with a debt-to-equity ratio of 1.37, the financial leverage supporting this growth is substantial.
The next few quarters will test if operating leverage can finally kick in. Success means growing sales absorb the higher finance and depreciation, lifting margins back toward the 12.3% TTM average. Stagnation would leave profitability pressured under the weight of its expanded balance sheet.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.