Yajur Fibres (YAJUR) Profit Plunges 44% as Revenue Falls 18% in Q4 FY26
The textile firm's quarterly and annual performance weakened sharply, with delayed capex and a tough market outlook clouding its FY27 prospects.
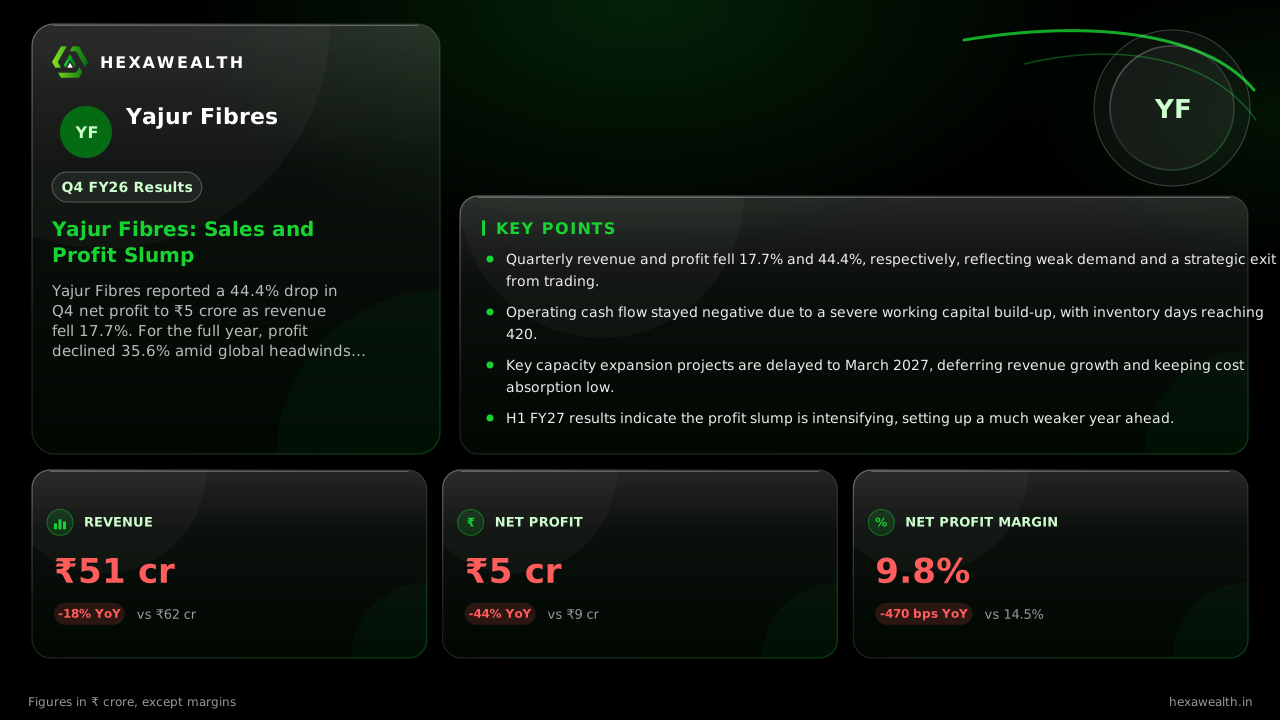
Yajur Fibres reported a 44.4% drop in Q4 net profit to ₹5 crore as revenue fell 17.7%. For the full year, profit declined 35.6% amid global headwinds and a strategic shift away from trading operations.
Yajur Fibres entered its first year as a listed company with a sharp operational slowdown. The Q4 FY26 results confirmed a difficult year, where strategic shifts and external pressures pulled down both sales and earnings.
The quarter saw revenue fall 17.7% to ₹51 crore, while net profit dropped 44.4% to ₹5 crore. This squeezed the net profit margin by 470 basis points to 9.8%. For the full year, the story was similar, with revenue down 28.2% and profit down 35.6%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 62.0
- Revenue (₹ Cr), Q4 FY26: 51.0
- Net Profit (₹ Cr), Q4 FY25: 9.0
- Net Profit (₹ Cr), Q4 FY26: 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 62.0
- Revenue (₹ Cr), Q4 FY26: 51.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q4 FY25: 9.0
- Net Profit (₹ Cr), Q4 FY26: 5.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 14.5
- Net Profit Margin (%), Q4 FY26: 9.8
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 51.0YoY -18% | 62.0 |
| Net Profit (₹ Cr) | 5.0YoY -44% | 9.0 |
| Net Profit Margin (%) | 9.8YoY -32% | 14.5 |
Why the Top Line Shrank
Management, cited by ScanX, attributed the annual decline to US-centric trade tariffs and geopolitical tensions disrupting supply chains since early 2026. More significantly, the company made a planned reduction of approximately ₹27 crore in trading revenue. This was a strategic move to cease all trading operations at its subsidiary, Yashoda Linen Yarn, and focus resources on commissioning a new manufacturing unit.
The Cash Flow Conundrum
Despite a 90% year-on-year improvement, operating cash flow remained deeply negative at ₹-48.22 crore for FY26. A report from mCapital.in points to a massive build-up in working capital, with inventory days ballooning to 420. The ₹31 crore of unspent IPO proceeds sitting in fixed deposits earn interest but do not fund day-to-day operations, leaving cash flow strained.
Delayed Growth, Pressured Margins
The path to recovery hinges on two delayed expansion projects. Both a brownfield expansion in Howrah and a greenfield linen yarn unit in Ujjain are now extended to March 31, 2027, as per a monitoring agency report. This deferral means no incremental sales from new capacity for at least the next year, keeping margins under pressure from under-absorbed costs.
Live Chart
· YAJUR
(BSE)
ISIN: INE0CNJ01010
The weak run-rate has continued into the new fiscal year. The company's unaudited H1 FY27 results show profit collapsing by about 58% on flat revenue, according to mCapital.in. This points to a materially weaker full-year FY27, with earnings potentially 50-60% lower than FY26.
Key Points
- Quarterly revenue and profit fell 17.7% and 44.4%, respectively, reflecting weak demand and a strategic exit from trading.
- Operating cash flow stayed negative due to a severe working capital build-up, with inventory days reaching 420.
- Key capacity expansion projects are delayed to March 2027, deferring revenue growth and keeping cost absorption low.
- H1 FY27 results indicate the profit slump is intensifying, setting up a much weaker year ahead.
Hexa Perspective
The quarter closes a year where Yajur Fibres traded near-term revenue for a long-term manufacturing bet. The balance sheet is flush with IPO cash, but operating metrics are deteriorating rapidly. Investors are now caught between a discounted valuation—the stock trades at a 63% discount to the industry P/E—and the reality that earnings may not rebound until the new plants are operational in FY28. The next few quarters will test the company's ability to manage costs and working capital while it waits for its delayed capex to bear fruit.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.