West Coast Paper (WSTCSTPAPR) Q2 FY27 Profit Soars 828% as Costs Plummet
The paper maker's net profit jumped over eight-fold year-on-year despite lower revenue, driven by a dramatic fall in employee, interest, and depreciation costs.
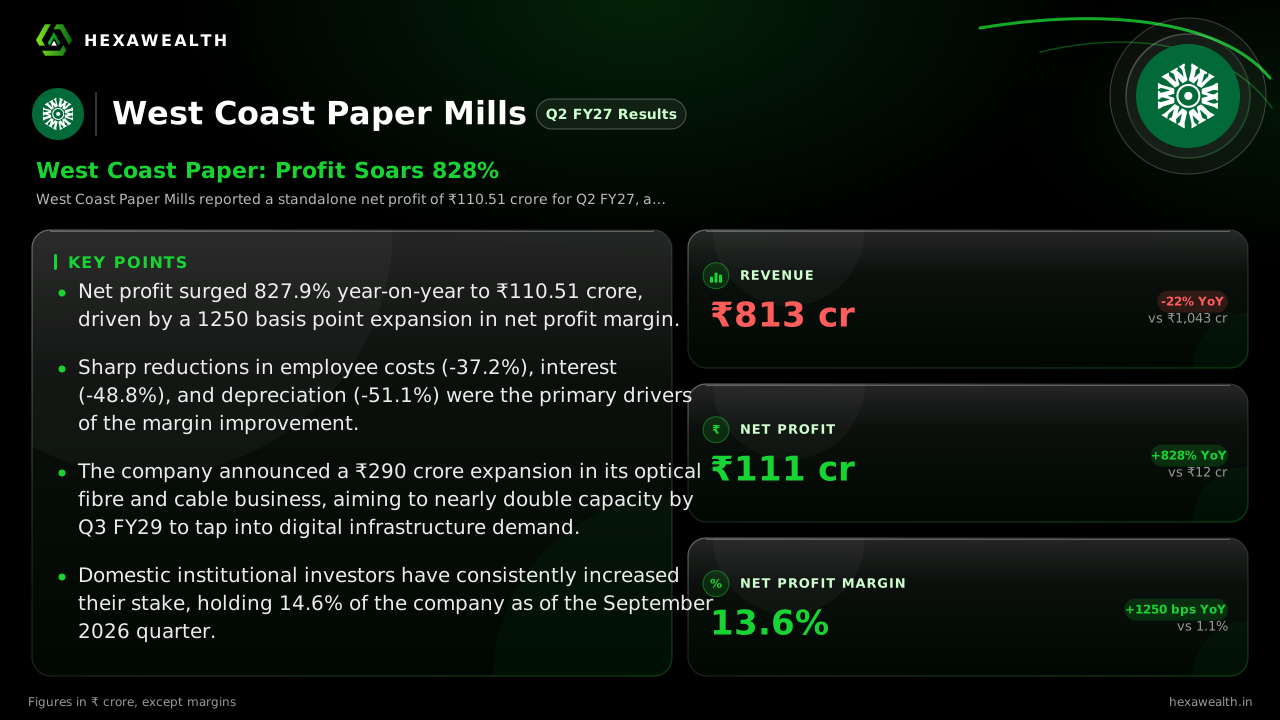
West Coast Paper Mills reported a standalone net profit of ₹110.51 crore for Q2 FY27, a staggering 827.9% increase from a year ago. This surge came even as revenue fell 22.1%, highlighting a powerful margin expansion story.
For West Coast Paper Mills, the September quarter was a story of efficiency triumphing over sales. The company delivered a massive profit surge not by selling more paper, but by radically tightening its cost structure across the board.
Standalone revenue fell 22.1% year-on-year to ₹812.97 crore. Yet, net profit rocketed 827.9% to ₹110.51 crore. The net profit margin tells the tale, leaping to 13.6% from just 1.1% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1043.02
- Revenue (₹ Cr), Q3 FY26: 1049.78
- Revenue (₹ Cr), Q4 FY26: 1245.30
- Revenue (₹ Cr), Q1 FY27: 1051.26
- Revenue (₹ Cr), Q2 FY27: 812.97
- Profit (₹ Cr), Q2 FY26: 11.91
- Profit (₹ Cr), Q3 FY26: 29.58
- Profit (₹ Cr), Q4 FY26: 53.98
- Profit (₹ Cr), Q1 FY27: 141.84
- Profit (₹ Cr), Q2 FY27: 110.51
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1043.02
- Revenue (₹ Cr), Q3 FY26: 1049.78
- Revenue (₹ Cr), Q4 FY26: 1245.30
- Revenue (₹ Cr), Q1 FY27: 1051.26
- Revenue (₹ Cr), Q2 FY27: 812.97
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 11.91
- Profit (₹ Cr), Q3 FY26: 29.58
- Profit (₹ Cr), Q4 FY26: 53.98
- Profit (₹ Cr), Q1 FY27: 141.84
- Profit (₹ Cr), Q2 FY27: 110.51
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 1.1
- Net Profit Margin (%), Q3 FY26: 2.8
- Net Profit Margin (%), Q4 FY26: 4.3
- Net Profit Margin (%), Q1 FY27: 13.5
- Net Profit Margin (%), Q2 FY27: 13.6
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 812.97YoY -22% | 1051.26 | 1043.02 |
| Profit (₹ Cr) | 110.51YoY +828% | 141.84 | 11.91 |
| Net Profit Margin (%) | 13.6YoY +1136% | 13.5 | 1.1 |
The cost cuts that powered profit
The profit explosion was fuelled by a dramatic reduction in three major expense lines. Employee costs fell 37.2% year-on-year, interest expense dropped 48.8%, and depreciation charges were down 51.1%. This disciplined cost management, reported by Sahi.com, expanded operating EBITDA margin to 15.2% from 6.5% a year ago.
Management attributed higher input costs in the Paper Division as a headwind. However, the newer Cable Division saw improvement through better efficiency and product mix, according to Tradebrains.in. This operational focus allowed profitability to soar even as top-line pressure from the paper business persisted.
A strategic pivot to fibre
Alongside the results, the board approved a ₹290 crore expansion of its optical fibre and cable capacity, targeting completion by Q3 FY29. Joint Managing Director Virendraa Bangur told Multibagg.ai the move targets demand from data centres, AI infrastructure, and telecom. This strategic capex aims to diversify earnings away from the volatile paper cycle.
Live Chart
· WSTCSTPAPR
(BSE)
ISIN: INE976A01021
The market has taken note of the transformation. Domestic institutional investors have raised their stake for 11 consecutive quarters, reaching 14.6% by September 2026, as per SectorAlpha.in. The stock has delivered a 92.7% return over the past year, though it trades at a slight discount to the industry PE.
Key Points
- Net profit surged 827.9% year-on-year to ₹110.51 crore, driven by a 1250 basis point expansion in net profit margin.
- Sharp reductions in employee costs (-37.2%), interest (-48.8%), and depreciation (-51.1%) were the primary drivers of the margin improvement.
- The company announced a ₹290 crore expansion in its optical fibre and cable business, aiming to nearly double capacity by Q3 FY29 to tap into digital infrastructure demand.
- Domestic institutional investors have consistently increased their stake, holding 14.6% of the company as of the September 2026 quarter.
Hexa Perspective
The quarter showcases a powerful operational turnaround where cost control has more than offset revenue softness. The sustainability of these margins is the key question. With the paper industry facing input cost volatility and import pressure, maintaining this discipline will be critical.
The large fibre expansion signals a strategic bet to reduce cyclicality. The payoff is years away, but it provides a long-term growth avenue distinct from the core paper business. For now, investors are rewarding the demonstrated ability to squeeze profit from a challenging top line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.