Roopshri Resorts (ROOPSHRI)' Revenue Jumps 117% but Profit Shrinks 38% in Q4 FY26
The hospitality firm's March quarter saw strong revenue growth, but a sharp rise in interest and depreciation costs severely compressed its bottom line.
Roopshri Resorts reported a 116.5% surge in Q4 FY26 revenue to ₹1.71 crore. However, net profit fell 37.5% to ₹0.05 crore as interest and depreciation costs soared, slashing the net profit margin by 720 basis points year-on-year.
For a single-hotel company like Roopshri Resorts, a strong revenue quarter should translate directly to the bottom line. The March quarter delivered the top-line surge, with revenue more than doubling from a year ago. Yet profitability collapsed, revealing the heavy cost of the company's ongoing transformation.
The numbers tell a story of growth and severe margin pressure. Revenue for Q4 FY26 jumped 116.5% year-on-year to ₹1.71 crore. Sequentially, it was up 78.1% from the September quarter. In stark contrast, net profit fell 37.5% YoY to just ₹0.05 crore, flat from the previous quarter. The net profit margin was crushed, falling 720 basis points from a year ago to just 2.9%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.83
- Revenue (₹ Cr), Q2 FY25: 0.67
- Revenue (₹ Cr), Q4 FY25: 0.79
- Revenue (₹ Cr), Q2 FY26: 0.96
- Revenue (₹ Cr), Q4 FY26: 1.71
- Profit (₹ Cr), Q4 FY24: 0.19
- Profit (₹ Cr), Q2 FY25: 0.37
- Profit (₹ Cr), Q4 FY25: 0.08
- Profit (₹ Cr), Q2 FY26: 0.05
- Profit (₹ Cr), Q4 FY26: 0.05
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 0.83
- Revenue (₹ Cr), Q2 FY25: 0.67
- Revenue (₹ Cr), Q4 FY25: 0.79
- Revenue (₹ Cr), Q2 FY26: 0.96
- Revenue (₹ Cr), Q4 FY26: 1.71
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.19
- Profit (₹ Cr), Q2 FY25: 0.37
- Profit (₹ Cr), Q4 FY25: 0.08
- Profit (₹ Cr), Q2 FY26: 0.05
- Profit (₹ Cr), Q4 FY26: 0.05
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: 22.9
- Net Profit Margin (%), Q2 FY25: 55.2
- Net Profit Margin (%), Q4 FY25: 10.1
- Net Profit Margin (%), Q2 FY26: 5.2
- Net Profit Margin (%), Q4 FY26: 2.9
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 1.71YoY +116% | 0.79 |
| Profit (₹ Cr) | 0.05YoY -37% | 0.08 |
| Net Profit Margin (%) | 2.9YoY -71% | 10.1 |
The costs that ate the profit
Two line items explain the profit squeeze. Interest expense, which was zero in Q4 FY25, surged to ₹0.19 crore this quarter. Depreciation more than tripled year-on-year to an identical ₹0.19 crore. According to The Economic Times, the company spent over 10% of its operating revenue on interest costs for the full year.
This cost surge is directly linked to the company's renovation and expansion plan for its sole property, Hotel Alexander in Matheran. Reports from Kotak Neo indicate the company embarked on a structured programme in 2026 to reinstate full lodging and boarding services. The sharp rise in depreciation suggests new assets were capitalized, while the interest points to funding this capex.
A weak start to the new year
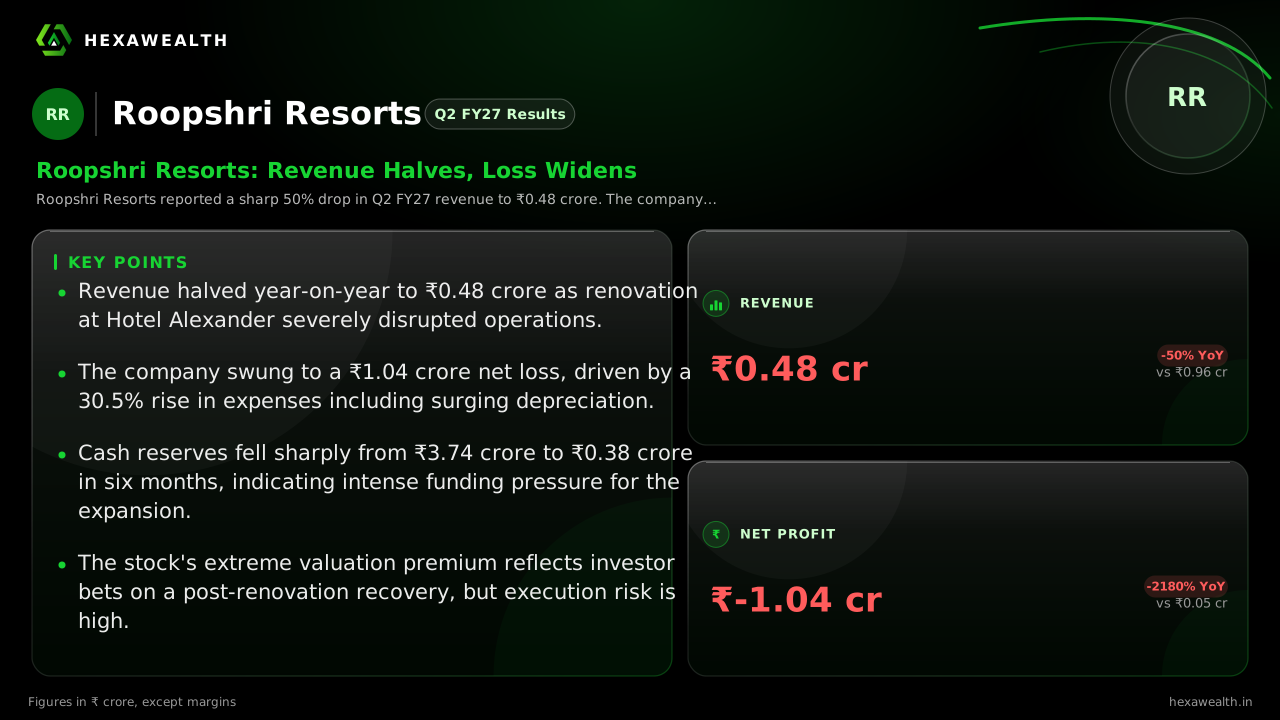
The outlook has already darkened. Research from MarketsMojo and filings show Roopshri Resorts began FY27 with a standalone net loss of ₹1.04 crore for the half-year ended September 2026. Revenue fell and expenses rose sharply, indicating the margin pressure from the renovation phase is intensifying.
Live Chart
· ROOPSHRI
(BSE)
ISIN: INE03WT01017
This comes despite a supportive industry backdrop. An ICRA report cited by IANS Live projects the domestic hospitality industry to grow 9-12% in FY26, with premium hotel occupancy holding firm. Roopshri's struggle is company-specific, tied to its upgrade cycle.
Key Points
- Revenue for Q4 FY26 more than doubled year-on-year to ₹1.71 crore, but net profit fell 37.5% to ₹0.05 crore.
- Profitability was severely hit by a surge in interest and depreciation expenses, which together totaled ₹0.38 crore for the quarter.
- The company started FY27 with a net loss of ₹1.04 crore for H1, signaling continued earnings pressure from its renovation project.
- The stock trades at a significant premium, with a P/E of 578.6 against an industry average of 45.4, as per the latest valuation data.
Hexa Perspective
The quarter underscores a classic investment phase dilemma. Roopshri Resorts is spending to upgrade its asset, which explains the stellar revenue growth but also the profit collapse. The critical question is when these costs will stabilize and the expanded capacity will start earning.
The weak H1 FY27 results suggest this pain has at least another quarter to run. Investors are paying a steep premium for future earnings that are not yet visible, making the stock highly sensitive to any delays or cost overruns in the renovation timeline.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.