Workmates Core2Cloud (WORKMATES) Q2 FY27 Profit Jumps 32% as Recurring Revenue Hits 87%
The cloud services provider posted a 27.5% rise in H1 FY27 revenue, with profit growth outpacing sales as its business model shifts decisively toward recurring contracts.
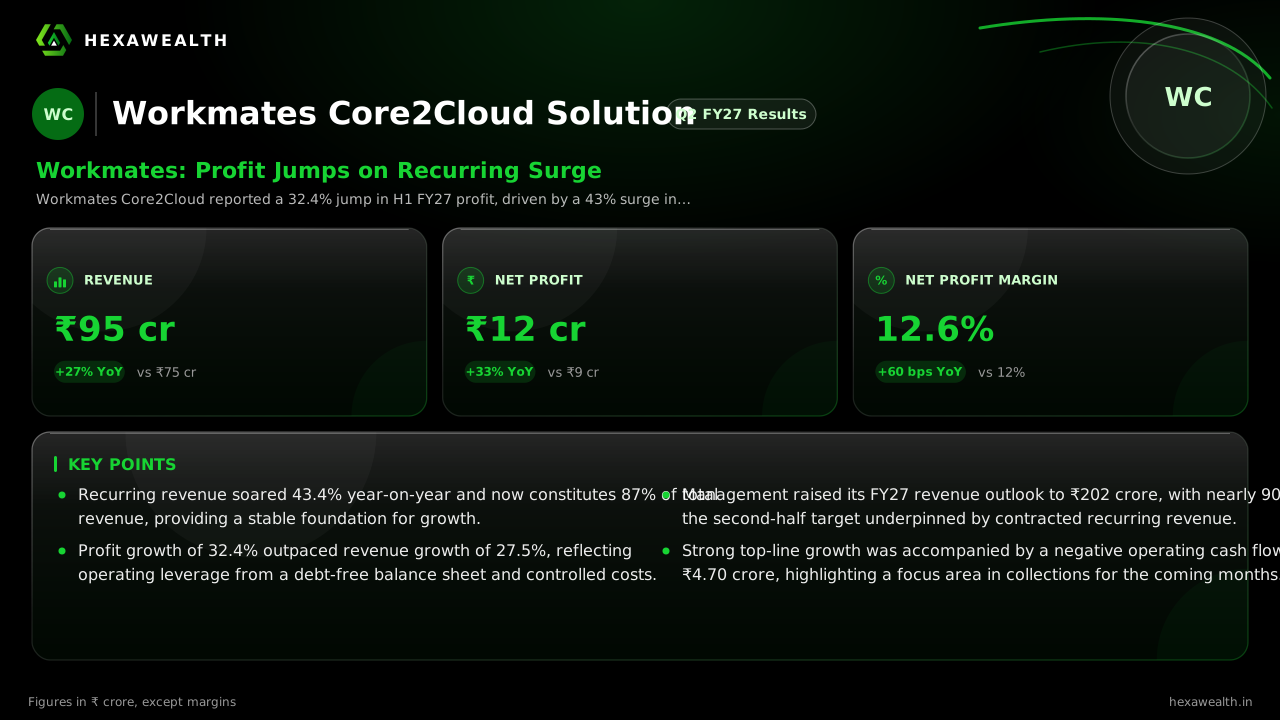
Workmates Core2Cloud reported a 32.4% jump in H1 FY27 profit, driven by a 43% surge in recurring revenue. Management raised its full-year revenue outlook, though cash flow turned negative as receivables grew.
For a cloud services firm like Workmates Core2Cloud, the shift from one-off projects to predictable, repeating income is the ultimate test of stability. Its latest half-year shows that transition accelerating, with recurring revenue now forming the overwhelming core of its business, driving profit growth ahead of sales.
The numbers tell a story of top-line strength and improving profitability. Consolidated revenue for H1 FY27 (April-September 2026) grew 27.5% year-on-year to ₹95.21 crore. Profit after tax rose even faster, climbing 32.4% to ₹12.03 crore. This pushed the net profit margin to 12.6%, a 60 basis point improvement from the same period last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentSep 2026 (H1 FY27) | PreviousMar 2026 (H2 FY26) |
|---|---|---|
| Revenue (₹ Cr) | 95.0 | 69.0 |
| Profit (₹ Cr) | 12.0 | 7.0 |
| Net Profit Margin (%) | 12.6 | 10.1 |
The Recurring Engine Revs Up
The standout driver was a 43.4% surge in recurring revenue to ₹82.97 crore, according to a Multibagg.ai report. Its share of total revenue jumped to 87% from 77% a year ago. This annuity-like growth, primarily from expansion within existing clients, provided a stable base that allowed profit to outpace revenue.
Operating leverage played a key role, as controlled employee costs and the absence of finance costs after becoming debt-free helped margins. However, the Stockwatch.live analysis noted that cost of cloud services grew slightly faster than revenue, preventing broader margin expansion.
A Raised Outlook and a Cash Flow Catch
Buoyed by this performance, management raised its FY27 revenue outlook to ₹202 crore from ₹190.56 crore, as reported by Multibagg.ai. The new target assumes ₹107 crore in second-half revenue, with ₹95.4 crore already contracted from recurring streams.
Yet, the growth came with a working capital trade-off. Operating cash flow turned negative ₹4.70 crore as trade receivables swelled to ₹39.50 crore. Management has identified improving collections as a priority for the coming half.
The Pipeline for What's Next
Visibility for the remainder of the year appears strong. The company holds a weighted pipeline of ₹110 crore for H2 FY27, as per Multibagg.ai, including cloud migration and cybersecurity opportunities. Two orders announced after the half-year close—an ₹11.5 crore migration deal and a multi-million dollar AWS contract—will contribute to this future conversion.
Key Points
- Recurring revenue soared 43.4% year-on-year and now constitutes 87% of total revenue, providing a stable foundation for growth.
- Profit growth of 32.4% outpaced revenue growth of 27.5%, reflecting operating leverage from a debt-free balance sheet and controlled costs.
- Management raised its FY27 revenue outlook to ₹202 crore, with nearly 90% of the second-half target underpinned by contracted recurring revenue.
- Strong top-line growth was accompanied by a negative operating cash flow of ₹4.70 crore, highlighting a focus area in collections for the coming months.
Hexa Perspective
The quarter solidifies Workmates' transition toward a high-recurrence model, which should dampen earnings volatility. The raised guidance is credible, anchored by contracted revenue, but its delivery hinges on converting a visible pipeline while managing receivables.
The margin story is nuanced. Profitability improved, but pressure from cloud service costs—a pass-through expense—limits upside. The company's premium valuation, at a P/E of 34.8 against an industry average of 19.0, prices in its growth trajectory and assumes successful execution on both conversion and collections in the second half.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.