Vishnusurya Projects (VISHNUINFR) Q2 FY27 Profit Crashes 87% as Revenue Drops 42%
The infrastructure firm saw a severe contraction in margins as project deferrals and a shrinking order book weighed on its September quarter performance.
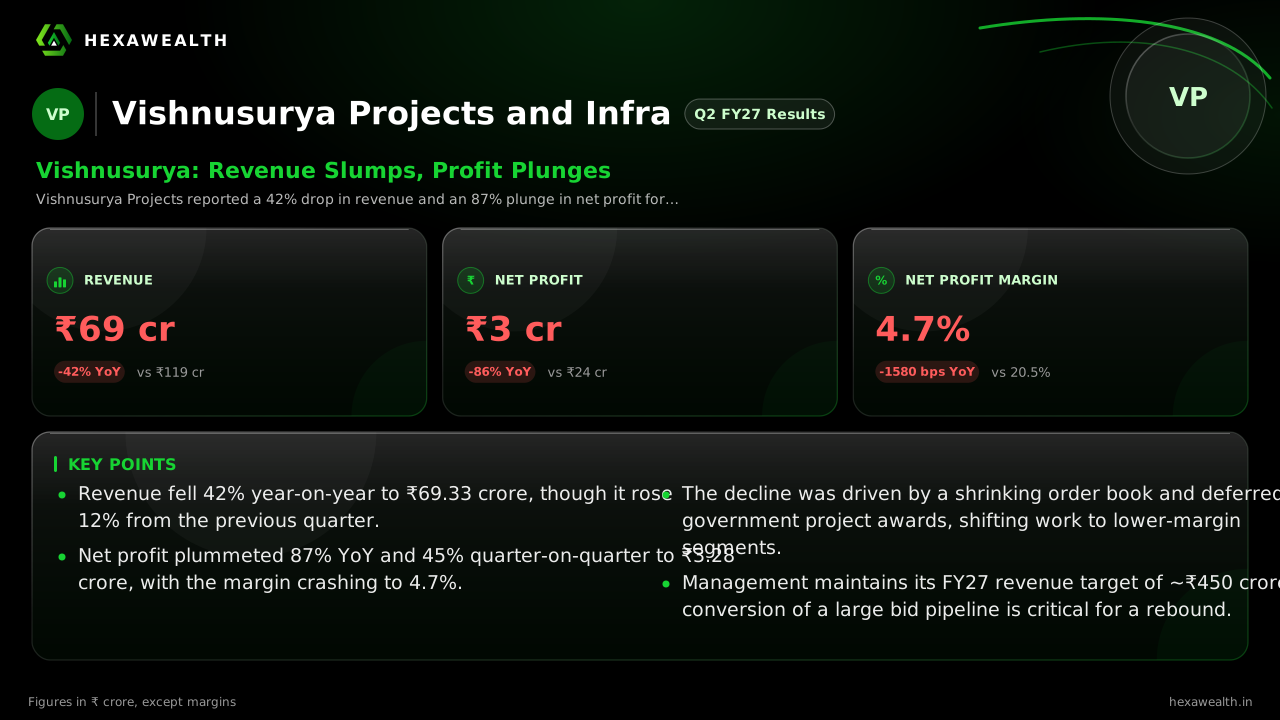
Vishnusurya Projects reported a 42% drop in revenue and an 87% plunge in net profit for Q2 FY27. Margins collapsed from 20.5% to 4.7%, driven by deferred government awards and a higher share of low-margin work.
For a company building its future on government water projects and owned quarries, the September quarter was a stark reminder of how quickly that work can stall. Vishnusurya Projects and Infra reported a severe double-digit decline, with revenue down 42% and profit crashing 87% from a year earlier.
The numbers show a business under pressure from all sides. While revenue ticked up 12% from the June quarter, profit fell another 45% sequentially. The net profit margin collapsed to 4.7%, a drop of 1,580 basis points from the 20.5% it held a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 69.33 | 61.87 |
| Profit (₹ Cr) | 3.28 | 5.92 |
| Net Profit Margin | 4.7% | 9.6% |
Why the bottom line fell apart
A shrinking order book and deferred project awards are at the heart of the slump. According to a Newboard.in report, the order book fell from ₹455.6 crore in March to ₹358.0 crore by June 2026. Management cited deferred awards and fund releases from government clients.
This shortage of high-value work shifted the revenue mix. The company's asset-backed quarry business, which earns higher margins, likely contributed less. Meanwhile, total expenses rose 19% quarter-on-quarter, with employee costs up 17%, squeezing an already weakened top line.
The long road to recovery
Management has not abandoned its full-year target of about ₹450 crore in revenue. Its roadmap, noted in a June earnings call, still aims for ₹180-190 crore from quarries and expects half its new orders to come via partner JWIL Infra.
However, the near-term outlook is clouded. The broader construction sector saw margins compress in Q2, with a FlashFinance analysis showing a 43-basis-point decline across 124 companies. For Vishnusurya, recovery hinges on converting its pending ₹263.9 crore bid pipeline into firm orders.
Key Points
- Revenue fell 42% year-on-year to ₹69.33 crore, though it rose 12% from the previous quarter.
- Net profit plummeted 87% YoY and 45% quarter-on-quarter to ₹3.28 crore, with the margin crashing to 4.7%.
- The decline was driven by a shrinking order book and deferred government project awards, shifting work to lower-margin segments.
- Management maintains its FY27 revenue target of ~₹450 crore, but conversion of a large bid pipeline is critical for a rebound.
Hexa Perspective
This quarter reveals the operational fragility that comes with high dependence on government infrastructure cycles. The 1,580-basis-point margin collapse is severe, moving the trailing-twelve-month margin to 6.7%, well below the FY26 full-year level of 10.1%.
The stock's valuation at a 60% discount to the industry P/E reflects this risk. Investors are weighing the promised order inflow against a demonstrated slowdown. The next few quarters will test whether management's guidance is a plan or a hope, as execution must now catch up to ambition.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.