Swan Corp (SWANCORP) Q2 FY27's Q2 Profit Surges on a One-Off Tax Windfall
A ₹558 crore tax credit from a subsidiary merger drove the quarterly profit, while underlying operations showed a modest improvement and core revenue declined.
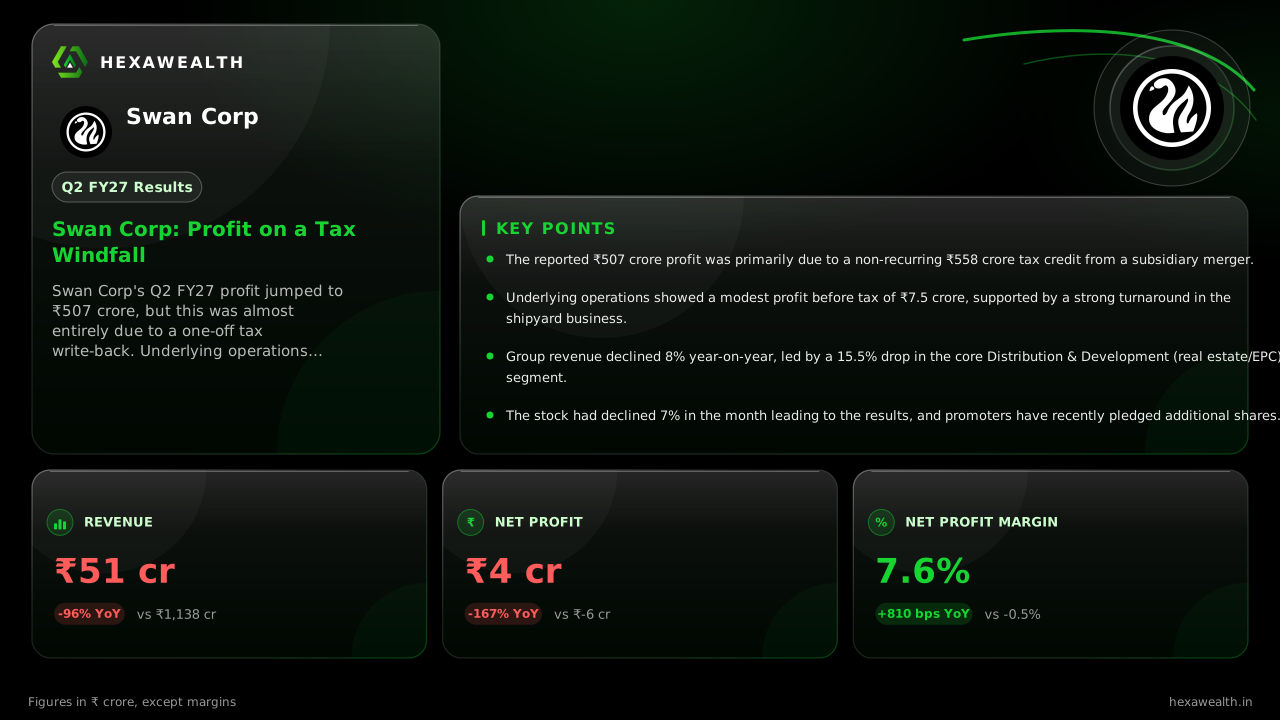
Swan Corp's Q2 FY27 profit jumped to ₹507 crore, but this was almost entirely due to a one-off tax write-back. Underlying operations remained weak, with consolidated revenue falling 8% year-on-year.
For Swan Corp, a diversified group spanning textiles, real estate, and shipbuilding, the September quarter delivered a headline that was almost too good to be true. The reported net profit of ₹507 crore, a massive swing from last year's loss, was driven by a one-off event that overshadowed the underlying business trends.
The scorecard reveals a stark divergence. While consolidated profit before tax was a modest ₹7.5 crore, a tax credit of ₹558 crore propelled the bottom line. This credit, as reported by Stockwatch, stemmed from a tax reassessment after the merger of Triumph Offshore into subsidiary Swan Defence and Heavy Industries (SDHI).
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 51.05YoY -96% | 1013.75 | 1138.34 |
| Profit (₹ Cr) | 3.9YoY +167% | -35.99 | -5.86 |
| Net Profit Margin (%) | 7.6YoY +1620% | -3.6 | -0.5 |
Note: Table shows standalone (parent-only) financials.
The Real Story Behind the Headline
Strip away the tax windfall, and the operating picture is mixed. The shipyard segment, housed within SDHI, was a bright spot. Stockwatch notes it swung to a ₹29.4 crore profit as revenue surged 74% year-on-year.
This improvement, however, was largely absorbed by group finance costs of ₹31.3 crore. Meanwhile, the Distribution & Development segment, which constitutes the bulk of group revenue, saw sales decline 15.5%.
A Cautious Market and Promoter Moves
The market appeared to see through the one-off gain. The stock entered the results period at ₹244.59, down 7% over the prior month according to Stockwatch. No verifiable analyst consensus or management commentary was available to frame expectations.
Separately, the promoter group encumbered an additional 9.57% stake in early November. This follows a pledge in October, adding context to the group's leverage dynamics outside the reported quarter.
Key Points
- The reported ₹507 crore profit was primarily due to a non-recurring ₹558 crore tax credit from a subsidiary merger.
- Underlying operations showed a modest profit before tax of ₹7.5 crore, supported by a strong turnaround in the shipyard business.
- Group revenue declined 8% year-on-year, led by a 15.5% drop in the core Distribution & Development (real estate/EPC) segment.
- The stock had declined 7% in the month leading to the results, and promoters have recently pledged additional shares.
Hexa Perspective
The quarter presents a clear case of headline numbers diverging from operational reality. The tax write-back provides a one-time boost to the balance sheet but does not reflect sustainable earnings power.
The shipyard's performance is encouraging and offers a potential growth vector, yet its contribution is still dwarfed by the larger, struggling real estate segment. Investors are left weighing a promising niche turnaround against persistent weakness in the core business, with promoter pledging activity adding another layer of caution. The sustainability of profits will depend entirely on the shipyard's momentum and a recovery in real estate execution.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.