Excel Industries (EXCELINDUS) Q2 FY27 Profit Jumps 36% Despite Stagnant Sales
Excel Industries posted a 36.4% surge in quarterly net profit, but revenue grew just 1.6% as cost control and a jump in other income drove earnings.
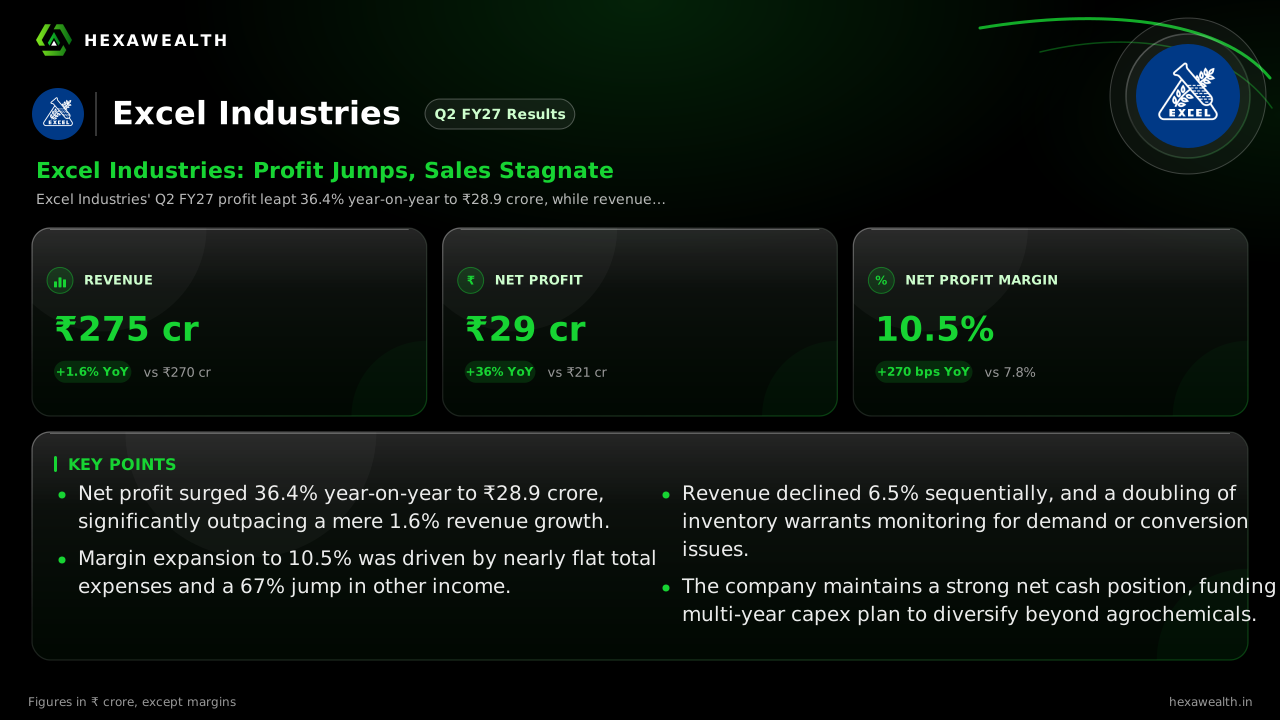
Excel Industries' Q2 FY27 profit leapt 36.4% year-on-year to ₹28.9 crore, while revenue grew a modest 1.6%. The margin expansion was fueled by flat expenses and a sharp rise in other income, though sales declined sequentially.
For a chemical maker, a quarter where profit grows 22 times faster than sales is a story of margin discipline, not market momentum. Excel Industries delivered exactly that, with net profit surging 36.4% on a meager 1.6% revenue increase, as flat expenses and a jump in other income lifted the bottom line.
The numbers show a business holding its ground on profitability while sales tread water. Consolidated revenue was ₹274.68 crore, barely changed from last year's ₹270.23 crore. Yet, net profit climbed to ₹28.9 crore, pushing the net profit margin up 270 basis points to 10.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 274.68YoY +1.6% | 293.83 | 270.23 |
| Profit (₹ Cr) | 28.90YoY +36% | 29.47 | 21.19 |
| Net Profit Margin | 10.5%YoY +35% | 10.0% | 7.8% |
The margin engine behind flat sales
Profit soared because total expenses were nearly flat year-on-year at ₹249.34 crore, as reported by scanx.trade. This tight cost control, alongside a 67% surge in other income to ₹12.44 crore, created the earnings leverage. The core operating story, however, was softer, with revenue declining 6.5% from the previous quarter.
A key feature was a significant inventory build-up, which doubled since March 2026 to over ₹262 crore according to scanx.trade. This suggests strategic stocking or potential delays in sales conversion, a point management will likely address in its scheduled earnings call on November 6.
A muted market and a cautious path forward
The broader agrochemical environment offers little tailwind. A Jefferies report cited by Chinimandi notes global crop protection demand remained weak in the September quarter despite rising crop prices. This aligns with Excel's stagnant top line and the industry-wide pressure seen in peers' results.
The company's strength is a robust, near debt-free balance sheet that supports its growth plans. Investor presentations reviewed by Arthneeti outline a ₹200-300 crore capex plan over three years for capacity expansion and new products like Phosphorus Pentasulphide.
Key Points
- Net profit surged 36.4% year-on-year to ₹28.9 crore, significantly outpacing a mere 1.6% revenue growth.
- Margin expansion to 10.5% was driven by nearly flat total expenses and a 67% jump in other income.
- Revenue declined 6.5% sequentially, and a doubling of inventory warrants monitoring for demand or conversion issues.
- The company maintains a strong net cash position, funding a multi-year capex plan to diversify beyond agrochemicals.
Hexa Perspective
The quarter presents a clear dichotomy: excellent profit conversion on stagnant sales. The sustainability of this earnings quality hinges on whether the cost control is structural and if the other income boost is repeatable.
With agrochemical demand soft globally, the planned capex into specialty chemicals is a prudent diversification. Investors are left weighing robust profitability and a strong balance sheet against a top line that has yet to find a durable growth catalyst in a challenging market.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.