Asian Star (ASTAR) Q2 FY27 Profit Grows 24% Even as Revenue Shrinks 21%
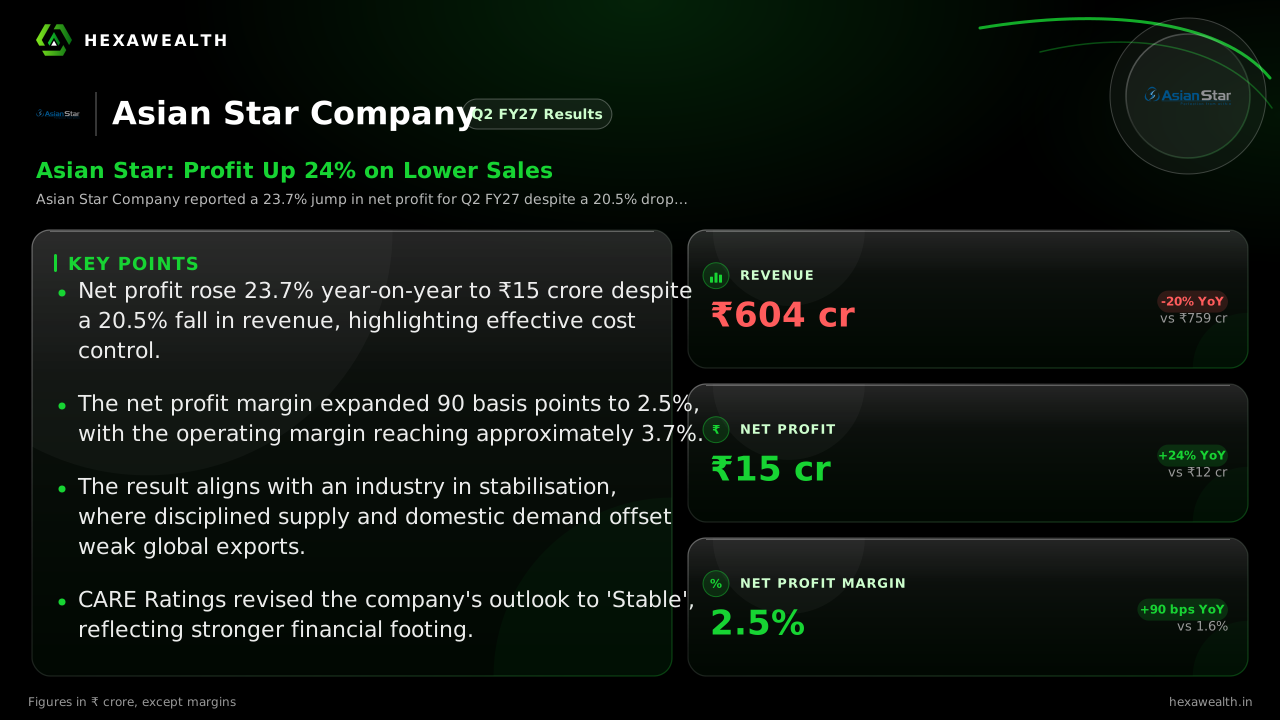
The jewellery maker's profit rose 23.7% year-on-year to ₹15 crore in Q2 FY27, but revenue fell 20.5% as the company focused on cost control.
Asian Star Company reported a 23.7% jump in net profit for Q2 FY27 despite a 20.5% drop in revenue. The quarter was defined by disciplined cost-cutting, which sharply lifted margins, as the broader diamond industry stabilises.
For a vertically integrated diamond and jewellery player, the quarter was a study in disciplined restraint. Asian Star delivered a 23.7% jump in net profit even as its top line contracted by a fifth, a result of sharp cost management in a market choosing value over volume.
The numbers show a clear trade-off. Revenue for the September quarter was ₹604 crore, down 20.5% from a year ago and 5.4% sequentially. Yet net profit climbed to ₹15 crore, with the net profit margin expanding 90 basis points year-on-year to 2.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 604.0YoY -20% | 638.31 | 759.4 |
| Profit (₹ Cr) | 15.0YoY +24% | 12.06 | 12.13 |
| Net Profit Margin (%) | 2.5YoY +56% | 1.9 | 1.6 |
The Cost-Cut That Lifted Profit
The profit growth was entirely driven by a tighter grip on expenses. Total expenditure fell 19.6% year-on-year, slightly outpacing the revenue decline. According to a summary by Perivis, the operating margin improved to approximately 3.7%, up from 2.9% a year earlier.
This squeeze came as the company navigated a bifurcated market. A Crisil Ratings analysis cited in The Economic Times notes lab-grown diamonds are reshaping entry-level demand, while natural stones retain premium appeal. Asian Star’s focus on cost likely reflects this pressure on volume-led segments.
A Market in Stabilisation, Not Recovery
The revenue decline aligns with an industry finding its floor, not a rebound. The same Crisil report projects India's natural diamond industry revenue to stay flat this fiscal, around $15 billion. Domestic demand is cushioning weak exports, particularly to the US and China.
For Asian Star, this means the current strategy of margin defence over sales growth may persist. The company’s recent credit rating outlook was revised from 'Negative' to 'Stable' by CARE Ratings, as noted by Groww, signalling improved financial stability.
Key Points
- Net profit rose 23.7% year-on-year to ₹15 crore despite a 20.5% fall in revenue, highlighting effective cost control.
- The net profit margin expanded 90 basis points to 2.5%, with the operating margin reaching approximately 3.7%.
- The result aligns with an industry in stabilisation, where disciplined supply and domestic demand offset weak global exports.
- CARE Ratings revised the company's outlook to 'Stable', reflecting stronger financial footing.
Hexa Perspective
The quarter shows Asian Star prioritising profitability in a muted market. The margin expansion is a clear positive, but its sustainability hinges on maintaining this cost discipline if revenue remains under pressure.
Investors are weighing a leaner, more efficient operation against the top-line shrinkage. With the stock trading at a significant discount to the industry PE, the market appears to be pricing in the challenges of volume growth more than the promise of margin improvement.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.