Steelco Gujarat (STEELCO) Q2 FY27 Profit Squeeze Deepens Despite 331% Revenue Surge
The steel processor's Q2 FY27 sales jumped over threefold year-on-year, but a crushing interest burden pushed its net loss wider and its net worth into negative territory.
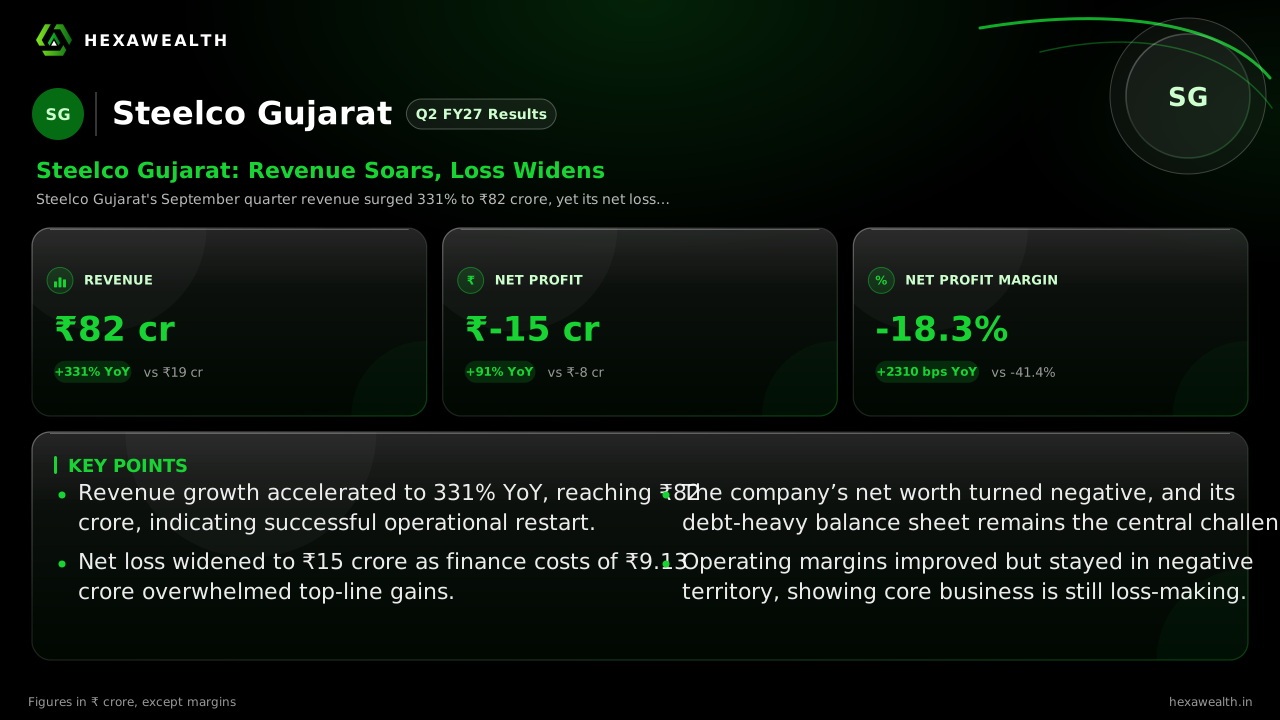
Steelco Gujarat's September quarter revenue surged 331% to ₹82 crore, yet its net loss widened to ₹15 crore. The company's net worth turned negative as high finance costs consumed the gains from its post-insolvency revival.
For a company restarting after insolvency, the first test is rebuilding sales. Steelco Gujarat passed that in the September quarter, with revenue tripling from a low base. The second test is turning that top line into profit, and there the company’s finance costs proved an immovable wall.
Revenue for the quarter ended September 2026 was ₹82 crore, up 331% from a year ago and 57% from the June quarter. The net loss, however, widened to ₹15 crore from ₹7.87 crore a year earlier and was essentially flat sequentially. The net profit margin improved on paper to -18.3% from -41.4% last year, but that reflects a higher revenue base, not operating profit.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 82.0YoY +331% | 52.18 | 19.02 |
| Profit (₹ Cr) | -15.0YoY -91% | -14.98 | -7.87 |
| Net Profit Margin (%) | -18.3YoY +56% | -28.7 | -41.4 |
The interest burden that ate the gains
The story is in the costs. According to a report from ScanX, finance costs surged to ₹9.13 crore, up 343% year-on-year and consuming over 11% of the quarter’s revenue. This heavy debt load, raised to fund the company’s revival, meant that every rupee of new sales was largely offset by interest expense. Total expenses climbed 262% to ₹97.75 crore.
The company’s balance sheet health deteriorated alongside the loss. ScanX noted that net worth turned negative at ₹12.39 crore as of September 30, down from a positive ₹2.72 crore at the end of FY26. The debt-to-equity ratio, a key solvency metric, swung to 18.31.
A revival still searching for leverage
Management has focused on restarting its single plant in Gujarat and rebuilding operations after its Corporate Insolvency Resolution Process (CIRP). The revenue jump shows commercial activity has resumed. A report from Flash Finance noted the operating margin improved by 1,949 basis points year-on-year, though it remained negative at -6.8%.
Yet, the path to profitability is blocked by the capital structure chosen for the turnaround. The company raised ₹140 crore via secured NCDs in January 2026, carrying an internal rate of return of 21.90% per annum, as per its annual report. A subsequent rights issue raised about ₹149 crore, but proceeds were directed to working capital, not debt reduction.
Key Points
- Revenue growth accelerated to 331% YoY, reaching ₹82 crore, indicating successful operational restart.
- Net loss widened to ₹15 crore as finance costs of ₹9.13 crore overwhelmed top-line gains.
- The company’s net worth turned negative, and its debt-heavy balance sheet remains the central challenge.
- Operating margins improved but stayed in negative territory, showing core business is still loss-making.
Hexa Perspective
Steelco Gujarat’s quarter is a stark lesson in capital structure. The company has demonstrably reignited its revenue engine, but the cost of its revival debt is now the defining constraint. Profitability hinges entirely on whether operating earnings can grow fast enough to outrun a 22% annual interest burden before equity is fully eroded. The market, which has seen the stock rise over 550% in the past year, is pricing a successful turnaround. These results show that turnaround is underway but far from complete, with the heaviest lift—de-leveraging—still ahead.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.