South West Pinnacle (SOUTHWEST) Q2 FY27 Profit Plunges 52% as Costs Overwhelm Revenue
South West Pinnacle Exploration saw its Q2 FY27 net profit fall by more than half, as a sharp rise in employee and depreciation costs squeezed margins.
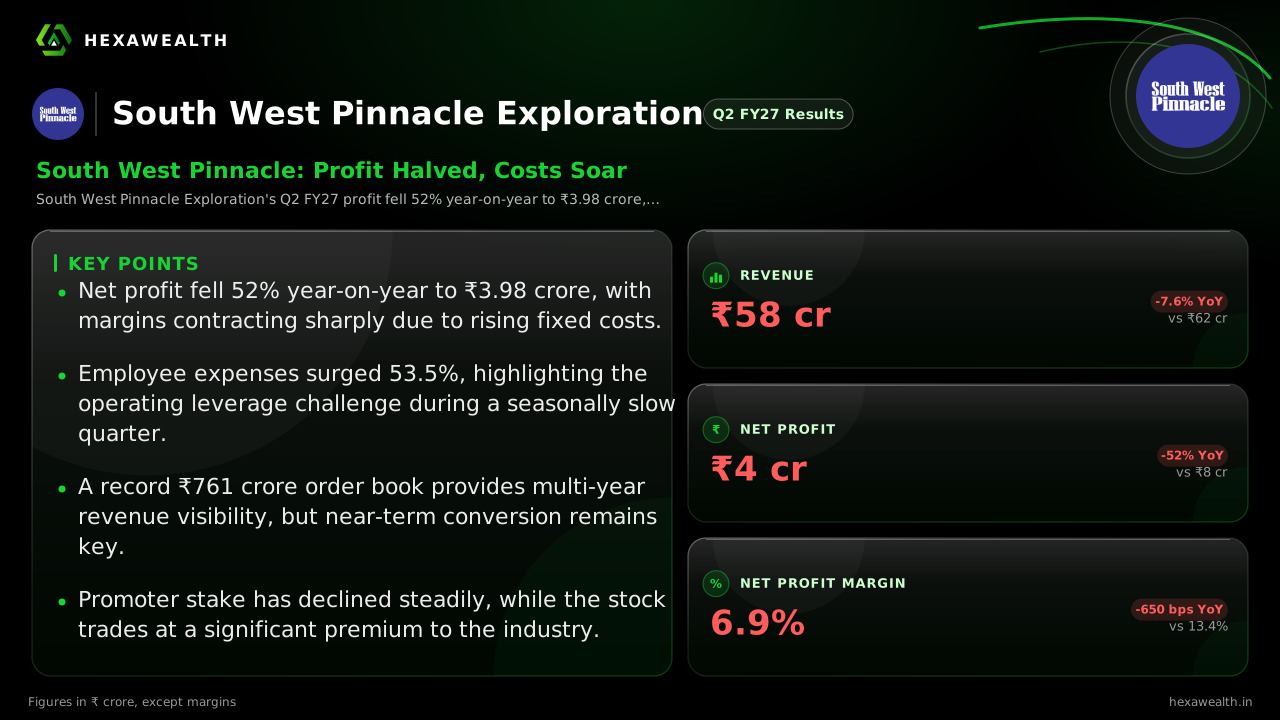
South West Pinnacle Exploration's Q2 FY27 profit fell 52% year-on-year to ₹3.98 crore, despite a record order book. A surge in employee costs and seasonal execution slowdowns led to a significant margin contraction.
For a company sitting on a record ₹761 crore order book, South West Pinnacle Exploration's September quarter was a reminder that execution trumps backlog. Revenue and profit fell both sequentially and from a year ago, as costs grew faster than the work completed.
The numbers show a clear squeeze. Revenue for Q2 FY27 was ₹57.73 crore, down 8% from last year and 6% from the previous quarter. Net profit dropped more sharply, falling 52% year-on-year to ₹3.98 crore. The net profit margin contracted to 6.9%, down 820 basis points from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 57.73 | 61.68 |
| Profit (₹ Cr) | 3.98 | 9.34 |
| Net Profit Margin (%) | 6.9 | 15.1 |
The Cost Squeeze That Erased Profits
The primary driver of the profit plunge was a surge in operating expenses. Employee benefit costs jumped 53.5% year-on-year to ₹13.18 crore. Depreciation also rose 18% as the company invested in its rig fleet.
These fixed costs became a heavier burden as revenue softened. Reports from Sahi.com and StockFin.ai note that monsoon seasonality typically reduces drilling days by 20-30% in the first half of the year, impacting execution. The cost structure did not flex down with the lower activity.
A Full Pipeline Awaits Better Execution
The company's long-term story remains anchored in its massive order book, which stood at ₹761 crore at the end of Q1. Key projects include a ₹307 crore order from Hindustan Zinc and a ₹167 crore extension of its Coal Bed Methane contract with Reliance Industries.
Management, according to a report by Multibagg.ai, is finalising the mining plan for its Jharkhand coal block, targeting production by FY28-29. The Oman copper-gold joint venture also awaits a geological report. These are future catalysts, but contributed no revenue this quarter.
The Market's Cautious Stance
The stock has returned 6.7% over the past year, slightly lagging the broader market's momentum. Promoter stake has gradually declined over recent quarters, falling to 61.7% in Q2 FY27 from 68.8% a year prior, as noted by StockFin.ai.
This reduction, alongside a price-to-earnings ratio of 19.1—more than double the industry average—suggests the market is weighing the rich valuation against near-term execution challenges. The company held an investor call on November 11 to discuss the half-year results.
Key Points
- Net profit fell 52% year-on-year to ₹3.98 crore, with margins contracting sharply due to rising fixed costs.
- Employee expenses surged 53.5%, highlighting the operating leverage challenge during a seasonally slow quarter.
- A record ₹761 crore order book provides multi-year revenue visibility, but near-term conversion remains key.
- Promoter stake has declined steadily, while the stock trades at a significant premium to the industry.
Hexa Perspective
The quarter underscores the operational gearing inherent in a contract drilling business. Costs are sticky, making profitability highly sensitive to revenue run-rates. The record order book is a solid foundation, but investors are now watching for two things.
First, a pick-up in execution speed in the seasonally stronger second half to absorb the high fixed-cost base. Second, tangible progress on the Jharkhand coal block and Oman JV, which are critical for diversifying revenue beyond cyclical drilling services. Until then, margins may remain under pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.