SIS Q2 FY27 Profit Jumps 37% on Record Revenue, But Costs and Cash Flow Pinch
SIS posted its highest-ever quarterly revenue and profit in Q2 FY27, but rising employee costs and a temporary cash flow squeeze highlight ongoing challenges.
SIS delivered record quarterly revenue of ₹4,816 crore in Q2 FY27, with profit jumping 37% year-on-year. Growth was led by its India security business, though margin expansion remains a battle against wage inflation and higher interest costs.
For SIS, a business built on deploying hundreds of thousands of security and facility management personnel, growth hinges on winning large contracts and passing through mandated wage hikes. The September quarter delivered on both fronts, setting new records but also revealing the persistent cost pressures of this model.
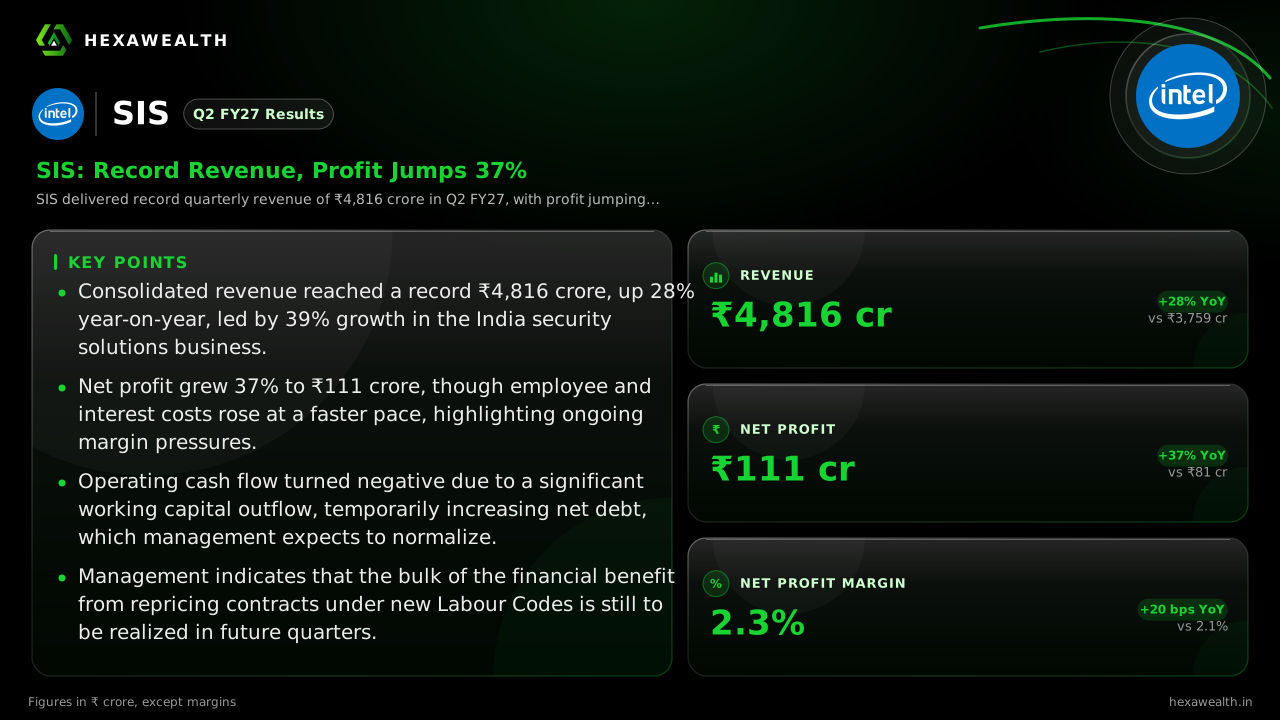
Revenue rose 28% year-on-year to ₹4,816 crore, while net profit grew faster at 37% to ₹111 crore. The net profit margin inched up to 2.3%. This performance extends a steady growth trend over the past year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4,816.01YoY +28% | 4,603.58 | 3,758.52 |
| Profit (₹ Cr) | 110.72YoY +37% | 101.66 | 80.73 |
| Net Profit Margin | 2.3%YoY +9.5% | 2.2% | 2.1% |
The India engine fires on all cylinders
The surge was powered by the domestic security business, which grew 39% year-on-year. According to a PTI report, major new client wins came from e-commerce, metals & mining, and IT sectors. The facility management segment also posted a record profit with its margin hitting a six-year high of 5.7%, as noted in the company's earnings call.
Management says the recent Labour Code changes are a key tailwind. Higher wage and statutory costs are being passed through to customers, lifting both revenue and margins. The AlphaStreet transcript quotes the CEO stating the “major chunk of the Labour Code repricing benefit is still ahead of us.”
Costs rise faster, and cash turns negative
The headline profit growth masks a squeeze underneath. Employee costs, which make up 85% of revenue, grew 29% year-on-year, slightly outpacing sales. Interest expense surged 60%, which Multibagg.ai attributes partly to a new office lease and acquisition-related costs.
More notably, operating cash flow was negative ₹99 crore. Management explained on the earnings call that a ₹273 crore working capital outflow, largely from a delayed payment in the international business, was a temporary timing issue. This pushed net debt to ₹1,026 crore.
A valuation gap persists
Despite the record numbers, the stock trades at a P/E of 28.7, an 18% discount to its industry peers. MarketsMojo maintains a 'Hold' rating, citing concerns over long-term margin sustainability alongside the strong growth. The one-year stock return of 16% has outperformed the broader market.
Key Points
- Consolidated revenue reached a record ₹4,816 crore, up 28% year-on-year, led by 39% growth in the India security solutions business.
- Net profit grew 37% to ₹111 crore, though employee and interest costs rose at a faster pace, highlighting ongoing margin pressures.
- Operating cash flow turned negative due to a significant working capital outflow, temporarily increasing net debt, which management expects to normalize.
- Management indicates that the bulk of the financial benefit from repricing contracts under new Labour Codes is still to be realized in future quarters.
Hexa Perspective
The quarter confirms SIS's revenue momentum in a supportive demand environment. The crucial watchpoint is whether operational discipline and contract repricing can consistently outrun wage inflation to deliver sustained margin improvement.
The cash flow dip appears transient, linked to a specific client payment. However, it underscores the working capital intensity of the model. Investors are weighing strong top-line execution against these profitability and cash conversion challenges, which explains the stock's persistent valuation discount.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.