Shukra Medtech (SHUKRAPHAR) Q2 FY27's Profit Stalls Even as Revenue Jumps 88%
The pharmaceutical company's Q2 FY27 sales surged on MedTech expansion, but a sharp rise in costs kept net profit flat and squeezed margins.
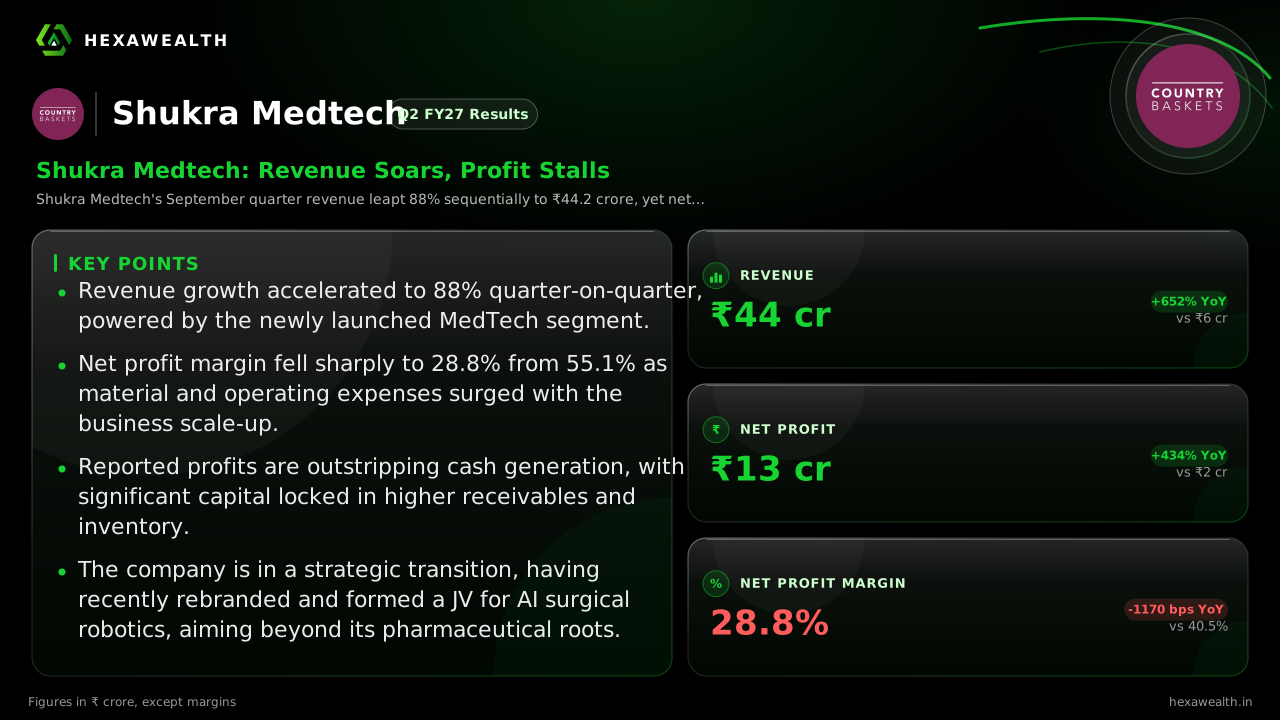
Shukra Medtech's September quarter revenue leapt 88% sequentially to ₹44.2 crore, yet net profit dipped slightly to ₹12.71 crore. The margin squeeze reflects the rapid scaling of its new MedTech segment and higher working capital needs.
Shukra Medtech's transformation from a traditional drugmaker is now hitting the financial statements. The September quarter shows revenue surging on the back of its new medical technology business, but profitability is not keeping pace, revealing the costs of a rapid pivot.
The numbers tell a story of top-line acceleration and margin compression. Consolidated revenue for Q2 FY27 was ₹44.2 crore, an 88% jump from the June quarter and a 652% leap from a low base last year. Net profit, however, was nearly flat at ₹12.71 crore, dipping 1.9% sequentially even as it grew 434% year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 44.2 | 23.52 |
| Profit (₹ Cr) | 12.71 | 12.96 |
| Net Profit Margin | 28.8% | 55.1% |
The MedTech engine is running
Revenue growth was driven by the newly operational MedTech segment. According to Flash Finance, this segment contributed ₹12.51 crore in Q2 revenue, while the core Pharmaceutical business brought in ₹32.27 crore. The company's strategic pivot, including a recent name change and a joint venture for surgical robotics, is beginning to generate sales.
Where the profit went
Despite the revenue jump, net profit margin collapsed to 28.8% from 55.1% last quarter. The primary cause was a 358% sequential surge in total expenses to ₹26.95 crore. Multibagg.ai reported that cost of materials consumed was ₹15.99 crore, a major component of this increase as the company scales operations.
This scaling is also tying up cash. For the half-year, operating cash flow was just ₹1.49 crore against a net profit of over ₹31 crore, as receivables and inventories rose sharply. The earnings are real, but the cash conversion is lagging behind the accounting growth.
A valuation waiting for consistency
The market has rewarded the growth narrative, with the stock up 84% over the past year. It trades at a trailing P/E of 4.8, a steep discount to the industry average of 38.4, according to the payload. No major brokerages have published ratings or targets yet, as noted by Sharpely.in, leaving the stock to be driven by retail sentiment and the unfolding story.
Key Points
- Revenue growth accelerated to 88% quarter-on-quarter, powered by the newly launched MedTech segment.
- Net profit margin fell sharply to 28.8% from 55.1% as material and operating expenses surged with the business scale-up.
- Reported profits are outstripping cash generation, with significant capital locked in higher receivables and inventory.
- The company is in a strategic transition, having recently rebranded and formed a JV for AI surgical robotics, aiming beyond its pharmaceutical roots.
Hexa Perspective
The quarter confirms Shukra Medtech's revenue model is working, but the cost structure of its new business is materially different. The margin squeeze is not a one-off but a feature of this phase, where establishing the MedTech operation carries upfront costs.
The critical watchpoint is working capital. If receivables and inventory continue to grow faster than revenue, the business will require constant external funding despite showing accounting profits. The current low P/E reflects skepticism about the sustainability and quality of these earnings until cash flows catch up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.