Shivam Autotech (SHIVAMAUTO) Q2 FY27's Q2 Loss Deepens Despite a Strong Revenue Rebound
The auto parts maker posted an 18% revenue jump, but a more than doubling of finance costs pushed its net loss wider year-on-year.
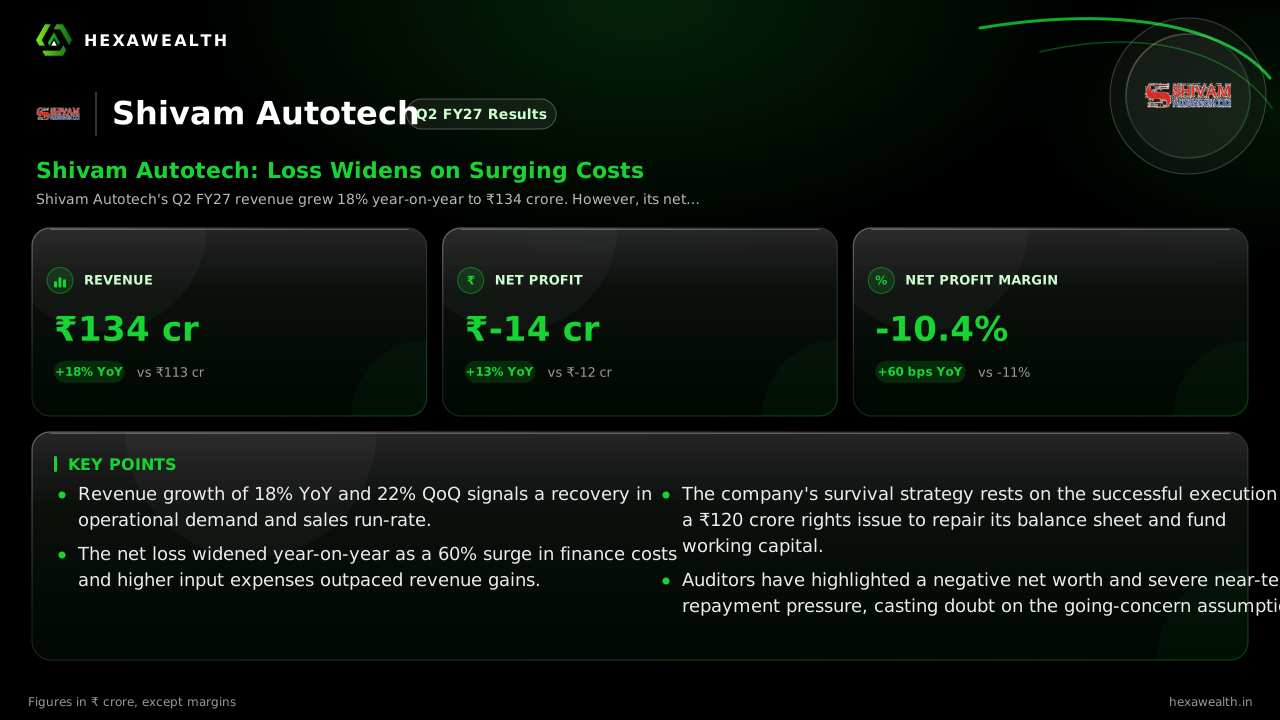
Shivam Autotech's Q2 FY27 revenue grew 18% year-on-year to ₹134 crore. However, its net loss widened to ₹14 crore as surging finance and input costs outpaced sales growth, highlighting persistent balance sheet stress.
For Shivam Autotech, the September quarter was a story of operational recovery colliding with a crushing debt burden. A sharp 22% sequential jump in sales showed demand was not the problem, but the cost of servicing its borrowings more than erased those gains.
The numbers reveal the tension. Revenue reached ₹134 crore, up 18% from a year ago. Yet the net loss widened to ₹14 crore, 13% deeper than the ₹12.4 crore loss in Q2 FY26. The loss did narrow from the previous quarter, but the year-on-year deterioration tells the real story.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 134.0YoY +18% | 109.6 | 113.2 |
| Net Profit (₹ Cr) | -14.0YoY -13% | -21.0 | -12.4 |
| PAT Margin (%) | -10.4YoY +5.5% | -19.2 | -11.0 |
The Debt That Devours Growth
The primary culprit was a 60% year-on-year surge in finance costs to ₹21 crore, as reported by Autocar Professional. This interest expense, which more than doubled from last year, consumed the operating profit generated from higher sales. Material and stores costs also rose, keeping total expenses growing faster than revenue.
This financial strain has pushed the company into negative net worth of over ₹75 crore, as noted by auditors NSBP & Co. in their review. The balance sheet shows a debt-to-equity ratio of 6.9, with a severe liquidity crunch—cash stood at just ₹1.7 crore against current borrowings of ₹310.6 crore at the end of the half-year.
A Lifeline in the Rights Issue
Management's plan to escape this trap hinges on a proposed ₹120 crore rights issue. According to Autocar Professional, ₹75 crore of this will convert promoter debt to equity, aiming to restore positive net worth. The remaining ₹32 crore is earmarked to ease working capital constraints that have crippled plant capacity utilisation.
The company, as noted in its annual report, is also diversifying into industrial and renewable energy components. Yet for now, it remains heavily dependent on the two-wheeler sector, with a single customer accounting for over half its revenue.
Key Points
- Revenue growth of 18% YoY and 22% QoQ signals a recovery in operational demand and sales run-rate.
- The net loss widened year-on-year as a 60% surge in finance costs and higher input expenses outpaced revenue gains.
- The company's survival strategy rests on the successful execution of a ₹120 crore rights issue to repair its balance sheet and fund working capital.
- Auditors have highlighted a negative net worth and severe near-term repayment pressure, casting doubt on the going-concern assumption.
Hexa Perspective
The quarter underscores that Shivam Autotech's operational engine can run, but its financial chassis is broken. The rights issue is a necessary, but not sufficient, condition for a turnaround. Success requires not just raising capital, but also stabilizing customer relationships—some of whom have flagged it as a 'Red Vendor'—and achieving the operating leverage needed to finally cover its debt costs. Investors are weighing a potential equity dilution against the existential risk of inaction.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.