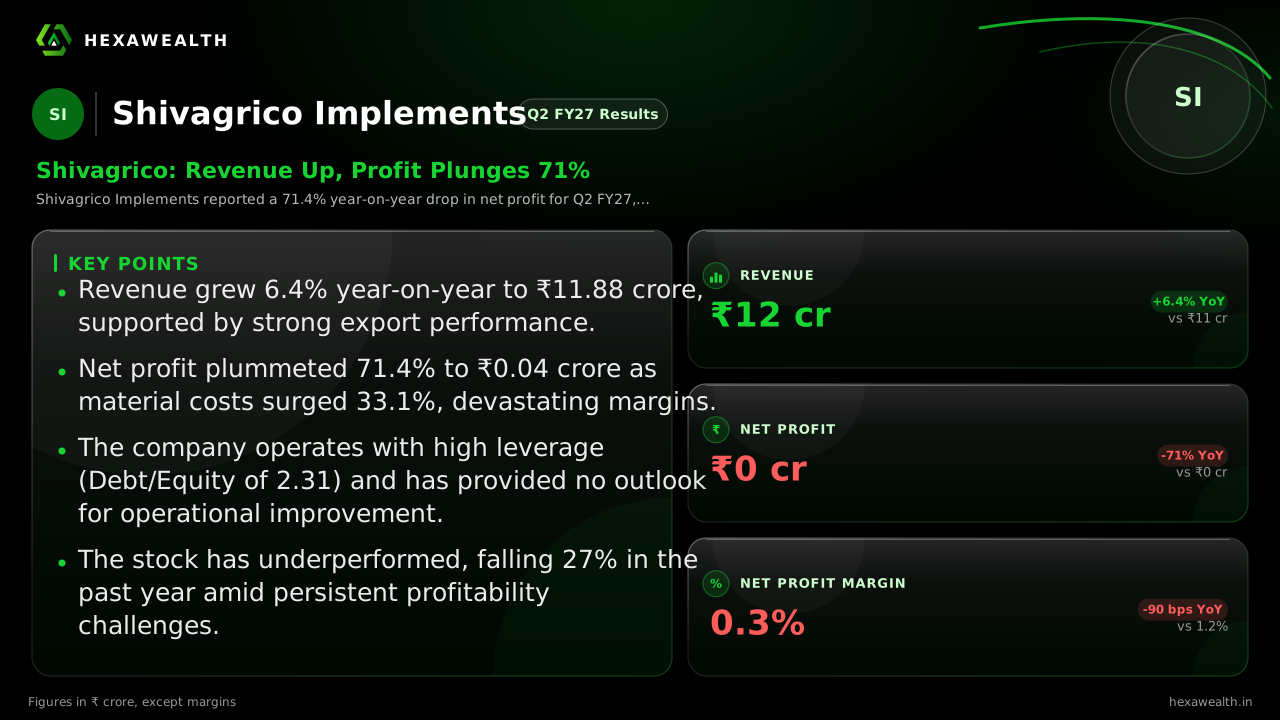
Shivagrico (SHIVAGR) Q2 FY27 Profit Plunges 71% as Material Costs Surge
The agricultural implements maker posted a 6.4% rise in September quarter revenue, but a sharp jump in input costs sent net profit tumbling.
Shivagrico Implements reported a 71.4% year-on-year drop in net profit for Q2 FY27, despite revenue growth of 6.4%. The collapse in profitability was driven by a surge in material costs that far outpaced sales growth.
For Shivagrico Implements, the September quarter was a story of sales growth that never reached the bottom line. The company delivered a modest revenue increase, but a dramatic surge in input costs erased nearly all profitability, highlighting a deep-seated margin challenge.
The numbers show the tension clearly. Revenue for Q2 FY27 stood at ₹11.88 crore, up 6.4% from a year ago and 1.4% from the June quarter. Net profit, however, collapsed to just ₹0.04 crore, a 71.4% plunge year-on-year and a 33.3% drop sequentially. The net profit margin shrank to a wafer-thin 0.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 11.88YoY +6.4% | 11.72 | 11.17 |
| Profit (₹ Cr) | 0.04YoY -71% | 0.06 | 0.14 |
| Net Profit Margin | 0.3%YoY -75% | 0.5% | 1.2% |
Why the top line didn't help
The profit crash was not due to weak demand. According to a report by scanx.trade, revenue growth was driven by a 41% jump in overseas sales. The core problem was a staggering 33.1% year-on-year surge in the cost of materials consumed, which severely outpaced the 6.3% revenue growth. This single item crushed gross margins.
Total expenses rose 7.9% from a year ago, further pressured by a 12.2% increase in interest costs on the company's elevated debt. With a debt-to-equity ratio of 2.31, interest remains a persistent burden on its already thin earnings.
A stagnant outlook with no catalyst
Management provided no forward guidance or commentary on margin recovery in its latest filings, notes an analysis from StockFin.ai. There have been no announcements of new orders, capacity expansions, or strategic initiatives in recent quarters. The company appears locked in a cycle of stable, low-margin revenue with high financial leverage and no visible plan to break out.
The market reaction has been negative, reflecting this stagnation. MarketsMojo reported the stock has declined 27% over the past year and technical indicators signal bearish momentum. It currently trades at a P/E of 22.8, a 53% discount to the industry average, but this likely reflects fundamental concerns rather than value.
Key Points
- Revenue grew 6.4% year-on-year to ₹11.88 crore, supported by strong export performance.
- Net profit plummeted 71.4% to ₹0.04 crore as material costs surged 33.1%, devastating margins.
- The company operates with high leverage (Debt/Equity of 2.31) and has provided no outlook for operational improvement.
- The stock has underperformed, falling 27% in the past year amid persistent profitability challenges.
Hexa Perspective
This quarter underscores a structural issue for Shivagrico: it cannot convert sales into earnings. The export-led revenue gain is positive, but without pricing power or cost control, it's meaningless for shareholders. The high debt load limits financial flexibility, making a turnaround reliant on operational efficiency that has yet to materialize. Until there is evidence of sustained margin recovery or a strategic shift, the company remains in a precarious, cash-constrained stalemate.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.