Shilp Gravures (SHILGRAVQ) Q2 FY27 Profit Collapses as One-Off Income Vanishes
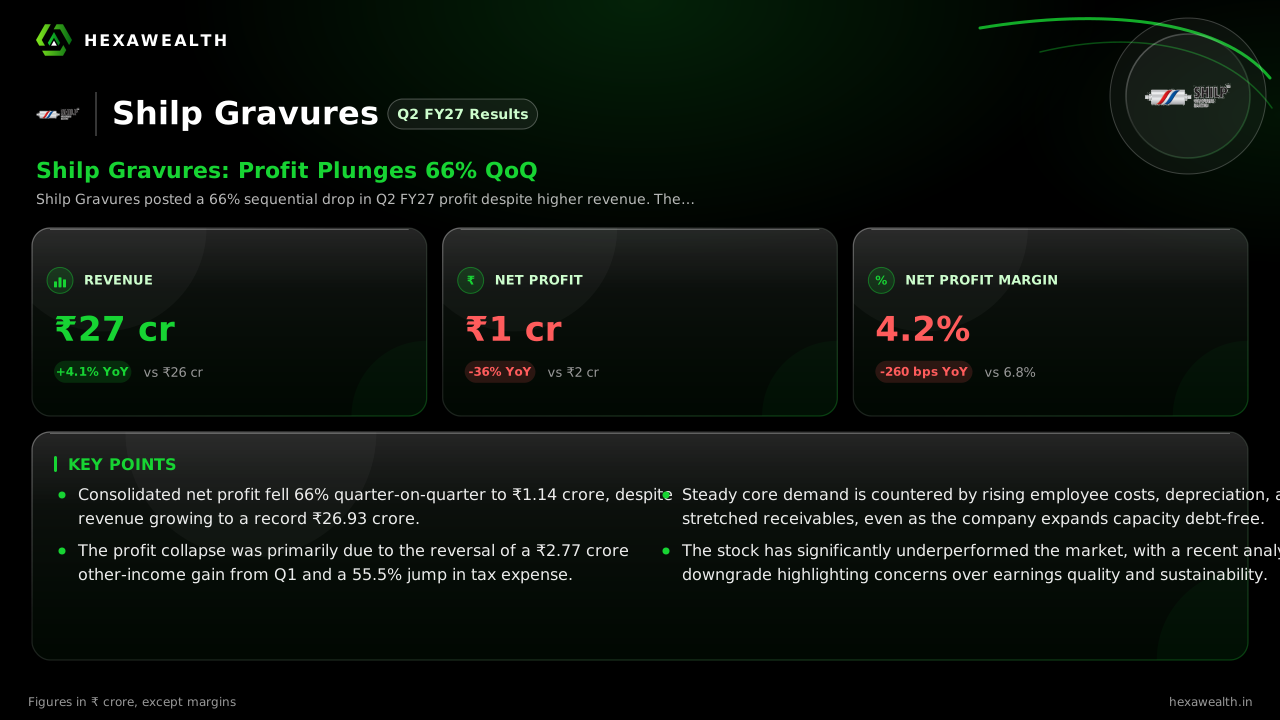
Revenue grew 4% year-on-year, but net profit fell 36% as a large other-income gain from the previous quarter reversed and tax expenses surged.
Shilp Gravures posted a 66% sequential drop in Q2 FY27 profit despite higher revenue. The collapse was driven by the absence of a one-off income gain and a sharp rise in tax costs, overshadowing steady demand for its core gravure rollers.
For a niche manufacturer like Shilp Gravures, steady demand for its printing cylinders should translate into predictable earnings. The September quarter delivered the demand, with revenue reaching a record high, but the bottom line told a different story entirely.
Consolidated revenue rose 4.1% year-on-year to ₹26.93 crore. Net profit, however, fell 35.6% to ₹1.14 crore. The sequential picture is starker, with profit down 66% from the June quarter. The net profit margin collapsed to 4.2%, down 910 basis points from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 26.93 | 25.20 |
| Profit (₹ Cr) | 1.14 | 3.35 |
| Net Profit Margin | 4.2% | 13.3% |
The One-Off That Distorted the Trend
The dramatic quarter-on-quarter profit swing stems from volatile other income. According to reports from scanx.trade and multibagg.ai, a significant ₹2.77 crore of other income boosted Q1 profit. This reversed to a loss of ₹0.12 crore in Q2, creating a nearly ₹2.9 crore swing that explains most of the sequential decline.
Costs That Are Here to Stay
Beyond that reversal, a structural cost increase weighed on profits. Employee costs and depreciation rose both year-on-year and sequentially, as noted by multibagg.ai. More critically, the tax expense surged 55.5% year-on-year to ₹1.23 crore.
Reports attribute this to higher deferred tax liabilities. This elevated tax rate, over 50% of pre-tax profit, turned a modest 1.8% standalone pre-tax profit growth into a steep net profit decline.
A Capacity Bet Amid the Squeeze
The company is betting on growth, funding a new Bengaluru plant entirely from internal accruals. As per zerodha.com, this will lift capacity by over 19%. The move targets South Indian markets, but it comes as operational costs are rising and working capital is stretching, with trade receivables up significantly.
The stock has reflected these pressures, down 43% over the past year. MarketsMojo downgraded the stock to 'Strong Sell' following the results, citing earnings volatility and the lack of institutional investor interest.
Key Points
- Consolidated net profit fell 66% quarter-on-quarter to ₹1.14 crore, despite revenue growing to a record ₹26.93 crore.
- The profit collapse was primarily due to the reversal of a ₹2.77 crore other-income gain from Q1 and a 55.5% jump in tax expense.
- Steady core demand is countered by rising employee costs, depreciation, and stretched receivables, even as the company expands capacity debt-free.
- The stock has significantly underperformed the market, with a recent analyst downgrade highlighting concerns over earnings quality and sustainability.
Hexa Perspective
The quarter exposes a core tension: Shilp Gravures' operating business is stable, but its reported profits are hostage to volatile non-operational items and a now-higher tax burden. The new Bengaluru facility may drive volume, but it does not directly address the margin pressure from rising costs.
Investors are weighing whether the record revenue marks a turning point or if profitability will remain subdued. The path to a re-rating requires several quarters of clean, tax-normalized earnings that finally leverage the company's niche leadership and new capacity.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.